
BHP
BHP is an Australian mining company, founded at Broken Hill in 1885, that today mines iron ore, copper and coal.
 10:32
Tata Group is India’s oldest and largest conglomerate — founded in 1868, built on cotton, steel, and infrastructure — not software, algorithms, or venture rounds.




Hemköp is a Swedish supermarket chain owned by Axfood. It operated around 200 stores in 2024. Its business model relies entirely on physical retail scale within a consolidated ownership structure. No data is provided on margins, digital performance, private label, or customer behaviour. Its value lies in infrastructure reuse — not innovation.


Bear Stearns collapsed because its business model depended on continuous short-term funding — and when counterparties stopped rolling over repo loans, liquidity vanished faster than capital could be deployed. Its balance sheet held value, but confidence did not. The firm was sold to JPMorgan Chase in a Fed-brokered fire sale.

The RJR Nabisco deal was a $25 billion leveraged buyout led by KKR in 1988 — the largest in history at the time. KKR’s $109-per-share bid prevailed over RJR management’s $112 offer because it was guaranteed. The transaction relied on institutional equity co-investors and a hostile tender offer. Post-acquisition, KKR repaid debt through asset sales and restructuring. Over 2,000 workers lost their jobs, most taking 5.6 months to find new work, and 72% who were rehired earned less than half their previous incomes.
ArcelorMittal is the world’s second-largest steelmaker — a $33 billion hostile merger of Mittal Steel and Arcelor in 2007. It operates across mining, smelting, and recycling in 14 countries. In 2025, it produced 55.6 million tons of steel against 74.6 million tons of capacity — 53% in Europe, 40% in the Americas. It sources 72% of its iron ore and 91% of its coke internally. The Mittal family surrendered control to close the deal. It is not a technology company. It is not growing. It is a vertically integrated commodity producer whose scale is structural, not strategic.
Barrick Mining is a gold-and-copper extraction company built through strategic acquisitions — not innovation, not discovery, not vertical integration. Its value lies in scale: 89 million ounces of gold in reserves, 3.91 million ounces produced in 2024, and a history of absorbing rivals like Placer Dome. But its governance fails where operations meet people: in 2008, Peter Munk personally silenced testimony about violence at Porgera. That gap — between reserve size and human accountability — is the real story.
Biedronka is a Polish discount supermarket chain owned by Portuguese group Jerónimo Martins. It operates 3,730 stores in Poland, employs 84,000 people, and accounts for approximately 70% of its parent’s sales. Its model relies on high-volume, low-margin sales of local and own-label goods — not differentiation or premium pricing. Its sole international move — one store in Slovakia, opened March 2025 — shows no evidence of traction. Its strength is also its risk: extreme geographic concentration in Poland.
Birks Group is the legal successor to Henry Birks and Sons — a Canadian jeweller founded in 1879, vertically integrated from design to retail, with manufacturing roots in Roden Bros. and national reach built through owned stores and co-branded acquisitions. Its 2005 merger with Mayors was a structural consolidation, not a new beginning.

Google DeepMind is a research lab, not a business. Its value lies in its ability to produce peer-recognised scientific milestones — not revenue, not IP licensing, not product deployment. It proves that one company can fund high-risk, long-horizon AI research at industrial scale — but only by insulating it entirely from market logic.

DiDi is a Chinese mobility technology company founded in 2012 by Cheng Wei in Beijing. It offers ride-hailing, taxi dispatch, bike sharing, vehicle leasing, food delivery, automobile services, and electric vehicle development. It merged with Kuaidi Dache in 2015 and acquired Uber China in 2016. It listed on the NYSE in June 2021 and was delisted in June 2022 after a $1.2 billion fine and app removal over data security concerns.

eBay acquired PayPal on October 3, 2002, for $1.4–$1.5 billion. It shut down its competing Billpoint service three months later. PayPal became the dominant, user-chosen payment method on eBay — used in over 70% of auctions and ~25% of closed listings — and by Q3 2012 accounted for 40% of eBay’s revenue ($1.37B). The deal was not about innovation. It was about controlling the checkout.
Enron was an American energy, commodities and services company founded in 1985 through a merger. It grew into a major electricity, natural gas, communications, and pulp and paper company — then collapsed due to institutionalised, systematic accounting fraud. Its 2001 bankruptcy was the largest fraud-related bankruptcy in U.S. history. It reorganised as Enron Creditors Recovery Corp. in 2004.
ExxonMobil is the largest U.S.-based oil and gas company. It was formed in 1999 by merging Exxon and Mobil. It is vertically integrated across oil and gas and its chemicals division. It produces about 3% of the world’s oil and 2% of global energy. In 2024, it emitted 610 Mt of CO2 — 1.58% of global emissions. It has faced widespread criticism and litigation over environmental incidents, including the 1989 Exxon Valdez oil spill, and for decades of climate change denial despite internal scientific accuracy.

Ferrari is a racing operation that sells cars — not the reverse. Its business model depends on using road-car revenue to fund Scuderia Ferrari, which in turn validates the brand, justifies price premiums, and dictates engineering direction. It was never financially self-sustaining in racing alone. Enzo Ferrari maintained control of racing through every ownership change — including Fiat’s 1969 investment — because that control was the source of legitimacy, not the cars.
Google is a search engine company founded in 1998 by Larry Page and Sergey Brin. Its core technology, PageRank, ranked websites by inbound links — a method co-published with Motwani and Winograd and patented by Stanford. Scott Hassan wrote the first implementation. The company launched from Susan Wojcicki’s garage. Its name misspelled 'googol' to signal scale. Initial funding came from Andy Bechtolsheim’s $100,000 cheque in August 1998. The sources say nothing about advertising, revenue, users, infrastructure costs, or market position beyond this.

JBS S.A. is the world’s largest meat processor by sales. On May 30, 2021, ransomware disabled its beef and pork slaughterhouses in the US, Canada, and Australia. It paid $11 million in Bitcoin. The White House attributed the attack to a Russian organisation; news outlets named REvil. REvil did not claim responsibility before its infrastructure vanished on July 13, 2021.



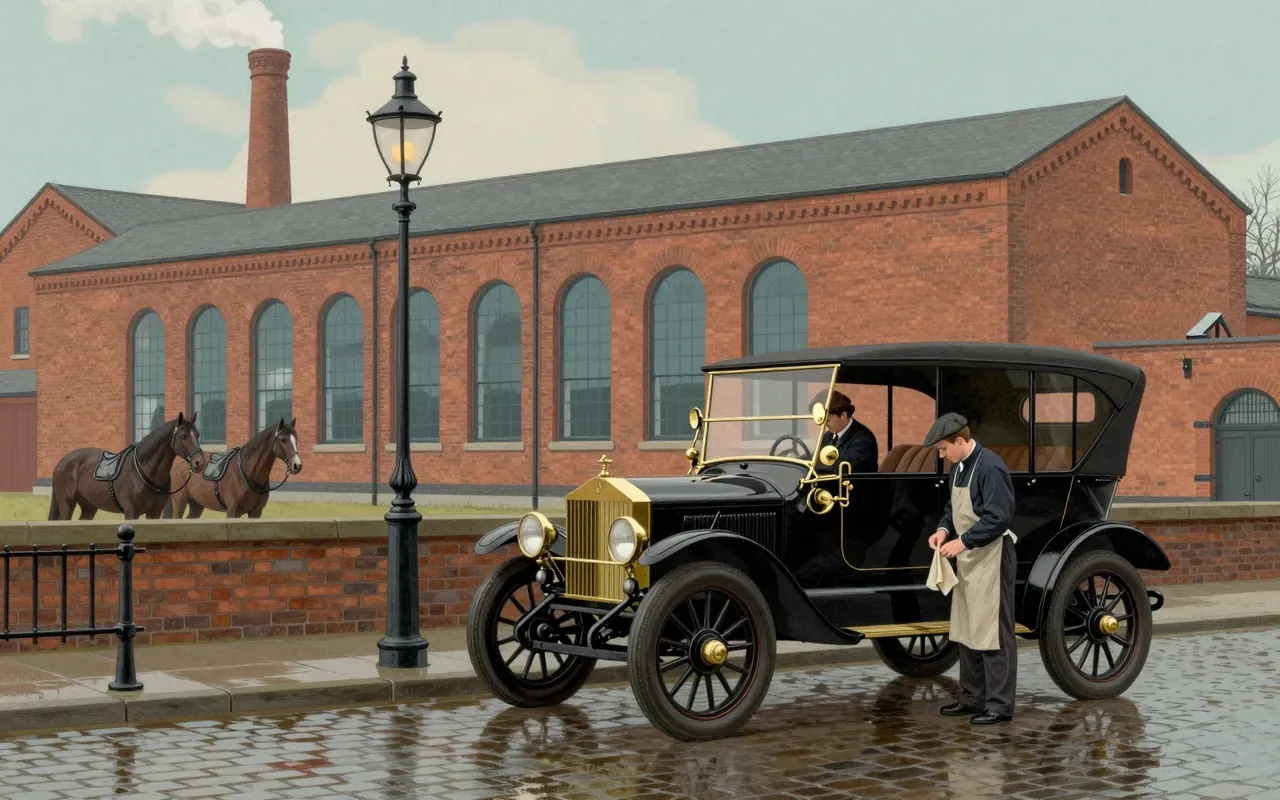
Rolls-Royce Limited was not a luxury brand first — it was an engineering firm that built cars to prove its method, then switched to aero-engines to survive war, then bet its existence on jet engines. Its collapse in 1971 was not a failure of ambition or invention. It was a failure of cost control in a single programme.
Surgutneftegas is a Russian oil and gas company formed in 1994 by merging state-owned entities holding major Western Siberian reserves. It became a private company in 1993 and has operated under Vladimir Bogdanov’s leadership since. Its business model relies on control of upstream assets, state-granted infrastructure rights, and export relationships — not capital markets, innovation, or transparency.

Malcolm McLean’s intermodal container was not an invention but a system — built around a 35-foot steel box sized for Pennsylvania highways, secured by Tantlinger’s corner castings and twistlocks, and operated by Sea-Land’s vertically controlled ships and cranes. It cut port handling time to eight hours — but only on one ship, at one port, under one company’s control. The real innovation was enforcing standardisation through ownership, not designing a better box.


The Thomson family is a dynastic holding structure anchored by a UK hereditary peerage and centred on The Woodbridge Company. Its wealth is not generated by visible operations but preserved by title, trust law, and concentrated private ownership. Sherry Brydson’s 23.47% stake is the sole quantified anchor of its financial claim. No public revenue, valuation, or operational detail is disclosed — only lineage and control.
WeWork: Or the Making and Breaking of a $47 Billion Unicorn is a 2021 documentary film. It follows Adam Neumann, founder and leader of the real estate company WeWork, who was forced out after a failed IPO. The film centres the collapse on that removal — not on debt, defaults, or unit economics.
ANA is Japan’s largest airline, rooted in a 1952 helicopter-and-aeroplane transport company. It launched Japan’s first postwar scheduled flight by a Japanese pilot in December 1953, added passenger service on the Osaka–Tokyo route in February 1954, and scaled into a dominant domestic carrier. Its growth reflects regulatory privilege more than competitive differentiation. No financials, pricing, or cost structure are disclosed in the source material.
Free is a vertically integrated French ISP that built its own networks, hardware, and pricing model — rejecting reliance on incumbents and subscription lock-in. It achieved profitability and low churn through infrastructure control and disciplined bundling, not venture funding or hype.
E.Leclerc is a French retailers’ cooperative founded in 1948. It pioneered the hypermarket format in 1964, adopted self-service retailing from the Félix Potin model, launched wine fairs in 1973, discontinued disposable plastic bags in 1996, introduced the Repère brand in 1997, and expanded internationally starting with Pamplona in 1992 and most recently into Luxembourg in 2023 via acquisition.
Magnit is a Russian food retailer founded in 1994 in Krasnodar by Sergey Galitsky. It grew rapidly from a regional chain into a national leader, adopting the convenience store format in 2004 and expanding to 1,000 stores by 2000 and 1,500 by 2005—surpassing Pyaterochka in revenue. By 2010 it ranked among the world’s top 250 retailers (Deloitte), and in 2014 became Russia’s largest importer. Its growth continued with milestones including 10,000 stores (2015), entry into pharmacy and drogerie formats, and strategic acquisitions like Dixy (2021) and Samberi (2024). Ownership shifted significantly after 2018, with Marathon Group becoming the largest shareholder in November 2021. Management transitioned from Galitsky to external CEOs starting in 2018, and the company pursued vertical integration via in-house production facilities and distribution infrastructure.

OMV is Austria’s major integrated oil- and gas company, founded in 1956 as the successor to the Soviet Mineral Oil Administration in occupied Austria. It makes money from refining crude oil at Schwechat, importing oil via the Adria–Vienna Pipeline from Trieste, selling natural gas supplied under contract with the Soviet Union, and operating transit infrastructure like the Trans-Austria Gas Pipeline. Its vertical integration worked: Schwechat refinery (1960), Soviet gas supply (1968), Adria–Vienna Pipeline (1970), and Trans-Austria Gas Pipeline (1974) formed a self-reinforcing system that locked in Austria’s role as a Central European energy node. OMV’s foundational model does not address decarbonisation, renewable generation, or energy storage. Its 1956–1974 expansion relied entirely on fossil fuel import, processing, and transit — with no indication of diversification beyond that scope in the source material. OMV shows how a national energy company can be built not through innovation or market creation, but through sequential infrastructure capture: refinery, pipeline, gas contract, transit corridor — each reinforcing the others’ value. Yes — as a case study in state-origined energy integration, infrastructure-led regional positioning, and Cold War-era resource diplomacy. Not as a model for modern energy transition strategy.
Peloton Interactive is an American exercise equipment and media company founded in January 2012 in New York City. It sells Internet-connected stationary bicycles, treadmills, and rowers equipped with touchscreens that stream live and on-demand fitness classes through a subscription service. Built-in sensors track metrics such as power output, providing real-time performance feedback and leaderboard rankings. Peloton charges $49.99 monthly for equipment-based access and $12.99 for app-only access. Its first bike sold on Kickstarter in 2013 at an early-bird price of $1,500; its first commercial Internet-connected bike launched in 2014. The company faced safety recalls (Tread+ in 2021, Bike PL01 in 2023), leadership changes (Foley stepped down as CEO in 2022, McCarthy resigned in 2024, Stern became CEO in 2025), and a sharp valuation decline—from $8.1 billion at IPO in 2019 to ~$1.3 billion by June 2024.

Rio Tinto is a British–Australian multinational mining company founded in 1873, headquartered in London and Melbourne, and operating globally as a major producer of copper, iron ore, aluminium, and lithium. Its history includes early dominance in Spanish copper production, strategic diversification after 1925, pivotal mergers — notably with Consolidated Zinc in 1962 and Alcan in 2007 — and extensive international expansion. The company is dual-listed on the London and Australian stock exchanges and has faced recurring criticism over environmental damage, corruption allegations (especially in Guinea), human rights concerns (e.g., Juukan Gorge), workplace culture issues, and legal challenges related to bribery and espionage. Its operational structure spans four product-based business units and numerous subsidiaries across six continents, with core assets concentrated in Australia and Canada.
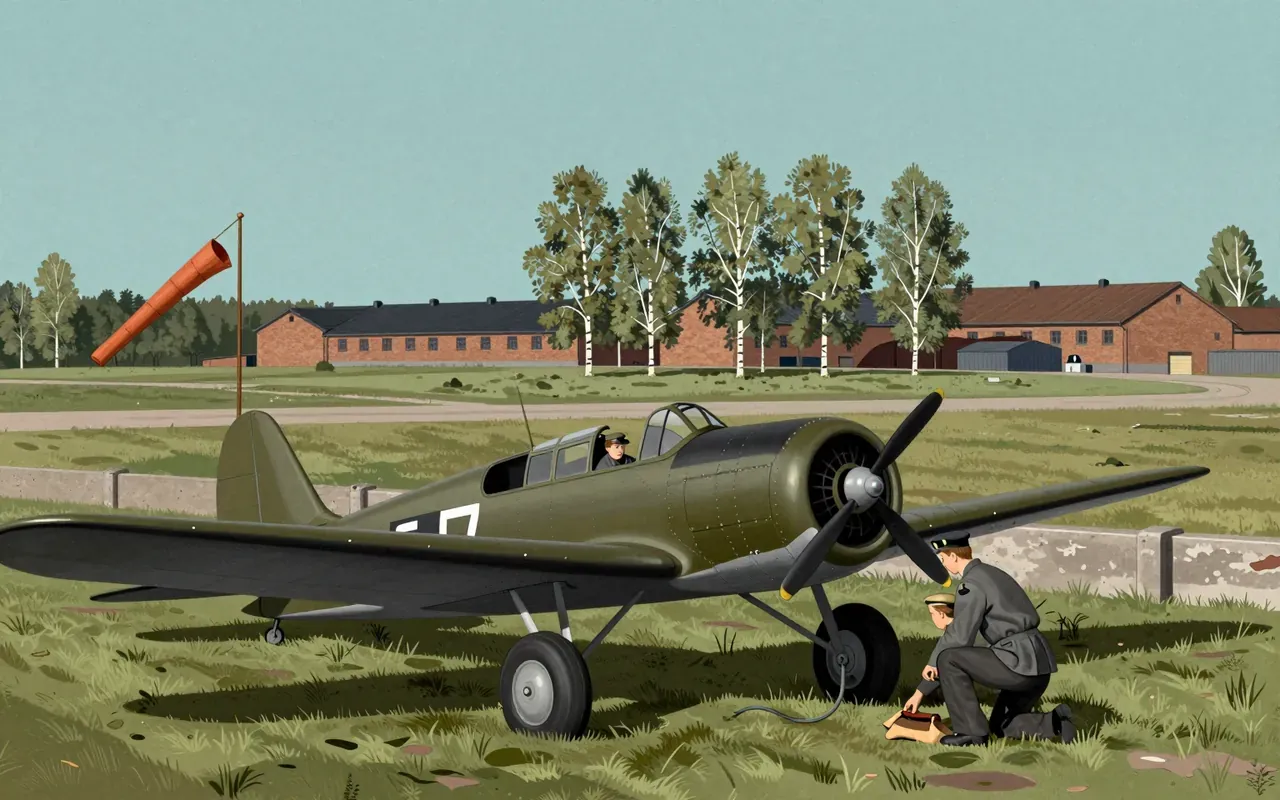
Saab AB is a Swedish aerospace and defence company founded in 1937 by AB Bofors to build aircraft domestically. It merged with ASJA in 1940, developed its first aircraft — the SAAB 17 — which flew on 1940-05-18, began automobile production in 1947, merged with Scania-Vabis in 1968, changed its name to Saab AB in May 1965, and was re-established as an independent entity in 1995 after de-merger.
Singapore Airlines is a state-aligned, operationally diversified aviation group—not a founder-led startup. Its value lies in infrastructure leverage, not narrative.
Vedanta Limited is a mining and metals company built on acquisitions, offshore holding structures, and regulatory navigation—not on technological differentiation or market creation.
Aldi is not a single company. It is two legally and financially separate firms — Aldi Nord and Aldi Süd — born from a 1960 split triggered by a disagreement over cigarettes. They share a name, a cost-cutting method, and a lineage, but no ownership, no shared board, and no central strategy. Their model works because it eliminates variables: no fresh produce, no advertising, no unsold stock, no large stores, no rebates beyond the legal 3%. By 1960, that method had scaled to 300 stores. Family control ended by 2002. The business survives not through narrative, but through subtraction.
Biocon is a rare case of a biotech company built without VC, without US incorporation, and without founder exit—its growth was constrained and enabled by Indian law, not Silicon Valley logic.
BT Group is a British multinational telecommunications holding company headquartered in London, England. It operates in around 180 countries and is the largest provider of fixed-line, broadband and mobile services in the UK. Its origins date back to the founding in 1846 of the Electric Telegraph Company. BT Group as it came to be started in 1912, when the General Post Office, a government department, took over the system of the National Telephone Company, becoming the monopoly telecoms supplier in the UK. The Post Office Act of 1969 led to the GPO becoming a public corporation, Post Office Telecommunications. The British Telecom brand was introduced in 1980, and became independent of the Post Office in 1981. British Telecom was privatised in 1984, becoming British Telecommunications plc, with some 50 percent of its shares sold to investors. BT runs the telephone exchanges, trunk network and local loop connections for the vast majority of British fixed-line telephones. The General Post Office (GPO) was the state postal system and telecommunications carrier of the United Kingdom until 1969. Established in England in the 17th century, the GPO was a state monopoly covering the dispatch of items from a specific sender to a specific receiver; it was overseen by a Government minister, the Postmaster General. The GPO was abolished by the Post Office Act 1969, which transferred its assets to the Post Office, so changing it from a Department of State to a statutory corporation. Responsibility for telecommunications was given to Post Office Telecommunications, the successor of the GPO Telegraph and Telephones department. In 1980, the telecommunications and postal sides were split prior to British Telecommunications' conversion into a totally separate publicly owned corporation the following year as a result of the British Telecommunications Act 1981. When new forms of communication came into existence in the 19th and early 20th centuries the GPO claimed monopoly rights on the basis that like the postal service they involved delivery from a sender and to a receiver. The Telegraph Act 1869 conferred on the Postmaster General a monopoly in telegraphic communication in the UK. The Wireless Telegraphy Act 1904, which granted control of radio waves to the General Post Office, who licensed all senders and receivers.
Carrefour is a foundational case in retail format design — not technology, not branding, not finance — but physical integration, location logic, and incremental scaling.

Emirates is a state-owned UAE flag carrier founded in 1985 after Gulf Air reduced Dubai services. It operates over 3,600 weekly flights from Dubai International Airport’s Terminal 3, serves 150+ cities across six continents, and ranks third globally by passenger volume and second by freight volume. Its ownership lies with Dubai’s Investment Corporation of Dubai, and its cargo arm is Emirates SkyCargo. It is not part of any global airline alliance.
Godrej & Boyce is not a story of disruption but of continuity — sustained by refusing to outsource precision, testing claims in fire, and anchoring engineering to national need. Its business model has never been about scaling a single product, but about retaining sovereign capability across generations.
Hyundai Motor is a state-facilitated, scale-first automaker whose power lies in integration — not invention. It controls the largest single auto plant on earth, ranks third globally by output, and sells more hybrids than EVs. Its origin story is contested across sources. Its value is in execution, not narrative.
Kaufland is a German hypermarket chain founded in 1984 in Neckarsulm, part of the Schwarz Gruppe, and developed by Dieter Schwarz as a full-range alternative to Lidl’s discount format. It makes money by selling groceries and general merchandise from hypermarkets averaging over 10,000 m², operating under vertical integration — running in-house bakeries since 1994, meat processing facilities, and organic product lines launched in November 2018. Its strategy of acquiring competitor assets (e.g., 12 famila stores and a Cash-&-Carry-Markt in January 2010) and rebranding existing Handelshof locations gave it rapid scale. It dominates eastern Germany today — a result of opening its first East German store in Meißen in 1990, immediately after reunification. Its Australian expansion failed within a year (2019–2020), exposing limits to its model outside culturally and logistically aligned markets. It does not operate outside Europe. The gap between Kaufland’s self-presentation as a sustainability- and quality-driven retailer (e.g., 2021 decarbonisation strategy, organic range) and its operational reality — acquisitions, rebranding, and regional dominance built on post-reunification timing and antitrust-cleared takeovers — reveals how legacy retail power consolidates without innovation.
Meituan is a Chinese technology company headquartered in Beijing that operates a platform for local services, including on‑demand food delivery, in‑store services, consumer reviews under Dazhong Dianping, hotel and travel bookings, and instant retail. It monetises through fees on its platform, taking a commission on food delivery orders and charging merchants for booking and in‑store services. Meituan’s rapid user growth is driven by its extensive coverage of local services, its integration of food delivery, in‑store services, and hotel bookings creating a one‑stop shop, and its large merchant base of 14.5 million active merchants providing network effects. Meituan faces regulatory scrutiny in China, its 2021 post by Wang Xing triggered a 7.1 % share plunge and anti‑monopoly investigation, and the company has been subject to scrutiny by Beijing Municipal Human Resources and Social Security Bureau. Meituan demonstrates the power of a diversified local‑services platform, its ability to scale across cities and internationally shows the importance of network effects, and its regulatory challenges highlight the need for compliance awareness. Meituan offers a case study in rapid scaling and diversification, but its regulatory risks caution investors.
Migros is a Swiss retail cooperative founded in 1925 in Zurich by Gottlieb Duttweiler as a private enterprise delivering six staple goods via five lorries to households with limited market access.
Morrisons is a UK supermarket chain founded in 1899 as an egg and butter stall in Rawson Market, Bradford. It grew regionally until the 2004 Safeway acquisition gave it national reach across Great Britain and one store in Gibraltar. As of 2021, it operated 497 stores, employed 110,000 people, and served ~11 million customers weekly. It was listed on the London Stock Exchange until its October 2021 acquisition by Clayton, Dubilier & Rice. Since then, it has struggled financially and fallen to fifth place in UK market share (8.6%), overtaken by Aldi in September 2022.

RTL Group is a broadcast-first European media operator built through merger, not innovation. Its structure reflects regulatory fragmentation, not technological ambition.

Syngenta is a global agricultural technology company headquartered in Basel, Switzerland, operating primarily in crop protection and seeds for farmers. It was founded in 2000 by the merger of the agrichemical businesses of Novartis and AstraZeneca. In 2004, Syngenta Seeds purchased Garst and Golden Harvest Seeds. In February 2016, ChemChina offered to purchase Syngenta for $43 billion, a deal Syngenta unanimously recommended to shareholders. In April 2017, U.S. and European antitrust authorities approved ChemChina's acquisition of Syngenta. To secure regulatory approval, ChemChina agreed to divest pesticide production of paraquat, abamectin, and chlorothalonil.
Takeda’s origin story is misaligned with its present identity: it began as a repackaging merchant, not a drug developer. Its longevity reflects adaptability, not continuity.
Vivendi is a French investment company headquartered in Paris, founded in 1853 as Compagnie générale des eaux. It evolved through mergers and diversification — notably becoming Vivendi Universal in 2000 via merger with Groupe Canal+ and Seagram — before reverting to Vivendi in 2006. From 2021, it executed a strategic spin-off of its core assets, culminating in 2024 with the separation of Canal+, Havas, and Louis Hachette Group, transforming itself into a focused investment company holding stakes in media and entertainment firms.
ABB is a post-merger industrial incumbent whose value lies in proven, regulated, physical infrastructure — not software, platforms, or scalability stories.

Alfa Romeo was not founded by Nicola Romeo. It was founded in 1910 as A.L.F.A. to acquire the assets of the failing Italian Darracq subsidiary. Romeo acquired it in 1915, took full ownership by 1918, renamed it in 1920, launched the first Alfa Romeo-branded car in 1921, won the inaugural 1925 World Manufacturers’ Championship, faced near-liquidation in 1927 due to poor investments, departed formally in 1928, and was taken over by the Italian state in 1933.
Alimentation Couche-Tard is a textbook case of geographic and operational scaling through acquisition and banner standardisation — not product, tech, or marketing innovation. Its model depends on acquiring undermanaged regional chains, stripping overlapping functions, and enforcing consistency in procurement and site selection. It reveals little about consumer behaviour or retail design, but much about how capital, real estate leverage, and decentralised execution combine to dominate fragmented markets.
Ambev is a case study in consolidation-driven profitability — not product-led growth. Its value came from regulatory navigation, cost discipline, and geographic sequencing, not brand, taste, or technology. It shows how monopoly conditions can be manufactured where competition is weak, not defeated.


Apollo Global Management is a $1.03 trillion alternative asset manager built on distressed-to-control investing, co-founded in 1990 by ex-Drexel bankers. It earns fees from pension funds, endowments, and sovereign wealth funds deploying capital across credit, private equity, and real assets. Its model works at scale—but its credibility fractures where leadership conduct contradicts its governance claims. The $158 million paid to Jeffrey Epstein did not disrupt operations, but it ended Leon Black’s tenure and exposed a rift between Apollo’s discipline-as-brand and its human risk.
Asda's origin story is a case study in opportunistic capital allocation — not disruption. It used regulatory shifts, tax law, and real estate terms to scale before it had a coherent brand or national footprint.



Biogen is a neurology-focused biotech that built scale via acquisition, not foundational science — and César Milstein, whose hybridoma work underpins modern antibody therapeutics, has no documented relationship to the company.

Blackstone is the largest alternative investment firm by AUM — $1.2 trillion as of September 2025, $1.3 trillion by Q1 2026 — built on a pivot from M&A advisory to merchant banking in 1987. Its founders lacked LBO experience but leveraged relationships to enter private equity, then scaled across asset classes using consistent mechanics: leverage, illiquidity, and fee-based capital aggregation. Its CEO held formal advisory access to the U.S. presidency, but that did not substitute for early fundraising credibility. The firm discloses neither performance nor risk metrics for its funds. Its growth reflects structural demand — not proprietary insight.


British Airways is the UK’s flag carrier, formed by state merger in 1974, privatised in 1987, and folded into IAG in 2011. It is the largest UK airline by fleet and international reach. It was the first passenger airline to earn over $1 billion on a single route in a year. It has a documented reputation for poor staff conduct, arbitrary service changes, and refusing compensation claims.

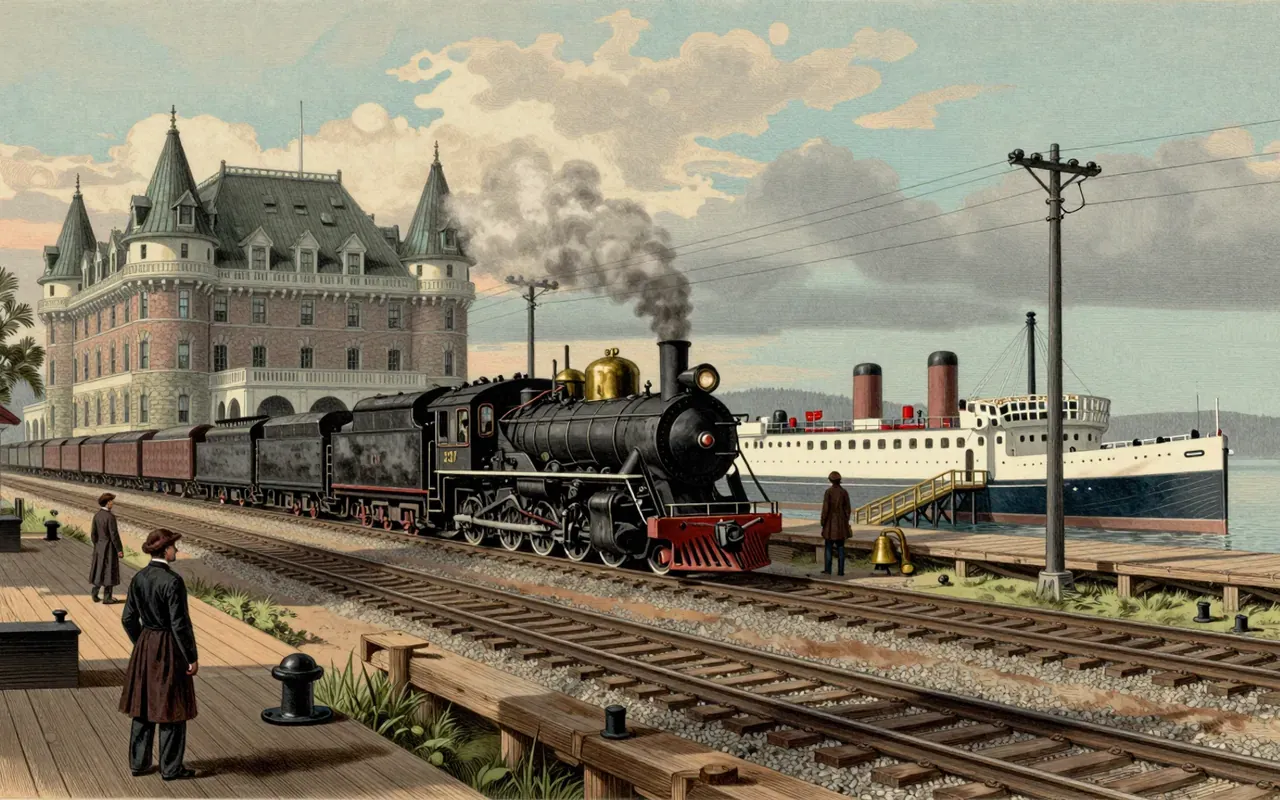
The Canadian Pacific Railway was not a startup, nor a disruptor — it was a state-contracted infrastructure monopoly, executed under tight political deadline and scaled through vertical integration. Van Horne’s genius lay not in invention but in orchestration: he turned a rail line into a self-reinforcing system of movement, messaging, lodging, and shipping — all funded by federal land grants, bonds, and tariffs, not market demand. Its success was geopolitical, not financial; its durability came from control of geography, not innovation.
Canadian Solar is a vertically integrated solar energy firm founded in 2001 by Dr. Shawn Qu, headquartered in Kitchener, Ontario, with operations spanning manufacturing, project development, and storage system provision.

Carlyle is a textbook case of how a firm leverages geography and timing — not product innovation — to dominate a financial services niche. Its business model remains fee-dependent, opaque, and unremarkable in mechanics. Its value lies in its path, not its current structure.

Caterpillar Inc. is the world's largest construction equipment manufacturer, founded in 1925 via merger, but rooted in Benjamin Holt’s continuous-track tractor innovation of 1904–1907.



Citroën was a French automobile manufacturer founded in 1919 in Saint-Ouen-sur-Seine. It pioneered four world-first production car technologies: front-wheel drive with unibody construction (1934), hydropneumatic self-levelling suspension (1954), modern disc brakes (1955), and swiveling headlights (1967). It also launched the 2CV in 1948, pioneering soft interconnected suspension. Citroën gained international reputation mass-producing armaments in WWI. It became the fourth-largest carmaker in the world in the 1930s, peaking in 1932 with the Traction Avant. Cost struggles aggravated by the Great Depression led to bankruptcy in 1934 and takeover by Michelin. Its double-chevron logo derived from André Citroën’s application of double helical gears, which he acquired after seeing them used by a Polish carpenter around 1900.
CME Group is a vertically integrated derivatives infrastructure operator. It runs exchanges, provides mandatory central clearing, and operates two spot platforms. In 2025, 81% of its revenue came from clearing and transaction fees, charged at $0.70 per contract across over 7 billion contracts. Volume increases during market volatility — a mechanical, observable feature. Its Bitcoin spot launch in May 2024 has no reported volume or revenue impact. Every major innovation — currency futures (1972), Globex (1987), IPO (2002) — was structural, not product-led.

De Beers is a case study in artificial scarcity — built not on geology or technology, but on merger, capital, and contract.
Dr. Reddy's Laboratories is a business case in disciplined vertical progression: API → branded formulation → export credential → finished product. Its early wins were tactical, not structural. No data on scale, margins, or longevity is provided — only sequence, timing, and pricing intent.
Eli Lilly and Company is a foundational case in how business infrastructure — not just discovery — creates pharmaceutical power. Its early bets on quality control, prescription gatekeeping, and regulation were deliberate, profitable, and durable. The sources confirm no modern financials or valuations, so analysis must stay anchored in its documented methods and milestones.



Etihad Airways is a state-owned UAE flag carrier launched in 2003 to project national presence globally. It operates passenger, cargo, and holiday services from Zayed International Airport using a fleet of 107 aircraft. It is the second-largest airline in the UAE after Emirates. Its business model relies on sovereign backing—not unit economics—to sustain scale beyond its home market’s natural demand.


FEMSA is a Mexican multinational beverage and retail company headquartered in Monterrey, operating the largest independent Coca-Cola bottling group in the world and Mexico’s largest convenience store chain. It reports US$26.9 billion in revenue (2019), ranks fifth-largest company in Mexico, and operates across Latin America via bottling plants, convenience stores, drugstores, fuel stations, and third-party logistics—and in the US via jan-san distribution. Listed on the Mexican Stock Exchange since 1978 and NYSE ADRs since 1998. FEMSA is the holding company of Cuauhtémoc Moctezuma Brewery—the culmination of Eugenio Garza Sada’s industrial expansion from a single brewery into Grupo Valores Industriales, which included Fábricas de Monterrey (1920), HYLSA (1942), Empaques de Cartón Titán (1936), and multiple acquired breweries.
Fiat’s early success came from disciplined scaling, not invention. It built volume, listed publicly, and dominated Italy’s auto market — all before 1910. Its story is about capital, control, and concrete.
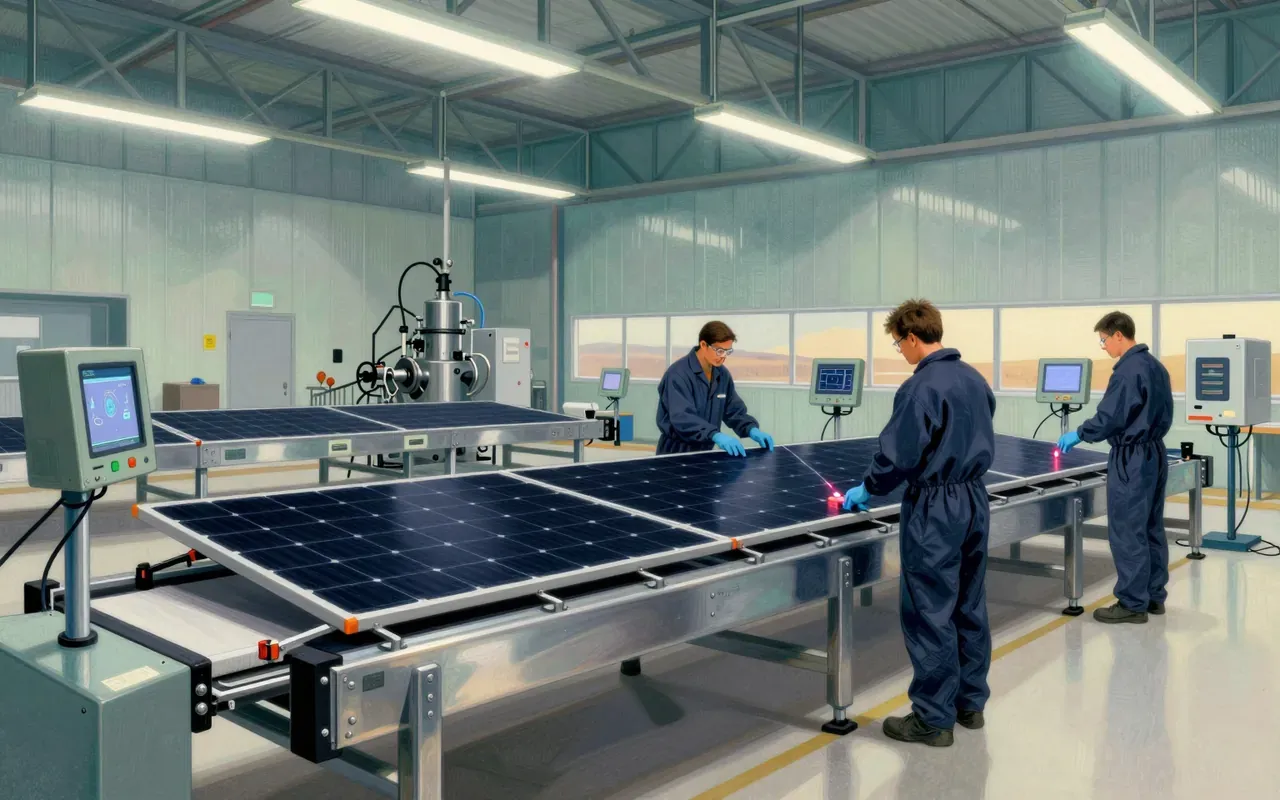
First Solar is a U.S. solar panel manufacturer that builds cadmium telluride (CdTe) thin-film modules in domestic factories. It was founded in 1990 as Solar Cells, Inc. by Harold McMaster, acquired and rebranded in 1999, and went public in 2006. Its technology diverges from mainstream silicon PV. As of March 2026, it had ~14 GW of annual domestic nameplate capacity across facilities in Ohio, Alabama, and Louisiana. It does not produce silicon panels, does not operate overseas factories, and does not integrate storage or software.


Genmab is a platform biotech — not a drug developer — built around two licensed and proprietary antibody generation methods. Its value is in reducing discovery risk and time, not in owning clinical or commercial outcomes.

George Weston Limited is a Canadian holding company founded in 1882, structured around two core assets: Loblaw Companies Limited and Choice Properties REIT.

Glencore is a vertically integrated commodity trader and miner whose power rests on controlling physical flows — especially zinc and copper — across jurisdictions. It emerged from Marc Rich + Co AG in 1994 after Rich was forced out following a failed zinc market corner. Its structure splits legal registration (Jersey), operational HQ (Baar), and oil-and-gas command (London). It holds no disclosed valuation or margin, but its 2010 market shares — 60% in zinc, 50% in copper — show where its leverage lies: not in brands or code, but in tons moved, stored, and priced across borders.


GSK plc is a British multinational pharmaceutical and biotechnology company formed in 2000 by the merger of Glaxo Wellcome and SmithKline Beecham. It traces its origins to Henry Wellcome’s 1880 co-founding of Burroughs Wellcome & Company. GSK developed the first malaria vaccine (RTS,S), markets WHO-listed essential medicines, and reported $42.4 billion in revenue and $9.32 billion in earnings in 2025. In 2012, it pleaded guilty in the US to unlawful drug promotion, failure to report safety data, and physician kickbacks — agreeing to a $3 billion settlement, the largest healthcare fraud case in US history and the largest in the pharmaceutical industry. The Wellcome Foundation Ltd., established by Henry Wellcome in 1924, was later sold to GSK following changes in UK charity law.


Husky Energy was a long-lived, vertically integrated petroleum company whose geographic reach and operational scope did not prevent its absorption into Cenovus Energy in 2021.


Imperial Oil was founded in 1880 as a Canadian response to Standard Oil’s expansion — a deliberate replication of Rockefeller’s integrated model. It quickly controlled 85% of national refining capacity. After failing to secure British ownership, its board sold 75% to Standard Oil in 1898, absorbing its Canadian subsidiaries. Post-1911 antitrust breakup, Imperial remained legally distinct but was wholly assigned to Jersey Standard — becoming Standard Oil’s exclusive vehicle for Canadian operations.


ICE is a financial infrastructure consolidator — not a technology innovator or market creator. It turned energy trading into a global clearing and exchange empire by acquiring failing or exposed rivals, shutting down physical floors, and layering data and mortgage tech atop core exchange revenue. Its business model depends on regulatory moats, scale-driven pricing, and vertical integration — not speed, intelligence, or user experience.

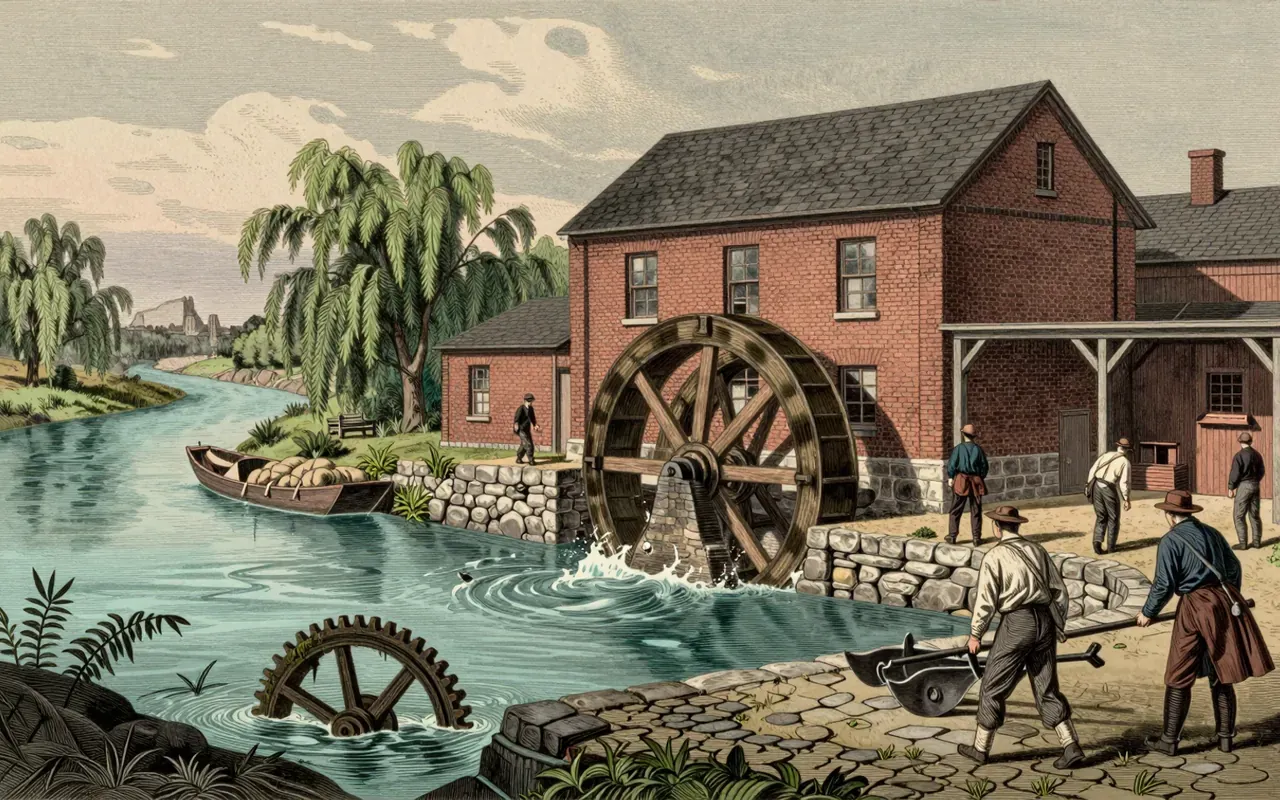
John Deere is not a tech company. It is a manufacturer whose first product solved a tactile, geographic problem — soil adhesion — with a repeatable material fix. Its growth followed physical logic: water power, then scale, then diversification. Financial services are noted but undated. Nothing in the sources supports claims about digital transformation, autonomy, or data-driven farming.
Johnson & Johnson began as a vertically integrated supplier of standardised, sterile medical consumables — selling trust, training, and readiness, not cures.

KKR is a foundational leveraged buyout firm whose early success relied on regulatory change, not market demand — and whose most famous deal was unprofitable. Its current scale reflects diversification beyond private equity, not enduring deal-making superiority.

KLM was not a private venture but a state-backed aviation instrument. Its longevity stems from institutional alignment — not market innovation.

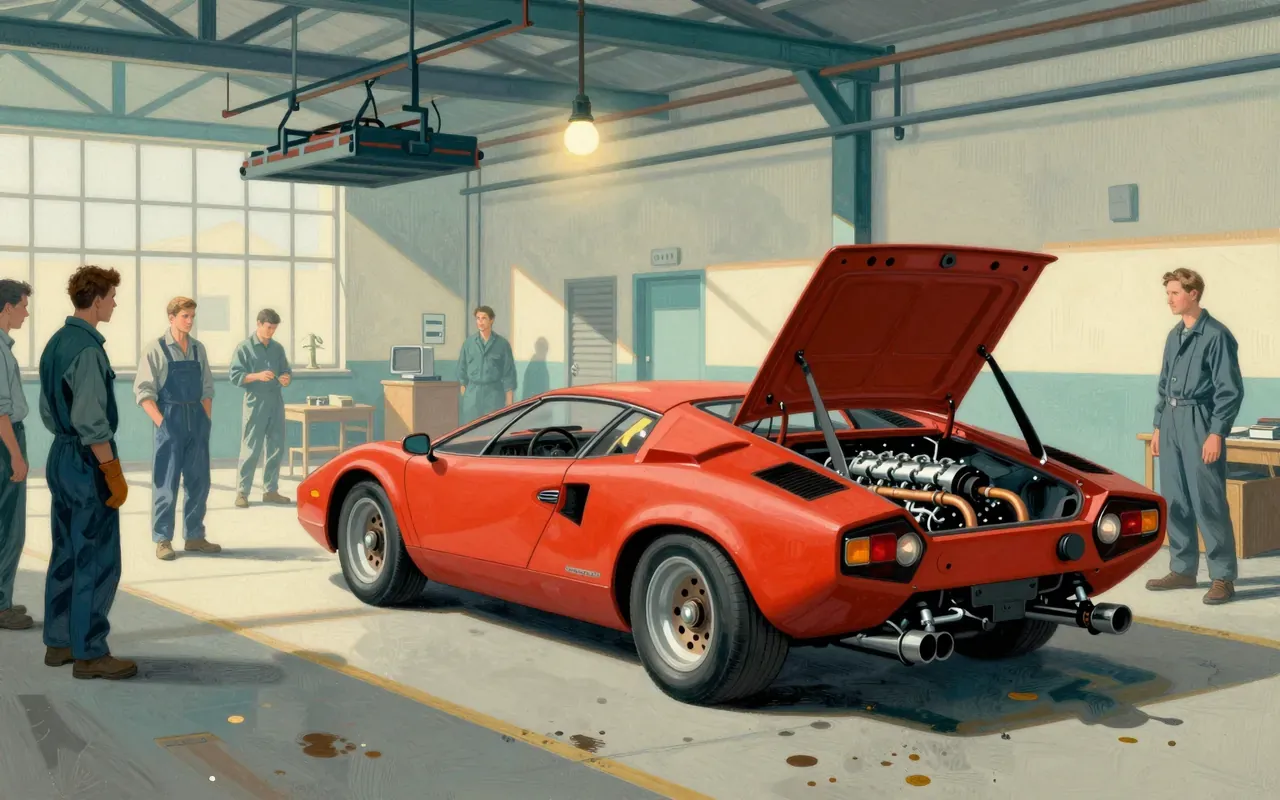
Lamborghini is a case study in disciplined positioning: a luxury carmaker built on agricultural engineering, anchored in one town, defined by one cultural metaphor, and repeatedly tested — and sometimes broken — by global economic forces.


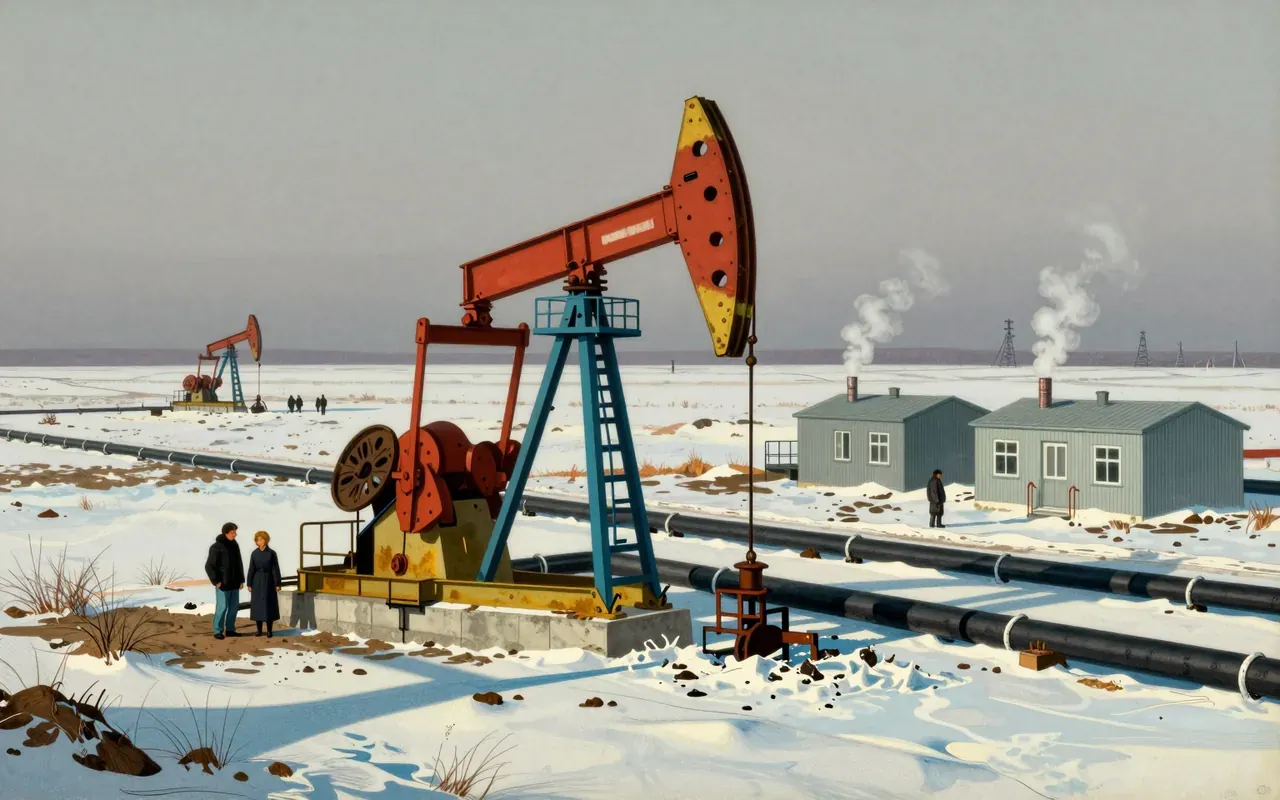
Lukoil is a Russian multinational energy corporation headquartered in Moscow, formed in 1991 by merger of three state-run western Siberian oil enterprises: Langepasneftegaz, Urayneftegaz, and Kogalymneftegaz.


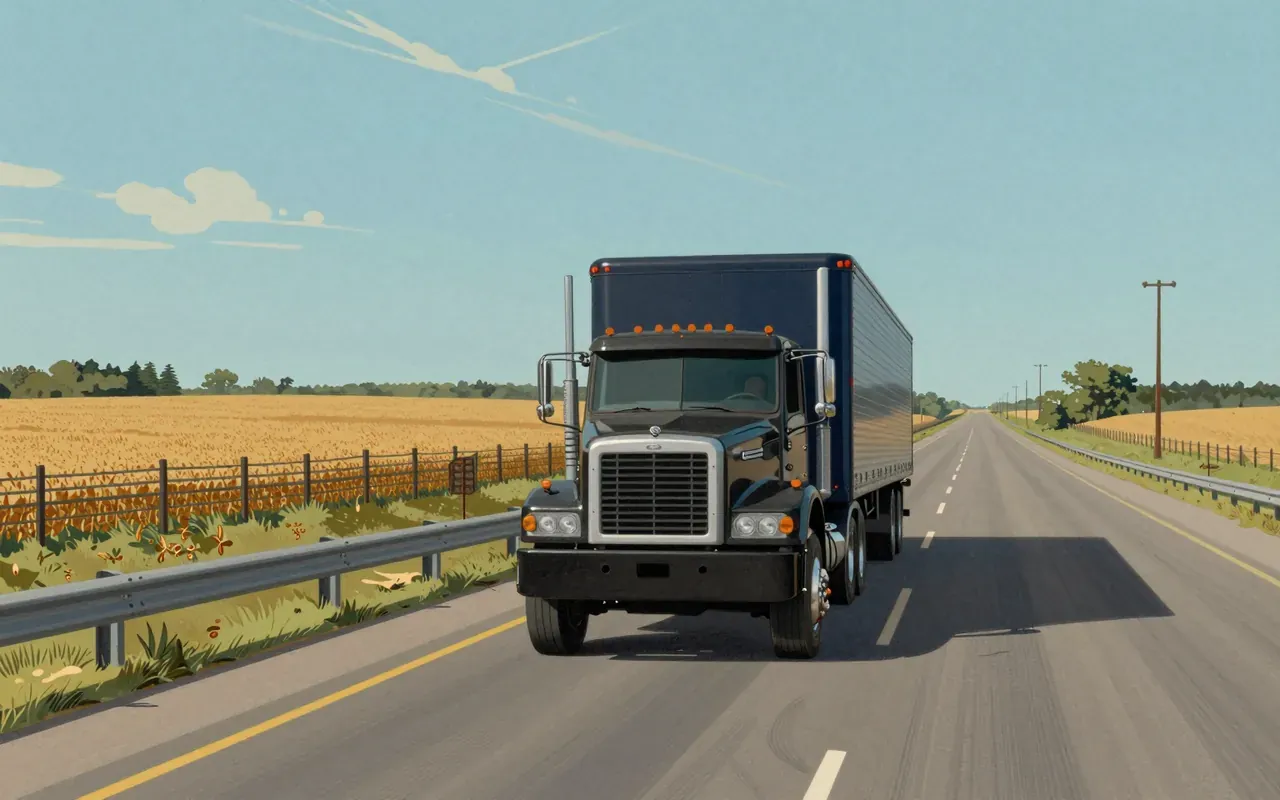
Mack Trucks is a vertically narrow, geographically mobile, and corporately subordinated industrial brand — sustained not by innovation or scale, but by consistent execution in a defined vehicle class and enduring customer trust in its vocational durability.

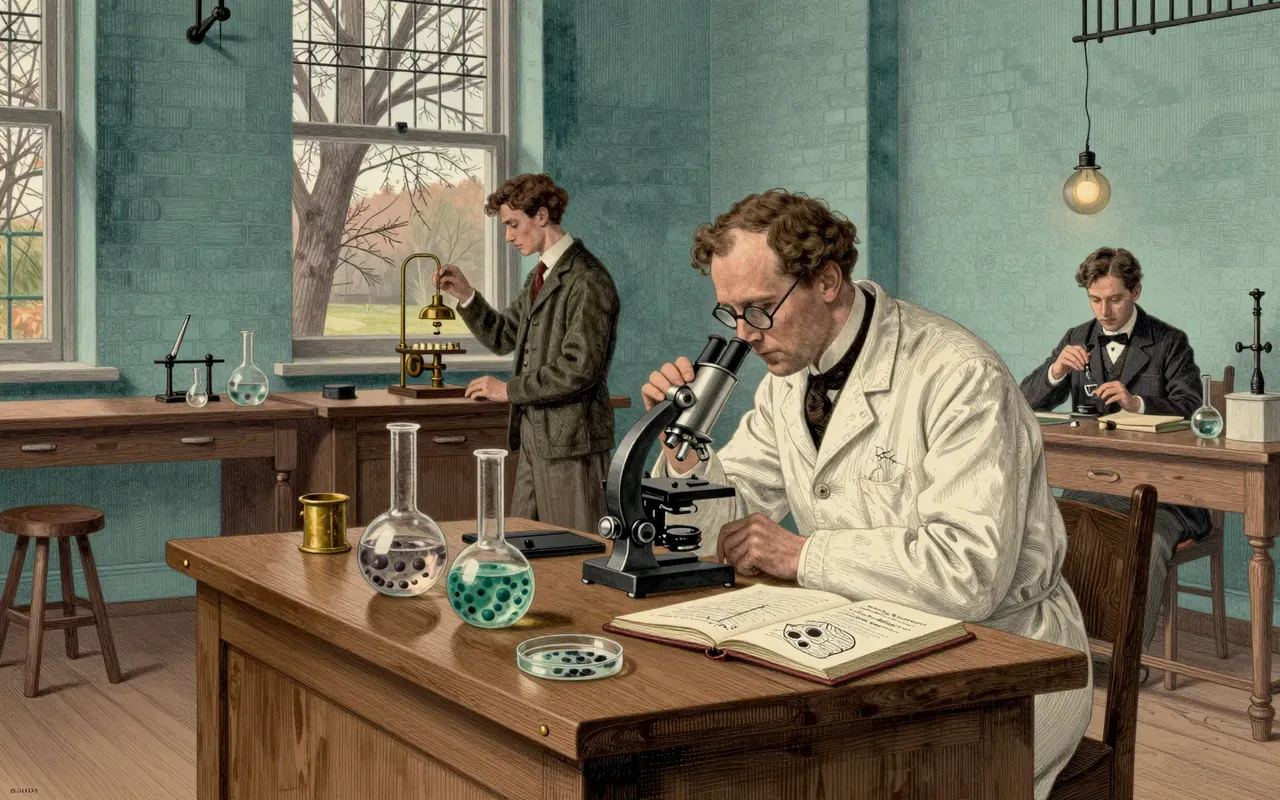
Merck & Co. is a multinational pharmaceutical company founded in 1891 as the American affiliate of the German Merck Group, made independent in 1919 after U.S. government expropriation and resale. Its early growth came from strategic mergers — not organic R&D — and its landmark streptomycin breakthrough relied on external academic research funded by the company. Under George W. Merck’s presidency (1925–1950), it developed synthetic vitamins, sulfas, antibiotics, and hormones, while simultaneously leading the U.S. biological weapons programme. The gap between its self-presentation as a scientific pioneer and its actual mechanics — acquisition, outsourcing, and state-aligned research — is the core of its business story.
Moody's Ratings is the credit ratings division of Moody's Corporation, rebranded from Moody's Investors Service in March 2024. It provides international financial research on bonds issued by commercial and government entities, operates as one of the Big Three credit rating agencies, uses a standardized ratings scale measuring expected investor loss in default, assigns ratings from Aaa (highest) to C (lowest), and was founded by John Moody in 1909 to produce manuals of statistics related to stocks, bonds, and bond ratings.


Nasdaq is not a disruptor — it is the incumbent infrastructure operator. Its value lies in ownership of exchange platforms, data feeds, and listing rules — not in technological novelty, which has long since been replicated. It works where liquidity and branding converge: tech IPOs, real-time data sales, and cross-border access. It falls short as a neutral arbiter: its incentives align with listed companies and high-frequency traders, not retail investors or public market integrity. The gap between its self-presentation as a ‘market enabler’ and its actual function as a toll collector is wide — and profitable.


Natura built a global cosmetics business using direct sales—not digital platforms—and anchored its identity in ethical sourcing and animal-testing bans. It listed on Brazil’s highest-governance stock exchange tier in 2004. But none of its stated commitments include third-party verification, cost impact, or enforcement mechanisms. Its scale—6.6 million consultants in 2018—is real. Its ethics are aspirational.
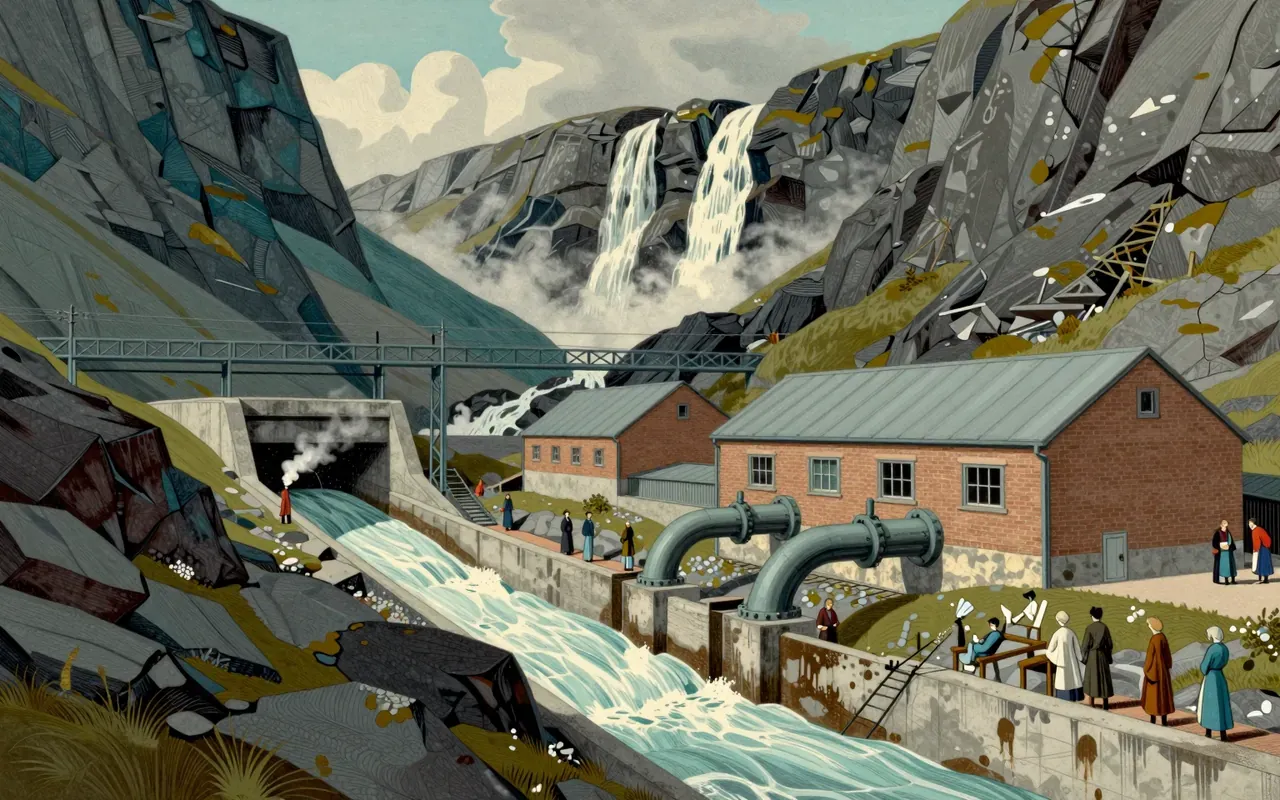
Norsk Hydro began as a single-purpose vehicle for Birkeland’s nitrogen-fixing arc — a physics experiment turned factory. Its early dominance came not from IP or management, but from locking in Norway’s hydropower geography. It survived obsolescence not through reinvention, but by ceding chemical control to IG Farben. Its WWII role — sole European heavy water producer — was accidental infrastructure reuse. Its current aluminium and renewables business shares no technology with its origin, only its dams, debt, and place.
Novatek is a state-tolerated gas monopoly-in-waiting: dominant domestically, absent internationally, priced by regulation not competition.

Peterbilt is a case study in acquisition-led industrial continuity: a timber operator bought a defunct truck maker to solve local hauling problems, engineered narrowly effective solutions, scaled only when external demand (military) appeared, and exited when land value exceeded truck value. Its legacy lies in execution, not vision.

Peugeot is the oldest car company in the world — but only because it formalised its automobile division in 1896, 86 years after its founding as a steel foundry. Its success came not from breakthrough invention, but from disciplined technology adoption, rapid iteration, and industrial scaling.
Pfizer’s origin story is not about curing disease — it is about solving chemical supply problems with fermentation. Its therapeutic dominance came decades after it mastered industrial microbiology under pressure.

Qantas was founded as a government-enabled airmail service — not a passenger airline — and its early survival depended entirely on public infrastructure needs, not market demand.
Regeneron is a biotech firm whose core innovation — the receptor trap — emerged from neurobiology, not pharmacology. It monetises that science via high-value partnerships and outsized government contracts, not broad platform dominance. Its success depends less on internal scale than on strategic leverage of public R&D funding.
Renault’s early business was built on three concrete moves: selling before incorporation, vertically integrating engine production, and dominating municipal taxi supply — not on vision, branding, or disruption.


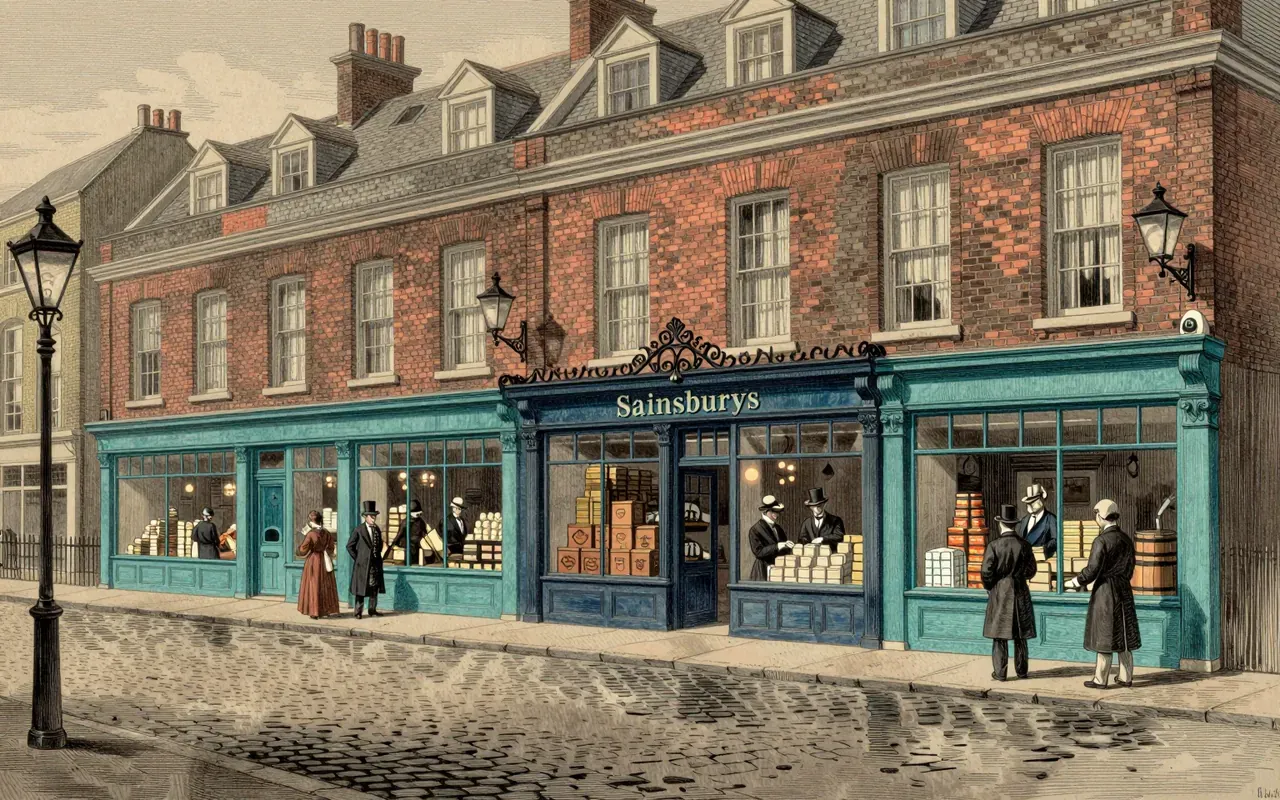
Sainsbury’s is the second-largest UK supermarket chain. It was the largest UK grocery retailer for most of the 20th century. It was founded in 1869 as a partnership by John James Sainsbury and Mary Ann Sainsbury at 173 Drury Lane in London. It began selling fresh foods and later expanded into packaged groceries. Its founding philosophy was 'Quality perfect, prices lower'. It used distinctive cast-iron signage, offered home delivery, and prioritised centrally located shops for better display and cooling before refrigeration existed. It grew to 128 stores by 1928 and remained a family business throughout Sainsbury’s lifetime. He served as Chairman and Governing Director from incorporation in 1922 until his death in 1928.


Saudi Aramco is the majority state-owned national oil company of Saudi Arabia. It holds the world's largest proven crude oil reserves and largest daily oil production. It operates the world's largest single hydrocarbon network, the Master Gas System. Its shares began trading on the Saudi Exchange on 11 December 2019, reaching a market capitalisation of about US$1.88 trillion. Its origins lie in a 1933 concession granted by Ibn Saud and executed by Chevron Corporation.






Soros Fund Management is a case study in regulatory adaptation: a firm that built its reputation on transparency of idea (macro thesis) and opacity of structure (family office), where the numbers remain impressive but uncheckable.
Tesco is a British multinational groceries and general merchandise retailer headquartered in Welwyn Garden City, England. It was founded in 1919 by Sir Jack Cohen in Hackney, London, beginning with a market stall selling war-surplus groceries. The Tesco brand emerged in 1924 from supplier initials and Cohen’s surname. The first dedicated shop opened in 1931 in Edgware. It was floated on the London Stock Exchange in 1947. It pioneered self-service (1948) and supermarket formats (1956). Cohen’s core business method was 'pile it high and sell it cheap' and the motivational internal motto 'YCDBSOYA'.


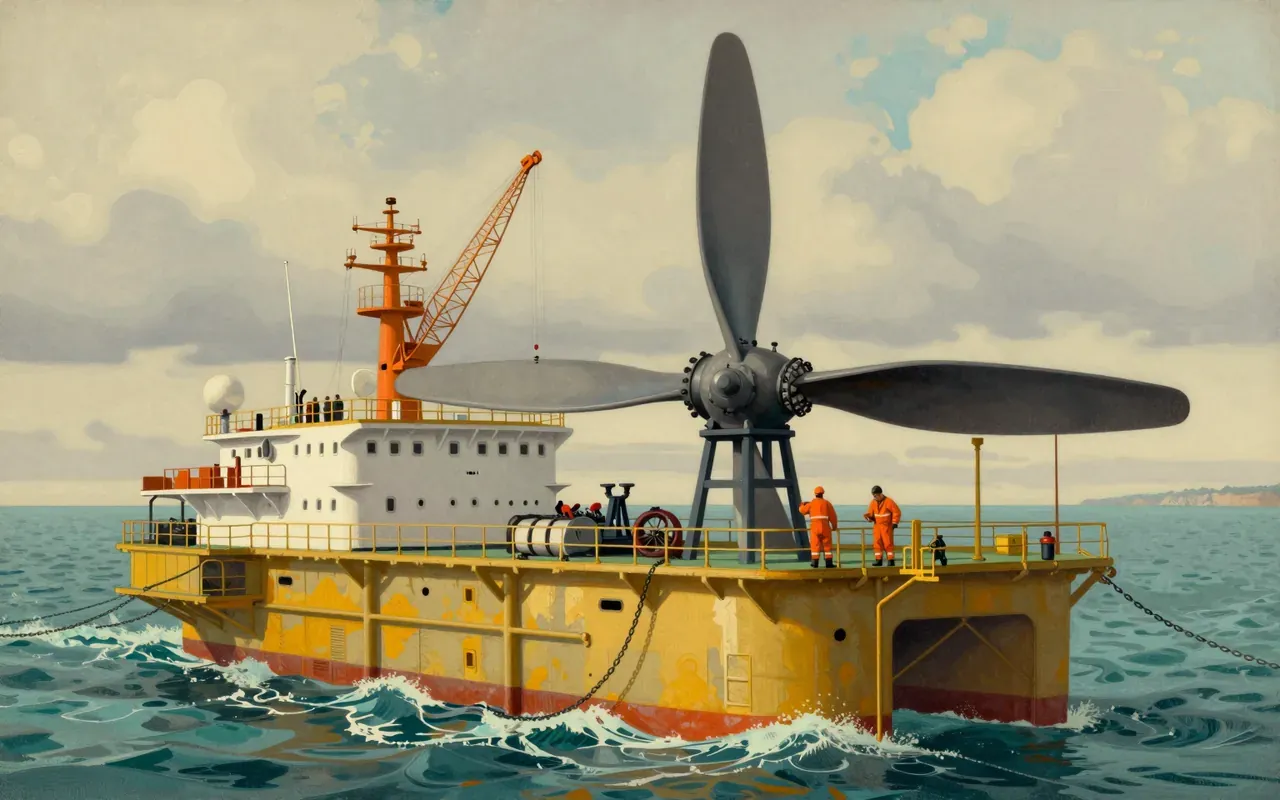
Vestas is a Danish wind turbine company founded in 1945, engaged in manufacturing, selling, installing, and servicing turbines globally; it details major operational milestones including global installations, R&D investment and patenting activity, strategic mergers, facility expansions and closures, and technical innovations such as stealth blades and floating turbines.
Volvo’s origin was not a corporate spin-off or investor-backed startup. It was a personal bet — financed by commissions saved in Paris, structured around a high-risk contract, validated by ten physical prototypes, and launched only after institutional rejection. Its early revenue came from trucks, not cars. Its founding story contradicts the myth of visionary consensus — it was a solo act of leverage, execution, and timing.


Activision’s founding was a contractual rupture, not a technological leap. It turned programmer identity and shelf presence into revenue — and proved third-party publishing could exist only after winning in court.

Adobe’s founding story is not about creative tools—it is about control of a foundational layer: the language that told printers what to print. That decision, made in a garage in 1982, let Adobe license across hardware and software ecosystems before ever selling to end users. Everything else came later—and is absent from the verified record.
Airbnb’s origin is materially humble: a rent crisis, two roommates, an air mattress, and Pop-Tarts. Its business model — brokerage via commission — was clear from the start, but its execution required repeated, costly pivots: cereal sales, crashed websites, YC’s $20k for 6%, and Sequoia’s $585k only after that. Its European expansion relied on acquiring Accoleo — not organic growth or superior product. The story Airbnb tells about itself is one of design-led innovation; the record shows it was one of opportunistic adaptation, funded by hustle and validated by investors only after infrastructure and evidence accumulated.
Alibaba Group is a Chinese multinational technology company founded in 1999 in Hangzhou as a B2B e-commerce marketplace, now operating nine major subsidiaries including Taobao, Tmall, and Alibaba Cloud.
AMD is not a story of disruption — it is a story of licensed dependence, contested access, and court-mandated self-reliance in semiconductor design.

Baidu is a foundational case of algorithm-first platform building: its 1996 RankDex technology became its 2000 product, its 2001 ad model predated Google’s, and its 2003 content-search innovations were tailored to Chinese media structures. It achieved national dominance and NASDAQ listing — but never decoupled from search advertising, even as it invested in Apollo, Xiaodu, and AI stacks.
The Bajaj Group is a 98-year-old Indian industrial conglomerate — not a tech platform, not a VC-backed startup, not a lifestyle brand. Its value comes from physical assets, sectoral spread, and continuity of ownership. It does not claim to disrupt. It owns factories.

Bayer was a dyestuffs partnership founded in 1863 by Friedrich Bayer and Johann Friedrich Weskott. It expanded through synthetic dye innovation, relocated due to arsenic contamination, built brand equity via Aspirin and the Bayer Cross, then merged into IG Farben in 1925 — whose assets were seized post-WWII for Nazi atrocities.


Beyond Meat is a plant-based meat alternative producer founded in 2009 by Ethan Brown to mitigate climate change. It licensed meatless protein technology from University of Missouri professors, launched its first product in 2012, its signature Beyond Burger in 2016, and became the first publicly traded company in its category in 2019. It announced layoffs of 19% of staff in October 2022 due to revenue declines and additional layoffs in November 2023 after a 9% sales decline.
Bharti Airtel is not a tech innovator but a regulatory arbitrageur—its real product is the ability to operate at scale across borders where others stall on licensing, spectrum, or infrastructure cost. It built nothing foundational in telecom standards or silicon, but mastered the sequencing: assemble → manufacture → license → outsource → bundle → expand. That sequence works only once per market—and only if you start before the rules harden.
Blockbuster’s story is not about disruption — it is about refusal. It controlled distribution, not demand. It priced convenience as punishment. Its collapse was mechanical, not mystical.

Boehringer Ingelheim is a rare case of sustained private ownership enabling both technical continuity (from lactic acid to biopharma) and social infrastructure (welfare policies pre-dating national systems). Its business model is not about disruption but compound discipline: owning the science, the scale, and the staff.
BP’s origin story is not about entrepreneurship or engineering — it is about a sovereign concession enabling extraction. Its business model depends on controlling physical assets and political access, not market creation or product innovation.
BYD is a battery-born, vertically integrated Chinese manufacturing conglomerate whose automotive business now dominates its revenue and global EV output — but the sources disclose no financials, no unit economics, and no evidence of why its integration delivers advantage beyond scale and employment headcount.
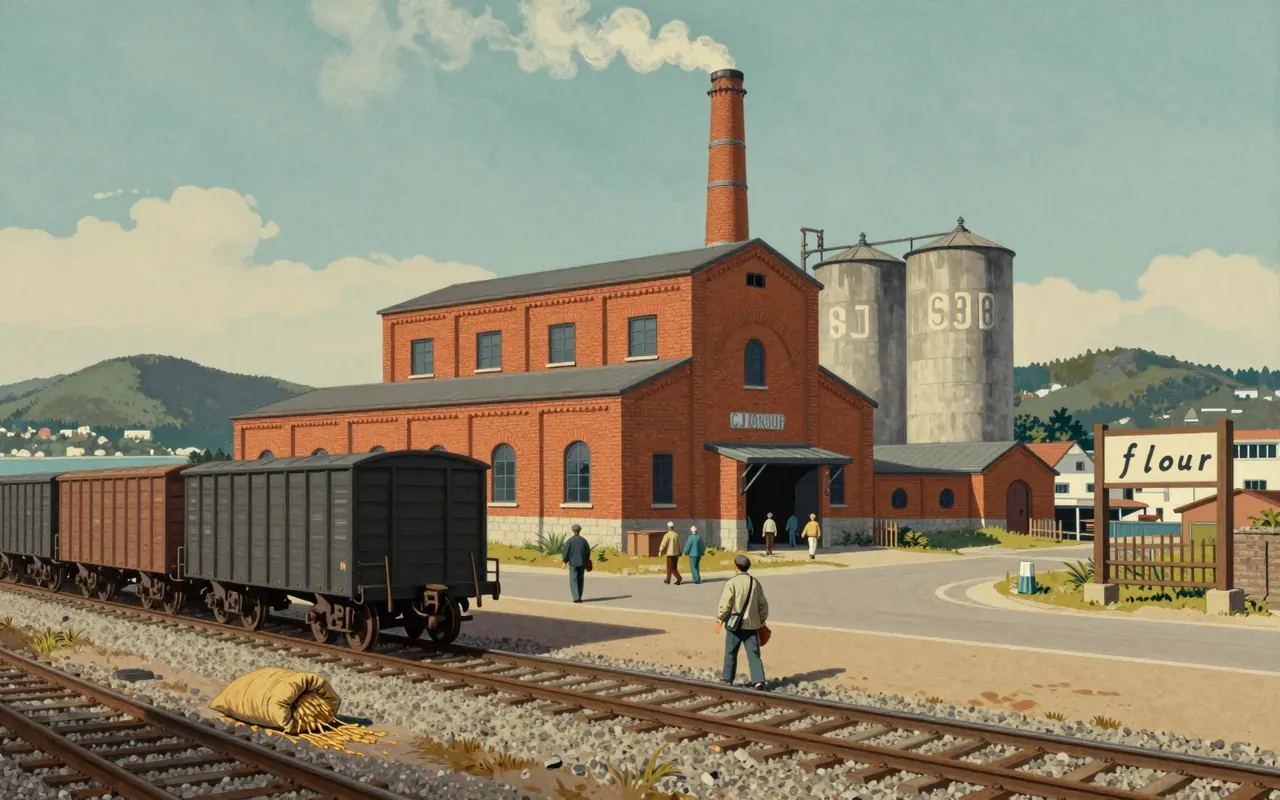
CJ Group is a South Korean chaebol that originated in 1953 as Samsung’s first manufacturing unit: a sugar and flour producer named CheilJedang. It established early industrial firsts — Korea’s first flour mill (1958), first sugar export to Okinawa (1962), and first branded sugar (Beksul, 1965). Its independence from Samsung followed a legal dispute among the Lee family — not market forces. Today it operates across food, bio, logistics, and entertainment, but the sources give no detail on how those businesses interconnect, profit, or compete. It is a case study in legacy infrastructure and familial fracture — not scalable strategy or innovation.
Daewoo was a South Korean chaebol founded in March 1967 by Kim Woo-choong as a small textiles trading corporation. It expanded using government-sponsored cheap loans tied to export potential, acquiring near-bankrupt companies across shipbuilding, electronics, and automotive sectors. By the 1990s, it ranked second largest in assets and third in revenues among South Korean conglomerates. It collapsed in November 1999 with $50 billion in debt after the 1997 Asian financial crisis exposed its reliance on continuous credit. Its story reveals how state-backed finance can substitute for profitability — until it cannot.

The Daimler Company was a British motor vehicle manufacturer founded in London in 1896, with manufacturing based in Coventry; it acquired rights to the Daimler name from Gottlieb Daimler and Daimler-Motoren-Gesellschaft; underwent reorganisation in 1904 and was purchased by BSA in 1910; absorbed the Lanchester Motor Company in 1933; held a Royal Warrant from 1902 until the 1950s; employed distinctive technologies including the Daimler-Knight engine, worm gear final drive, and patented fluid flywheel with Wilson preselector gearbox; and was dissolved on 23 December 2025 after years of dormancy.

Danone’s origin is a tightly documented sequence: a Barcelona workshop, a legal name fix, physician validation, pharmacy distribution, then expansion. No funding rounds, no founder mythmaking — just regulatory adaptation and clinical credibility turned into commerce.


The Walt Disney Company is an American multinational mass media and entertainment conglomerate founded on October 16, 1923, as the Disney Brothers Studio by Walt and Roy Disney in California. It rose to prominence in animation with Steamboat Willie (1928), diversified into live-action films, television, and theme parks in the 1950s, reversed a post-1966 decline under Michael Eisner via international theme park expansion and the Disney Renaissance (1989–1999), and transformed into a major entertainment conglomerate under Bob Iger through strategic acquisitions (Pixar, Marvel, Lucasfilm, 21st Century Fox). It operates the largest television and film studio in Hollywood.
EA is not a tech innovator or creative studio — it is a licensing and distribution engine that built cultural legitimacy on developer authorship, then discarded it for scale.

Epic Games is a vertically integrated software and entertainment company whose business model relies on cross-subsidising its store and engine through a hit game. Its self-portrait as a developer ally conflicts with its contractual terms and revenue structure. The gap between that story and its mechanics is where the real lesson lies.
Facebook is an American social networking service founded in 2004 by Mark Zuckerberg and four Harvard College roommates; initially limited to Harvard students, it expanded to other North American universities and then globally to users aged 13+ (14+ in select regions) starting in 2006; as of December 2023 it had ~3.07 billion monthly active users and as of July 2025 ranked third globally by web traffic, with 23% originating from the US; it was the most downloaded mobile app of the 2010s and is accessible across internet-connected devices including PCs, tablets, and smartphones; its headquarters are in Palo Alto, California.
Gap Inc. was a logistics play disguised as youth culture — and its early success came from solving stockouts, not selling identity.
Geely is a founder-led, family-financed industrial pivot machine — not a tech innovator or brand builder. It built scale by acquiring assets (Volvo, Lotus, Smart, Aston Martin), not customers. Its business model relies on platform reuse and regulatory arbitrage, not margin expansion or consumer loyalty. Verified financials are absent. Its most durable tactic is holding equity stakes where others seek control.
H&M is a Swedish multinational clothing company headquartered in Stockholm, founded in 1947 by Erling Persson in Västerås as a women’s-only retailer named Hennes. Built on a fast fashion business model, it sells apparel, accessories, and homeware. In 1968, Persson acquired the hunting apparel retailer Mauritz Widforss, added menswear, and changed the name to Hennes & Mauritz. The company was listed on the Stockholm Stock Exchange in 1974 and opened its first store outside Scandinavia in London in 1976. It began online retailing in 1998 using the domain hm.com, registered in 1997.
Hermès is a vertically integrated French manufacturing company built on a hand-sewn stitch, sustained by family control, and monetised through scarcity-enforced pricing across 16 product lines.

Hero MotoCorp is a case study in state-enabled industrial scaling: it leveraged licences, joint ventures, and low-cost execution—not proprietary tech or global branding—to become India’s dominant two-wheeler maker. Its independence from Honda was real, but its post-2011 growth relies on the same mechanics: volume, distribution, and incremental product iteration.

Hitachi’s origin was not entrepreneurial mythmaking — it was applied engineering inside a single mine. Its revenue came from selling hardware that replaced steam, muscle, and manual control with electrified motion. It succeeded by staying embedded in physical infrastructure — not by pivoting to services or software. Its independence in 1920 marked a shift in legal structure, not strategy. Odaira’s leadership lasted until 1947, but he never owned the firm he built.
Huawei is a Chinese multinational technology conglomerate founded in Shenzhen in 1987 by Ren Zhengfei. Its headquarters are in Longgang, Shenzhen, Guangdong. Its main product lines include telecommunications equipment, consumer electronics, electric vehicle autonomous driving systems, and rooftop solar power products. Telecommunications equipment is its biggest area of business, and its largest customer is the Chinese government. Initially focused on manufacturing phone switches, Huawei expanded to more than 170 countries, building telecom infrastructure, providing equipment and services, and manufacturing consumer communications devices. In 2012, it surpassed Ericsson to become the world's largest telecommunications equipment manufacturer. As of 2025, it is the largest smartphone vendor in China with an 18.1% market share.
IBM under Thomas J. Watson Sr. was a sales-and-leasing enterprise built on punched card tabulators — not computing. Its dominance relied on vertical control, not technical novelty. That control was dismantled by antitrust action in 1936. Everything else — System/360, AI, PCs — belongs to a later era.

ICICI Bank’s 1994 formation under K.V. Kamath was not the birth of a startup but the strategic repackaging of a state-backed institution into a private, technology-enabled, acquisitive financial group — with real execution in regulation-constrained conditions.
Infosys is a textbook example of policy-led scaling: no proprietary tech, no venture funding, no market creation — just disciplined execution on a regulatory opportunity.
Instagram is a photo- and short-video-sharing social networking service launched in October 2010 by Kevin Systrom and Mike Krieger in San Francisco, after pivoting from a check-in app called Burbn.


JD.com is not a platform play. It is a logistics-and-service company disguised as an e-commerce site. Its scale comes from owning the last mile — and the first response.


Kobe Steel is a Japanese industrial conglomerate whose name misleads: steel accounts for the smallest share of its business among major Japanese steelmakers. It grew not through market innovation but via naval technical guidance and orders after the Russo-Japanese War. Its real strengths lie in wire rods, transport aluminium, screw compressors, and wholesale power supply—three distinct divisions operating semi-independently. The gap between its identity (a steel company) and its economics (a diversified industrial group) is structural, not accidental.
Kodak was not a camera company first — it was a film company that used cameras to distribute its consumable. Its 1888 system created a new market by removing technical barriers. Its dominance came from controlling the film supply chain, not the hardware. No source mentions digital disruption, so the brief stops at peak film-era success.

Lehman Brothers’ origin was material: cotton. Its end was financial: illiquid mortgage assets. The gap between the two is where the real story lives.
LG Electronics is a vertically integrated South Korean hardware manufacturer whose post-war origins, protected domestic launch, and 1995 rebranding reveal more about industrial policy than innovation mythology.
L'Oréal is the world's largest cosmetics company — not because it invented beauty, but because it industrialised chemistry, controlled distribution, and systematised intellectual property.
Louis Vuitton is a French luxury fashion house founded in 1854. It merged into LVMH in 1987. It earns revenue from globally distributed, monogrammed luxury goods sold via 460+ owned stores. Its valuation rose from US$25.9bn (2012) to US$28.4bn (2013), alongside US$9.4bn revenue that year. It is repeatedly named the world’s most valuable luxury brand—but never discloses margins, unit costs, or subsidiary-level financials. Legal actions, WWII collaboration, model mistreatment, UNESCO site damage, and cultural appropriation claims are documented—but none appear in its financial reporting or governance disclosures.
LVMH is a French multinational luxury goods conglomerate formed in 1987 by merger—not founded—of Louis Vuitton and Moët Hennessy. Bernard Arnault assumed control shortly thereafter, not by founding but by outmanoeuvring the initial family owners. The company operates through ~60 subsidiaries managing 75 luxury brands across six branches. Its $500B valuation in April 2023 reflects disciplined acquisition—Boussac Saint-Frères (1984), Tiffany & Co. (2021)—and structural decentralisation that preserves brand identity while centralising financial control. LVMH does not invent luxury; it acquires, integrates, and governs it.
Marks & Spencer began as a £5 stall with a slogan — not a brand, not a department store, but a refusal to haggle.

Michelin is a tyre company whose early dominance came from patenting and proving mechanical improvements — detachable, automobile, run-flat, radial, asymmetric — all tested in races or real-world conditions. It monetised mobility itself: first via tyres, then via the Michelin Guide, which existed solely to grow the car-tourism market and thus tyre sales. No evidence supports claims about culture, legacy, or unmeasured influence — only documented innovations, patents, and commercial pivots.

Nestlé is a case study in how industrial food companies scale not through singular genius, but through technical borrowing, wartime procurement, and post-war recalibration. Henri Nestlé invented a product, then exited. The company that bears his name grew via merger, contract, and consolidation — not continuity.
Netflix is a case study in operational iteration — not technological invention. Its value lies in how it structured incentives, removed friction, and scaled infrastructure — not in what it claimed to be.

Oracle Corporation is a multinational technology company founded in 1977 in Santa Clara, California, by Larry Ellison, Bob Miner, and Ed Oates. It sells database software (especially Oracle Database), enterprise applications (ERP, HCM, CX, SCM), and cloud infrastructure and hardware. By the mid-2000s, it had become the world's largest enterprise software vendor. Its foundational database design drew from Edgar F. Codd’s relational model paper. IBM’s delay in releasing a relational database for Unix and Windows allowed Oracle to dominate mid-range and microcomputer systems. Oracle acquired Sun Microsystems in 2010 after regulatory approval in the U.S. and EU.

Panasonic is a Japanese multinational electronics manufacturer founded in 1918 by Kōnosuke Matsushita, headquartered in Kadoma, Osaka. It makes money by manufacturing and selling electronics, batteries, automotive systems, industrial equipment, and home renovation services. Its early innovation in battery-powered bicycle lamps — replacing three-hour candle and oil lamps — established product-market fit. Its 1963 plant produced eight CRT TVs per minute, accounting for 21.8% of Japan’s output — the largest share of any company. It ranked 6th globally in PCT patents in 2025 — down from three decades as the world’s top patent applicant. Its repeated workforce reductions — 40,000 in 2011, 10,000 in 2025 — signal structural strain, not agility. These are reactive cost cuts, not evidence of resilient business design. Patent leadership does not guarantee market dominance; Panasonic held the world’s top patent applicant rank for three decades but lost consumer electronics leadership as CRT TV production collapsed. Yes — its patent intensity, scale of operational recalibration, and sustained market position offer concrete lessons in industrial adaptation.
POSCO is a state-created steelmaker that achieved scale and productivity through sovereign backing — not market signals or founder vision.


Rolex is a vertically integrated Swiss luxury watchmaker founded in London in 1905, whose early authority came from technical validation (Kew Observatory, 1914), wartime policy (RAF replacement), and structural control (foundation ownership since 1960). It claimed the first waterproof wristwatch case in 1926 — but Depollier patented a functionally identical design eight years earlier. No financial data appears in the sources.


Salesforce is a case study in narrative-first SaaS scaling: built on a slogan, funded by subscription growth, extended by platform logic, and recalibrated by AI-driven cost shifts—not disruption, but disciplined iteration.
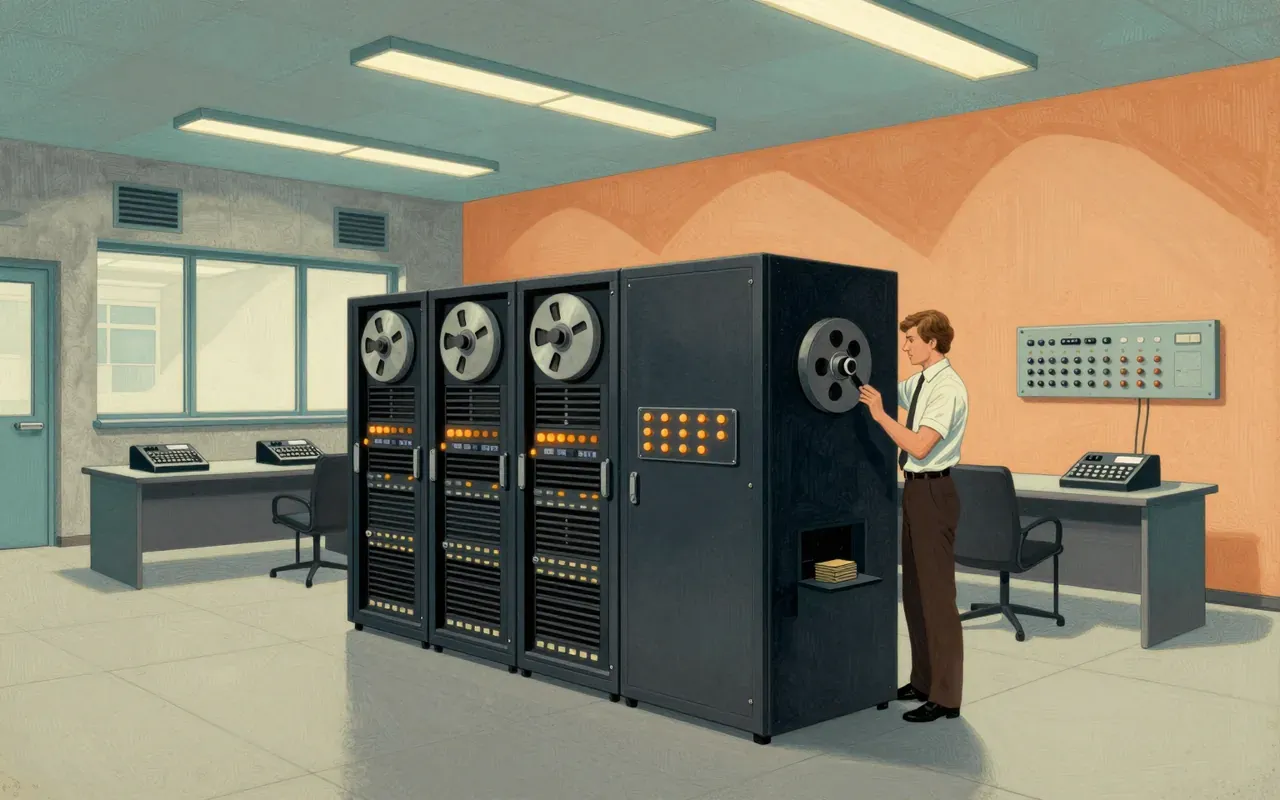
SAP is the world's largest vendor of enterprise software. Founded in 1972 in Walldorf by Dietmar Hopp and four former IBM colleagues, it built its first product—the RF financial accounting system—in 1973 for Imperial Chemical Industries in Östringen. Its technical distinction was real-time operation via local electronic storage and a common logical database, eliminating overnight punch card processing. It restructured from GbR to GmbH (1981), to AG (late 1980s), to SE (2014). Hopp led SAP from 1988 to 2005 and retained ~10% equity.
Sega’s story is not about innovation or disruption — it is about sequential exit: from import to manufacture, from coin-op to console, from hardware to software. Its survival post-2001 rests on what it built before it tried to compete with Nintendo and Sony — arcade scale and Sonic.
Shein is a global fast fashion e-commerce platform founded in 2008 in Nanjing, China, and currently headquartered in Singapore. It began as a drop shipping-style operation sourcing from Guangzhou’s wholesale market, then transformed into a fully integrated retailer starting in 2012. Its product range spans women’s, men’s, and children’s apparel plus accessories and cosmetics, targeting Europe, the Americas, Australia, and the Middle East. Its growth has been tied to popularity among younger Millennials and older Gen Z consumers, enabled by low pricing and rapid trend response.

Shell plc is a British multinational oil and gas company formed in April 1907 through the merger of Royal Dutch Petroleum Company and The 'Shell' Transport and Trading Company — founded in 1897 by Marcus Samuel and his brother. It is vertically integrated across exploration, production, refining, transport, distribution, marketing, petrochemicals, power generation, and trading. It was the ninth-largest corporate greenhouse gas emitter (1988–2015). In 2004, it overstated oil reserves, triggering a £17 million fine and leadership change. In 2021, it rebranded from Royal Dutch Shell plc to Shell plc.

Siemens is a German multinational engineering company founded in 1847 as Telegraphen-Bauanstalt von Siemens & Halske in Berlin. It evolved through mergers into Siemens AG in 1966. It makes money from industrial automation, building automation, rail transport, and health technology. Its early model worked: rapid internationalisation via family agents, vertical integration from invention to installation, and patent-backed standard-setting. It does not sustain leadership in all its historical domains: it no longer builds x-ray tubes, electric trams, or passenger trains as standalone products. The gap between Siemens’s founding logic — applied electromagnetism deployed via owned workshops and international agents — and its present structure — a diversified, publicly listed conglomerate with AI and software at its core — reveals how industrial capability gets recoded as platform strategy over time. Yes — if you are studying how engineering firms scale infrastructure innovation into global revenue without pivoting to venture capital narratives.
SK Group is a South Korean chaebol founded in 1953 through the acquisition of Sunkyong Textiles — Japanese-owned property seized by the South Korean government after the Korean War armistice. It is the second-largest chaebol by revenue, controlled by the estate of Chey Tae-won via SK Inc., and operates 186 subsidiaries under the SKMS management system. Its cornerstone remains energy and chemicals, though it spans AI semiconductors, flash memory, telecommunications, and petrochemicals. The material confirms no revenue figures, margins, valuations, or operational metrics beyond structure, origin, control, and sectoral scope.
SoftBank Group is a Japanese investment holding company founded in 1981 as a software distributor, restructured as a holding company in 1999, and renamed SoftBank Group Corp in 2015. It focuses exclusively on investment management — primarily in technology companies across diverse markets. Its Vision Fund, launched in 2017 with $100 billion, was the world’s largest technology-focused venture capital fund at inception. SoftBank went public in 1994 with a $3 billion valuation. In 2016, it announced a $50 billion U.S. investment commitment targeting 50,000 jobs. From 2023, it shifted strategy toward AI infrastructure and semiconductor-related investments — a direction confirmed by Masayoshi Son’s January 2025 chairmanship of Stargate LLC.
Spotify is a Swedish music streaming service founded in April 2006 by Daniel Ek and Martin Lorentzon. It operates under a freemium model, offering DRM-protected audio content—including over 100 million songs and 7 million podcasts—from record labels and media companies. Royalties are distributed based on stream share rather than fixed per-unit payments, with ~70% of revenue going to rights holders. It became publicly traded on the NYSE in April 2018 and reported its first profitable year in fiscal 2024. As of March 2026, it served over 777 million monthly active users and 300 million paying subscribers.


Theranos was a health technology company founded in 2003 in Palo Alto, California, that falsely claimed to perform rapid, accurate blood tests using minimal blood volume via proprietary devices; investigations revealed it relied on conventional machines, produced inaccurate results, voided two years of Edison data, and misrepresented its capabilities to investors, partners, and regulators.


Twitter, Inc. was a social media company founded in March 2006 in San Francisco, spun off from Obvious Corporation (formerly Odeo), operating the Twitter platform and other services. It prioritised uptime and design principles over revenue until after 2008, grew to over 100 million users by 2012 and 330 million monthly active users by 2019, went public in November 2013, and was acquired by Elon Musk for $44 billion in April 2022 before merging into X Corp. in April 2023. No source states its revenue model, unit economics, or profitability.

Uber is a platform whose early growth relied on regulatory noncompliance, strategic rebranding, and reactive imitation — not technical invention or user-first design. Its financial mechanics are transparent: high take rates on massive transaction volume. Its story is not about disruption, but about exploiting gaps between law and enforcement.

Unilever is not a modern purpose-led corporation disguised as a legacy firm — it is a legacy firm whose original mechanics (commodity sourcing, unit standardisation, trademark enclosure, paternalistic control) still define its structure, even as its marketing tells a different story.
Uniqlo is a case study in industrialised apparel: no hype, no heritage theatre, no seasonal spectacle — just a tightly coupled system for making, moving, and refining simple clothes at scale.
Universal Pictures was a business architecture designed to extract value from every layer of film — from performer contracts to theatre leases — using legal, spatial, and branding levers. Its success was tactical, not mythic.
Valve is a rare case where platform ownership fully decouples creative output from financial sustainability. Its flat structure is not a virtue—it is a tax the company pays for avoiding managerial overhead, made bearable only by Steam’s dominance. It does not scale. It does not replicate. It survives.
Warner Bros. is a trademarked asset that has outlived every corporate owner since its 1923 founding — surviving mergers, spin-offs, and acquisitions not through creative consistency, but because its library and IP rights remain licensable across shifting distribution models.
WeChat is a product of Tencent’s Guangzhou lab, launched in 2011 by Allen Zhang. It bundles messaging, social, and payments — and dominates China not because it is open or interoperable, but because it is closed, complete, and compliant.
WeWork was a shared-workspace provider founded in 2010 by Adam Neumann and Miguel McKelvey, operating physical and virtual coworking spaces in ~600 buildings across 125 cities. It made money by leasing commercial real estate long-term, then subleasing it short-term to members — a classic mismatch of lease duration and revenue risk. The brand resonated and the format met demand for flexible office space — but only at small scale, with tight lease control and disciplined expansion. The business model failed under scale: fixed long-term lease liabilities could not be offset by volatile, short-term membership revenue — especially when growth relied on subsidising occupancy with investor capital. Neumann’s practice of buying buildings and leasing them back to WeWork exposed a governance vacuum — incompatible with public markets. Bankruptcy in 2023 and restructuring in 2024 confirmed the model collapsed under its own lease obligations — not market timing. A company can raise $12.8 billion and peak at a $47 billion valuation without ever proving unit economics — because investors funded narrative, not margins. Yes — as a case study in how governance failures, misaligned incentives, and financial engineering can override operational reality.
WhatsApp is not a messaging app with a business model—it is a telecom identity layer wrapped in an app. Its value lies in what it replaced (SMS, MMS, local calling) and what it enabled (cross-border, zero-cost, asynchronous communication at planetary scale). Its acquisition by Facebook in 2014 for $19.3 billion confirmed its strategic value as infrastructure—not as a consumer product.


Xerox pioneered the photocopier market starting with the Xerox 914 in 1959; Joseph C. Wilson signed an agreement in 1946 to develop Chester Carlson's invention commercially; before the 914, Xerox tested the market with the Flat-plate 1385 prototype, which proved nonviable due to slow speed; the 914—the first plain paper photocopier—was developed by Carlson and John H. Dessauer; researchers at Xerox and PARC invented key personal computing elements including the GUI, mouse, and desktop computing; Xerox opened PARC in 1970; and Gary Starkweather invented the laser printer in 1969 by modifying a Xerox 7000 copier.
Xiaomi is a Beijing-based Chinese multinational founded in 2010 by Lei Jun and six others. It operates in consumer electronics, software, and electric vehicles. It launched its first smartphone in August 2011 and entered the smart electric vehicle industry in March 2021.
YouTube was a technical execution of a simple idea—upload and share video—with no monetisation strategy. Its founders leveraged prior wealth, network access, and timing to achieve rapid scale, then sold to Google before proving sustainability. The gap between usage and revenue was never closed—it was exited.
Zara is a case study in operational rigour, not branding or tech. Its advantage is physical: proximity, control, and repetition — not algorithms or virality.

Adidas is a German multinational athletic apparel and footwear corporation headquartered in Herzogenaurach. It was founded by Adolf Dassler in 1948, following the breakup of the Dassler Brothers Shoe Factory. Adidas makes money selling athletic apparel and footwear. Its revenue in 2024 was €23 billion. It operated 17 factories and generated one billion Deutschmarks in annual sales by 1978. Dassler’s focus on functional footwear innovation worked: he redesigned spiked running shoes, introduced interchangeable screw-in studs for football boots, and secured high-visibility athlete adoption (Jesse Owens, 1936). The three-stripe logo became a registered trademark in 1949 and a scalable visual identifier. The 1924 Dassler Brothers Shoe Factory was a shared venture — not Adidas — and dissolved in 1948 amid a rift. Post-war material shortages forced rapid reconversion from weapons to shoes — yet Adidas hit one billion Deutschmarks in sales by 1978. Adidas shows how a narrow technical advantage — screw-in studs, canvas-rubber spikes, the three-stripe trademark — can anchor decades of manufacturing expansion when paired with strict control over production, branding, and distribution channels. Yes — as a case study in how technical footwear innovation, trademark discipline, and athlete-led validation built industrial scale in post-war Europe — but only if you treat its origin story as a business reconstitution, not a founding myth.

Berkshire Hathaway is a holding company built on arbitrage, insurance float, and concentrated control — not innovation or disruption.

ByteDance is an AI-driven content platform company built on internal competition, strategic acquisition, and rapid global scaling — not organic product leadership or transparent monetisation.

Goldman Sachs is a multinational investment bank and financial services company founded in 1869 and headquartered in New York City. It offers investment banking (advisory for mergers and acquisitions and restructuring), securities underwriting, prime brokerage, asset management, and wealth management. It acts as a market maker, operates private-equity and hedge funds, structures complex and tailor-made financial products, owns Goldman Sachs Bank USA (a direct bank), and trades both on behalf of clients and for its own account.

Intel is a foundational semiconductor company whose business model pivoted from memory to microprocessors—and whose lasting leverage came from controlling the x86 instruction set, not just fabrication.

JPMorgan Chase is a vertically integrated financial monopoly whose scale rests on documented historical control — from industrial consolidation to slave-backed credit — not disruption or invention.


Morgan Stanley is a financial institution whose origin story is legally precise, but whose current identity is structurally ambiguous. It began as a Glass–Steagall-mandated spin-off — not a startup, not a rebellion, but a regulatory necessity. Its early market share proves execution mattered more than ideology. Its 1997 merger erased the line between investment banking and mass-market finance — yet the firm still trades on the prestige of 1935. That dissonance is the real story.

PayPal is a case study in opportunistic infrastructure: built on a dead-end tech idea, it succeeded only after latching onto a specific, messy, high-volume use case — eBay auctions — and charging for reliability in a trust vacuum.

Tencent is a Chinese multinational technology conglomerate and holding company, co-founded in 1998 in Shenzhen. It is one of the highest-grossing multimedia companies globally by revenue and the world’s largest company in the video game industry by equity investments. Its first product, OICQ, launched in February 1999 and reached over one million registered users by year-end 1999. In 2000, Tencent secured $2.2 million in venture capital funding and adapted its platform for mobile messaging — generating 80% of revenue via telecom operator fee-sharing deals. After losing a U.S. arbitration case over domain names, it renamed OICQ to QQ in December 2000. By 2004, it held 74% of China’s instant messaging market and listed on the Hong Kong Stock Exchange.

TSMC is the world’s largest and most advanced contract chipmaker — a state-enabled, capital-intensive factory system that executes Moore’s Law with industrial rigour. Its dominance comes not from vision or branding, but from delivering real chips, on schedule, at scale.

Visa is a payment infrastructure built on delegation: banks issue cards, Visa provides the rails and branding, and consumers pay fees embedded in every transaction. Its 1970 restructuring into a member-owned, decentralised association — conceived and led by Dee Hock — was a deliberate rejection of hierarchy. Yet its 2025 volume ($14.2 trillion) reflects not distributed decision-making but tightly coordinated standards enforcement. The ‘chaordic’ ideal remains descriptive, not operational.

Amazon is a vertically integrated infrastructure company disguised as a retailer. Its founding was opportunistic, its growth funded by reinvestment, not profit. Its dominance rests on owning the pipes — logistics, compute, storage, and distribution — not the content or brands moving through them.

Anthropic positions itself as a safety-first AI builder—but its business runs on proprietary models trained with legally contested data, sold under restrictive partnerships, and governed by self-declared public benefit terms that do not prevent mass-scale book scanning or billion-dollar copyright liability.

Apple Inc. was founded in 1976 to market Wozniak’s Apple I. It achieved early success with the mass-produced Apple II. It pioneered graphical user interfaces via the Lisa (1983) and Macintosh (1984), launching desktop publishing in 1985 with the LaserWriter. Internal conflict led to Jobs’s 1985 departure. By 1997, Apple was losing money and failing to deliver a modern OS — prompting acquisition of NeXT and Jobs’s return as CEO. NeXTSTEP became the foundation of Mac OS X. Apple’s revival was structural, not inspirational.

BlackBerry Limited is a Canadian software company specialising in secure communications and IoT. It was founded in 1984 as Research In Motion (RIM) and developed the BlackBerry brand of wireless mobile devices from 1999 to 2016. After spinning off its mobile division into BlackBerry Mobile in 2016 — discontinued in 2020 — the company transitioned to providing software and services and holds critical software application patents. RIM was the first wireless data technology developer in North America and the first outside the Nordic countries to develop Mobitex connectivity products. In 1996, RIM introduced the Interactive Pager, the first two-way messaging pager. In 1999, RIM introduced the BlackBerry 850 pager, the first device to use the BlackBerry OS, which received push email from Microsoft Exchange Server using BlackBerry Enterprise Server (BES). Its introduction set the stage for enterprise-oriented products, such as the BlackBerry 957 in April 2000, the first BlackBerry smartphone.

The Coca-Cola Company was founded in 1892 by Asa Griggs Candler in Atlanta after he purchased the formula from John Stith Pemberton in 1888. It generated revenue by manufacturing and selling syrup to soda fountains, then licensing bottling rights for $1 per territory — a contract that transferred capital and operational risk to third parties while preserving brand control. By 1895 it achieved nationwide US distribution; exports began in 1899 (Cuba) and 1901 (Europe). Candler trademarked the brand and paid dividends in 1893, proving early financial viability. The model worked because it scaled without infrastructure — but failed to ensure product consistency across bottlers. This is a masterclass in leveraging intellectual property through contractual design, not product innovation.

Costco is a membership-first retail system whose financial mechanics are transparent: fees fund operations, low margins enforce discipline, and private label locks in loyalty. It works where density, income, and culture permit bulk buying — and fails where they don’t. No hype. No exceptions.

Ford Motor Company was not an idea about mobility—it was a financial and mechanical system for turning $28,000 into 15 million cars. Its power came from eliminating variability: in parts, in process, in price, and eventually in design. It succeeded by making everything repeatable—including authority.

General Electric was a financial construct, not an inventive one. Its formation marked the moment capital overrode authorship — and Edison became a brand, not a boss.

General Motors was founded in 1908 as a holding company, not a manufacturer. It made money by acquiring brands and suppliers, issuing stock to secure alignment, and franchising dealerships — all before building a single integrated factory. Its early success came from financial engineering, not product innovation. Durant was removed twice — in 1910 and 1920 — exposing the fragility of growth without operational discipline. Sloan’s later reforms codified what Durant had improvised: a scalable, tiered brand architecture. The real innovation was not the car, but the corporation.


IKEA is a case study in disciplined execution — not innovation. Its success rests on replicating a single operating model globally, enforced by geographic and legal separation between brand and retail. Nothing in the source material supports claims about culture, sustainability, or digital transformation — only cost, control, and structure.


Lotte is a textbook case of chaebol formation through sequential anchoring — first in Japan, then decisively in Korea — but its financial mechanics remain unreported.

McDonald's is not a restaurant chain but a replication system — built on enforceable standardisation and deliberately constrained franchising. Its economics rely on control, not volume, and its origin story is a legal rebranding of a hostile acquisition.

Meta Platforms is a vertically integrated advertising monopoly masquerading as a metaverse infrastructure company. Its business model is simple and brittle: monetise attention at scale. Its strategy is contradictory: spend billions on speculative futures while refusing to decouple from surveillance-based ads. Its governance is absolute: Zuckerberg controls votes, vision, and compensation.

Microsoft’s founding was not about building the best software first — it was about controlling the terms of distribution before the market existed. Its early success came from timing, contractual foresight, and treating software as licensable intellectual property — not a service or craft. The company established the template for platform leverage in computing: own the interface, not the hardware.

Myspace was the first globally reaching social network. It grew fast, peaked at 115 million monthly visitors, and was acquired for $580 million. But it never built infrastructure, governance, or trust to match its scale — and collapsed when attention shifted to platforms that treated users as people, not pageviews.

Nike’s origin is a textbook case of a startup succeeding not by inventing a category, but by reengineering a supply chain — then iterating relentlessly on one functional detail: traction.
Nintendo’s origin is a case study in operational discipline over narrative ambition. It succeeded by controlling production hardware, exploiting regulatory shifts, and locking in high-frequency buyers — not by inventing games or chasing culture.

Nokia's origin is industrial infrastructure, not digital ambition. Its longevity stems from disciplined capital management — not visionary foresight.

Nvidia is a fabless semiconductor company whose business model depends on external demand shocks, not internal cost control or manufacturing leverage.

OpenAI is a public benefit corporation whose legal structure separates nominal mission stewardship (26% nonprofit ownership) from actual control and value capture. Its market impact is real—ChatGPT became the fifth-most-visited site globally—but its $852bn valuation reflects investor appetite for AI infrastructure access, not verified unit economics, revenue, or margin discipline. Microsoft’s $13bn investment funds development but does not constitute revenue. The gap between OpenAI’s self-description as a public benefit entity and its operational reality is structural—not incidental.

Patreon is not a creator empowerment tool — it is a monetisation layer that captures value at the point of transaction, enforces terms unilaterally, and scales through volume, not trust.

PepsiCo is a post-1965 corporate construct. Its name recalls, but does not continue, Caleb Bradham’s 1893 pharmacy invention — a digestive soda that failed because of commodity price risk, not brand weakness.


Porsche began as a contract engineering firm — not a carmaker. Its first product was the Volkswagen Beetle, designed for the German government in 1931. It earned royalties on every Beetle built. Only in 1948 did it sell its first car under its own name: the 356, built by hand in a Gmünd sawmill using Beetle-sourced components due to post-war scarcity. Over 78,000 356s were made across 17 years — but the company’s revenue came first from consulting, then royalties, not car sales.

Reddit is a community platform whose founding mechanics—Lisp prototype, Swartz-led rewrite, rapid acquisition, deferred monetisation, and founder re-entry—reveal how infrastructure survives without a clear business model.


Samsung’s origin contradicts its current identity: it was a trading and transport firm, not a tech innovator. Its electronics entry was late, small-scale, and licence-dependent — a strategic pivot enabled by infrastructure, not invention.

Shopify is a Canadian multinational cloud e-commerce management platform for retail point-of-sale systems, founded in 2006 by Tobias Lütke, Daniel Weinand, and Scott Lake. In 2024, it processed US$292.3 billion in transactions, with 5 million customers. Its software is praised for ease of use and reasonable fee structure, and it is described as the 'go-to e-commerce platform for startups'. Shopify went public in 2015 and uses a two-class voting structure that grants disproportionate voting control to Lütke despite his minority economic stake.

Sony’s early business model was hardware-first, export-first, and name-first — built on tangible, shipable, patentable devices that redefined category boundaries in foreign markets.

SpaceX is a government-contract-powered aerospace manufacturer whose reusable launch system succeeded where others failed — not because of vision alone, but because NASA paid for development, testing, and flight operations while Starlink created a parallel revenue stream. Its Mars and Starship ambitions remain outside this economic reality.
Starbucks is the world’s largest coffeehouse chain. It was founded in 1971 in Seattle as a coffee bean wholesaler. Howard Schultz transformed it into a company-owned coffeehouse chain serving espresso-based drinks. As of November 2022, it operated 35,711 stores in 80 countries. It held an IPO on June 26, 1992, raising $271 million to double its store count. It credits its growth to rejecting domestic franchising and positioning stores as social hubs — driving the second wave of coffee culture.

Stripe is infrastructure, not finance. It sells developer convenience — not banking services. Its $159bn valuation rests entirely on volume processed, not revenue disclosed, margins proven, or ownership of capital.

Tesla is not a software or AI company—it is a vertically integrated hardware manufacturer whose valuation rests on future scale, not current unit economics. Its founders were Eberhard and Tarpenning. Musk joined in 2004, led funding, took control, and shaped its public narrative. It sells cars, batteries, and solar—but publishes no per-product margin data. Its market dominance is financial, not operational.

TikTok is a Chinese-origin short-form video platform launched internationally by ByteDance in September 2017 as the overseas counterpart to Douyin. It uses AI-driven recommendation algorithms to connect creators with audiences. It surpassed two billion mobile downloads by April 2020. Its corporate entity, TikTok Ltd, is incorporated in the Cayman Islands and headquartered in Singapore and Los Angeles. Zhang Yiming founded ByteDance in 2012 and explicitly framed global expansion as essential because China accounts for only one-fifth of global internet users. ByteDance acquired Musical.ly for US$800 million in August 2018 and integrated it into TikTok.

Toyota’s founding was a licensed, capital-backed industrial pivot — not a startup story.

Volkswagen was a Nazi state project designed by Ferdinand Porsche, funded by coerced public savings, and diverted entirely to military production. Its 'people’s car' promise was broken before delivery — yet its engineering outlived its ideology.

Walmart’s early success was mechanical, not magical. It used known levers — location, transport, procurement — with unusual discipline. Its story is not about disruption but about execution fidelity.


Yahoo Inc. (2017–present) is not the original Yahoo!. It is a Delaware-incorporated media entity formed in 2006, acquired by Verizon in 2017 for $4.48 billion — reduced from $4.8 billion after two breaches affecting over a billion users. Verizon wrote down its combined AOL-Yahoo value by $4.6 billion in 2018 and rebranded it Verizon Media in 2019. In 2021, Apollo Global Management acquired 90% for $5 billion, reinstating the Yahoo name and appointing Jim Lanzone CEO. Its $7.4 billion 2020 revenue comes from advertising across vertically focused, high-traffic properties — but it has shed Tumblr, HuffPost, and AOL without replacing their scale or influence.
Every desk carries the hue of this subject, so a brief says where it belongs before you read the title.