Airbus
The European airliner maker as it stood in 1998: a consortium of national aerospace firms, bound by treaty and paid by airliner sales.
Making it work with the materials and money available.
Ferrari is a racing operation that sells cars — not the reverse. Its business model depends on using road-car revenue to fund Scuderia Ferrari, which in turn validates the brand, justifies price premiums, and dictates engineering direction. It was never financially self-sustaining in racing alone. Enzo Ferrari maintained control of racing through every ownership change — including Fiat’s 1969 investment — because that control was the source of legitimacy, not the cars.
Rolls-Royce Limited was not a luxury brand first — it was an engineering firm that built cars to prove its method, then switched to aero-engines to survive war, then bet its existence on jet engines. Its collapse in 1971 was not a failure of ambition or invention. It was a failure of cost control in a single programme.
Malcolm McLean’s intermodal container was not an invention but a system — built around a 35-foot steel box sized for Pennsylvania highways, secured by Tantlinger’s corner castings and twistlocks, and operated by Sea-Land’s vertically controlled ships and cranes. It cut port handling time to eight hours — but only on one ship, at one port, under one company’s control. The real innovation was enforcing standardisation through ownership, not designing a better box.
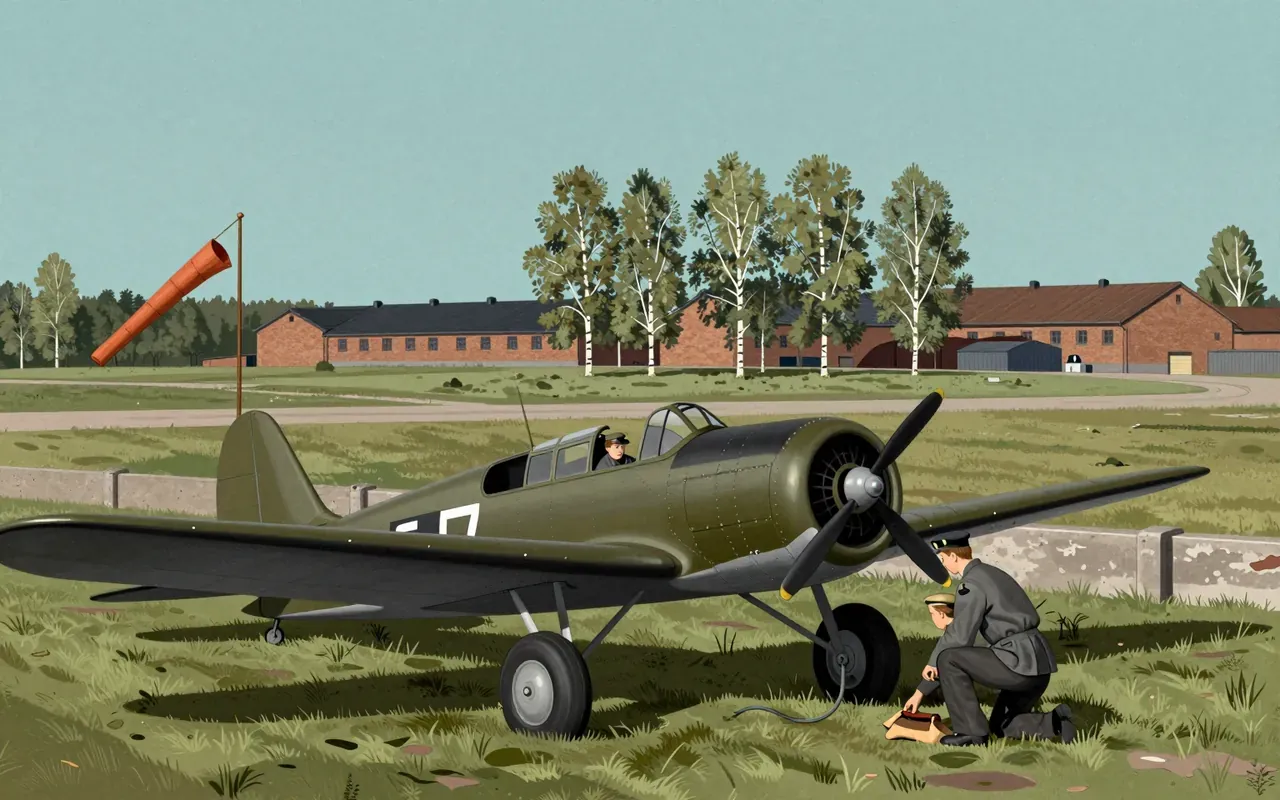
Saab AB is a Swedish aerospace and defence company founded in 1937 by AB Bofors to build aircraft domestically. It merged with ASJA in 1940, developed its first aircraft — the SAAB 17 — which flew on 1940-05-18, began automobile production in 1947, merged with Scania-Vabis in 1968, changed its name to Saab AB in May 1965, and was re-established as an independent entity in 1995 after de-merger.

Godrej & Boyce is not a story of disruption but of continuity — sustained by refusing to outsource precision, testing claims in fire, and anchoring engineering to national need. Its business model has never been about scaling a single product, but about retaining sovereign capability across generations.
ABB is a post-merger industrial incumbent whose value lies in proven, regulated, physical infrastructure — not software, platforms, or scalability stories.
Alfa Romeo was not founded by Nicola Romeo. It was founded in 1910 as A.L.F.A. to acquire the assets of the failing Italian Darracq subsidiary. Romeo acquired it in 1915, took full ownership by 1918, renamed it in 1920, launched the first Alfa Romeo-branded car in 1921, won the inaugural 1925 World Manufacturers’ Championship, faced near-liquidation in 1927 due to poor investments, departed formally in 1928, and was taken over by the Italian state in 1933.

Caterpillar Inc. is the world's largest construction equipment manufacturer, founded in 1925 via merger, but rooted in Benjamin Holt’s continuous-track tractor innovation of 1904–1907.
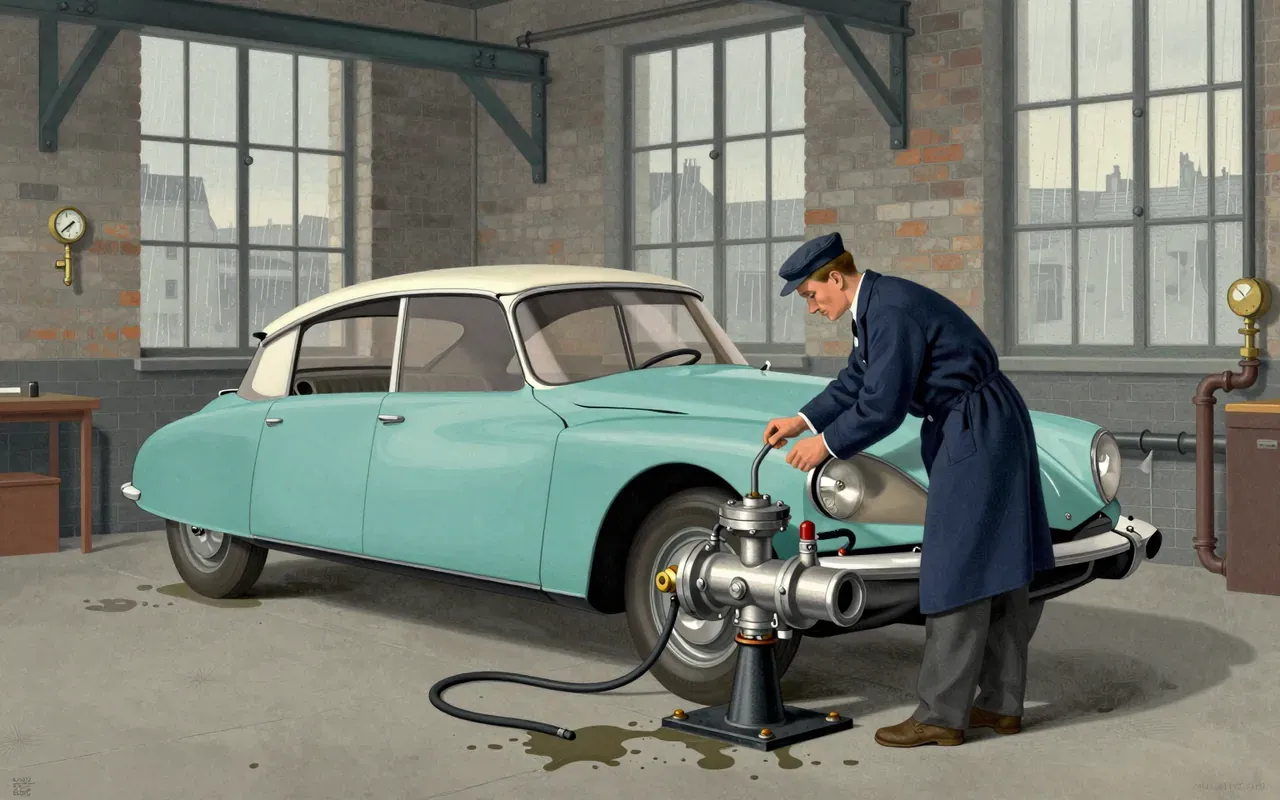
Citroën was a French automobile manufacturer founded in 1919 in Saint-Ouen-sur-Seine. It pioneered four world-first production car technologies: front-wheel drive with unibody construction (1934), hydropneumatic self-levelling suspension (1954), modern disc brakes (1955), and swiveling headlights (1967). It also launched the 2CV in 1948, pioneering soft interconnected suspension. Citroën gained international reputation mass-producing armaments in WWI. It became the fourth-largest carmaker in the world in the 1930s, peaking in 1932 with the Traction Avant. Cost struggles aggravated by the Great Depression led to bankruptcy in 1934 and takeover by Michelin. Its double-chevron logo derived from André Citroën’s application of double helical gears, which he acquired after seeing them used by a Polish carpenter around 1900.

Lamborghini is a case study in disciplined positioning: a luxury carmaker built on agricultural engineering, anchored in one town, defined by one cultural metaphor, and repeatedly tested — and sometimes broken — by global economic forces.
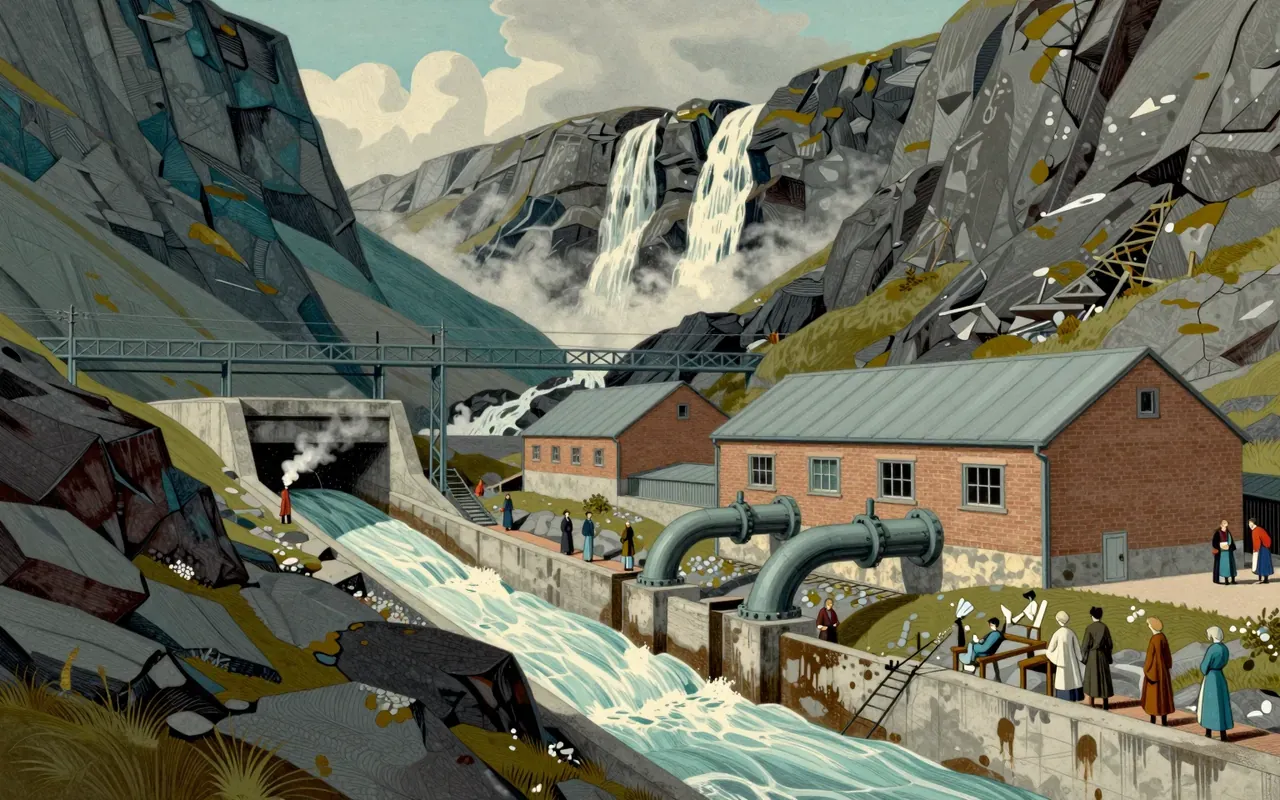
Norsk Hydro began as a single-purpose vehicle for Birkeland’s nitrogen-fixing arc — a physics experiment turned factory. Its early dominance came not from IP or management, but from locking in Norway’s hydropower geography. It survived obsolescence not through reinvention, but by ceding chemical control to IG Farben. Its WWII role — sole European heavy water producer — was accidental infrastructure reuse. Its current aluminium and renewables business shares no technology with its origin, only its dams, debt, and place.
Peterbilt is a case study in acquisition-led industrial continuity: a timber operator bought a defunct truck maker to solve local hauling problems, engineered narrowly effective solutions, scaled only when external demand (military) appeared, and exited when land value exceeded truck value. Its legacy lies in execution, not vision.
Peugeot is the oldest car company in the world — but only because it formalised its automobile division in 1896, 86 years after its founding as a steel foundry. Its success came not from breakthrough invention, but from disciplined technology adoption, rapid iteration, and industrial scaling.

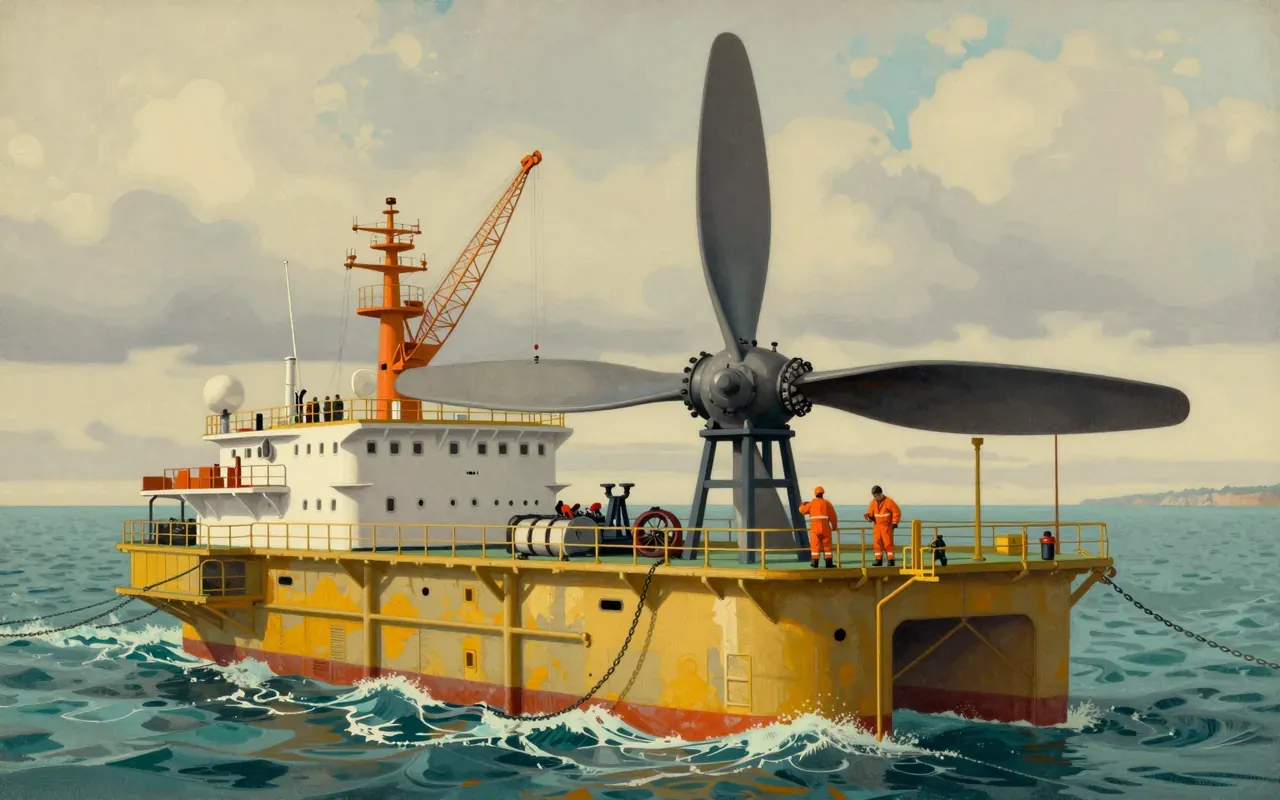
Vestas is a Danish wind turbine company founded in 1945, engaged in manufacturing, selling, installing, and servicing turbines globally; it details major operational milestones including global installations, R&D investment and patenting activity, strategic mergers, facility expansions and closures, and technical innovations such as stealth blades and floating turbines.
Volvo’s origin was not a corporate spin-off or investor-backed startup. It was a personal bet — financed by commissions saved in Paris, structured around a high-risk contract, validated by ten physical prototypes, and launched only after institutional rejection. Its early revenue came from trucks, not cars. Its founding story contradicts the myth of visionary consensus — it was a solo act of leverage, execution, and timing.


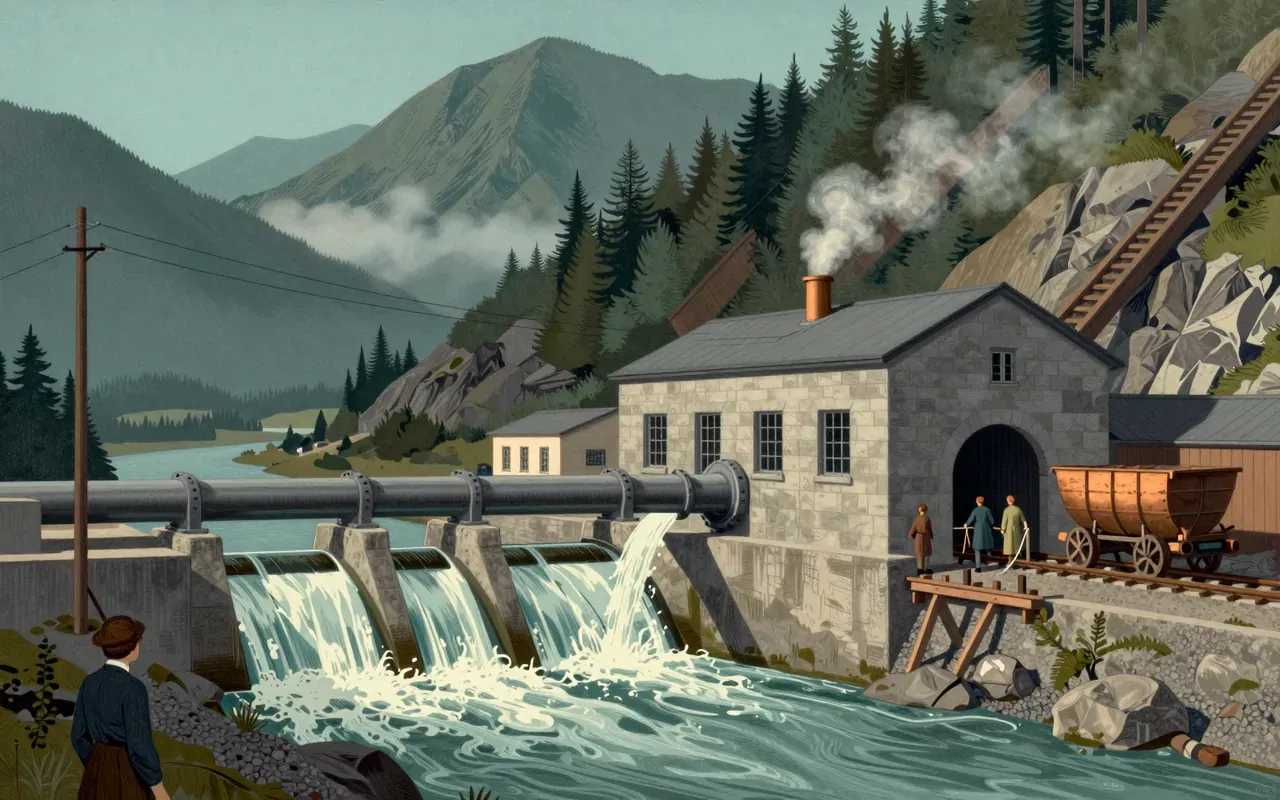
Hitachi’s origin was not entrepreneurial mythmaking — it was applied engineering inside a single mine. Its revenue came from selling hardware that replaced steam, muscle, and manual control with electrified motion. It succeeded by staying embedded in physical infrastructure — not by pivoting to services or software. Its independence in 1920 marked a shift in legal structure, not strategy. Odaira’s leadership lasted until 1947, but he never owned the firm he built.
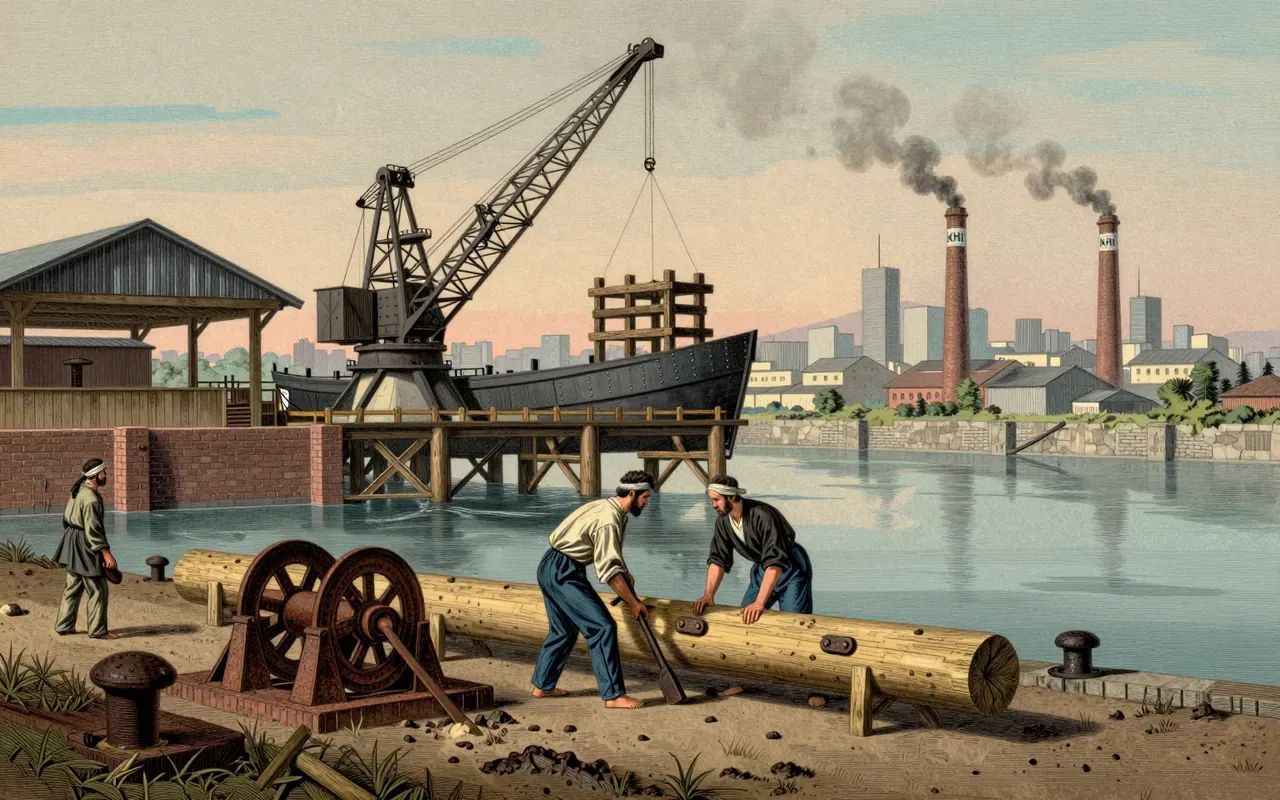

Kobe Steel is a Japanese industrial conglomerate whose name misleads: steel accounts for the smallest share of its business among major Japanese steelmakers. It grew not through market innovation but via naval technical guidance and orders after the Russo-Japanese War. Its real strengths lie in wire rods, transport aluminium, screw compressors, and wholesale power supply—three distinct divisions operating semi-independently. The gap between its identity (a steel company) and its economics (a diversified industrial group) is structural, not accidental.
Michelin is a tyre company whose early dominance came from patenting and proving mechanical improvements — detachable, automobile, run-flat, radial, asymmetric — all tested in races or real-world conditions. It monetised mobility itself: first via tyres, then via the Michelin Guide, which existed solely to grow the car-tourism market and thus tyre sales. No evidence supports claims about culture, legacy, or unmeasured influence — only documented innovations, patents, and commercial pivots.

Siemens is a German multinational engineering company founded in 1847 as Telegraphen-Bauanstalt von Siemens & Halske in Berlin. It evolved through mergers into Siemens AG in 1966. It makes money from industrial automation, building automation, rail transport, and health technology. Its early model worked: rapid internationalisation via family agents, vertical integration from invention to installation, and patent-backed standard-setting. It does not sustain leadership in all its historical domains: it no longer builds x-ray tubes, electric trams, or passenger trains as standalone products. The gap between Siemens’s founding logic — applied electromagnetism deployed via owned workshops and international agents — and its present structure — a diversified, publicly listed conglomerate with AI and software at its core — reveals how industrial capability gets recoded as platform strategy over time. Yes — if you are studying how engineering firms scale infrastructure innovation into global revenue without pivoting to venture capital narratives.
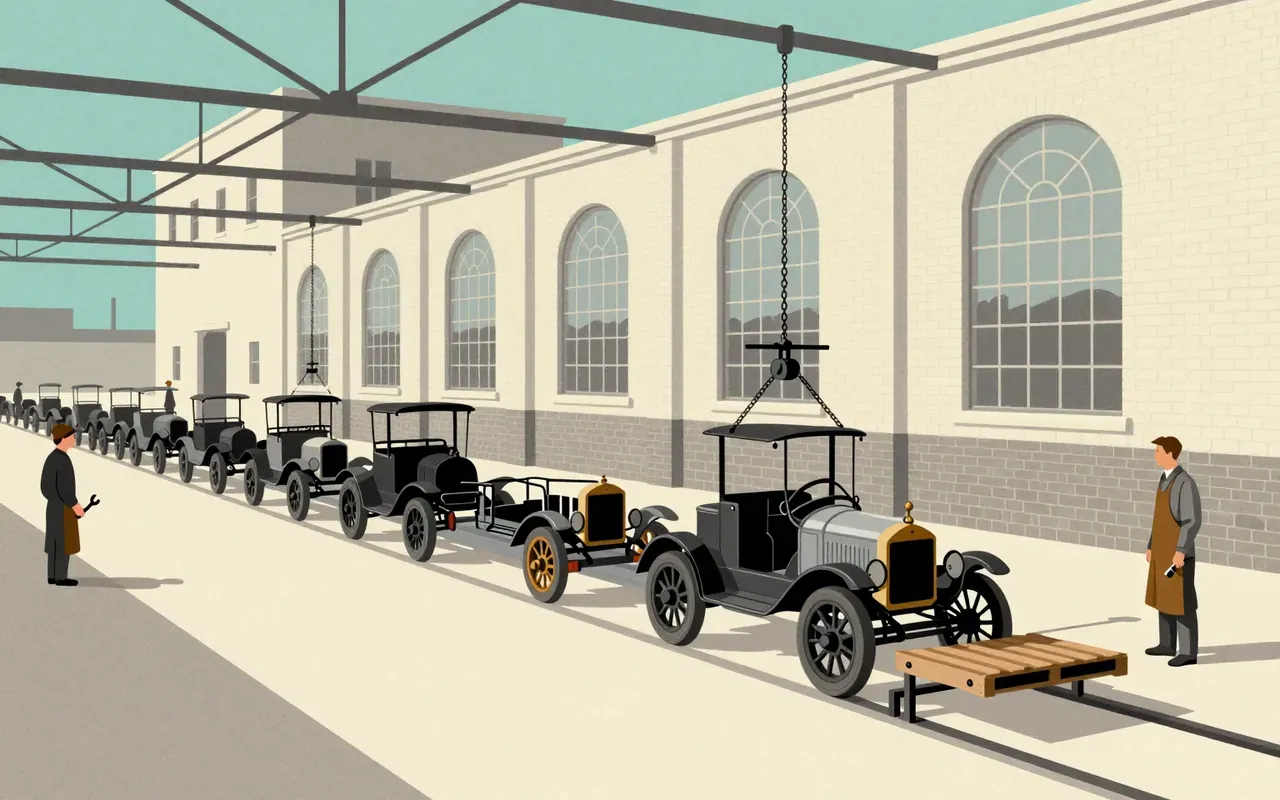
Ford Motor Company was not an idea about mobility—it was a financial and mechanical system for turning $28,000 into 15 million cars. Its power came from eliminating variability: in parts, in process, in price, and eventually in design. It succeeded by making everything repeatable—including authority.

Porsche began as a contract engineering firm — not a carmaker. Its first product was the Volkswagen Beetle, designed for the German government in 1931. It earned royalties on every Beetle built. Only in 1948 did it sell its first car under its own name: the 356, built by hand in a Gmünd sawmill using Beetle-sourced components due to post-war scarcity. Over 78,000 356s were made across 17 years — but the company’s revenue came first from consulting, then royalties, not car sales.
SpaceX is a government-contract-powered aerospace manufacturer whose reusable launch system succeeded where others failed — not because of vision alone, but because NASA paid for development, testing, and flight operations while Starlink created a parallel revenue stream. Its Mars and Starship ambitions remain outside this economic reality.
Toyota’s founding was a licensed, capital-backed industrial pivot — not a startup story.