China Biologic Products
A provincial monopoly masquerading as a biotech company.
Invisible until they break, then the only story.
Hemköp is a Swedish supermarket chain owned by Axfood. It operated around 200 stores in 2024. Its business model relies entirely on physical retail scale within a consolidated ownership structure. No data is provided on margins, digital performance, private label, or customer behaviour. Its value lies in infrastructure reuse — not innovation.

JBS S.A. is the world’s largest meat processor by sales. On May 30, 2021, ransomware disabled its beef and pork slaughterhouses in the US, Canada, and Australia. It paid $11 million in Bitcoin. The White House attributed the attack to a Russian organisation; news outlets named REvil. REvil did not claim responsibility before its infrastructure vanished on July 13, 2021.
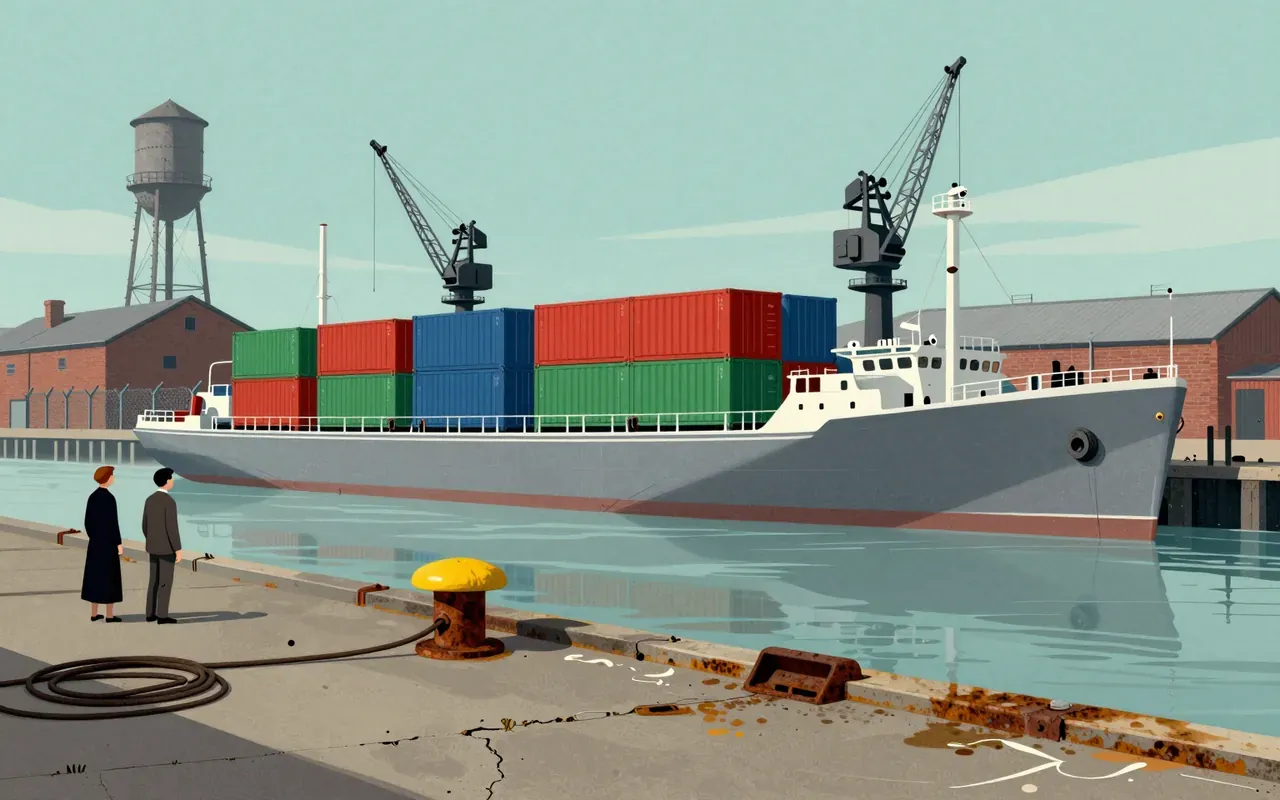
Malcolm McLean’s intermodal container was not an invention but a system — built around a 35-foot steel box sized for Pennsylvania highways, secured by Tantlinger’s corner castings and twistlocks, and operated by Sea-Land’s vertically controlled ships and cranes. It cut port handling time to eight hours — but only on one ship, at one port, under one company’s control. The real innovation was enforcing standardisation through ownership, not designing a better box.
Magnit is a Russian food retailer founded in 1994 in Krasnodar by Sergey Galitsky. It grew rapidly from a regional chain into a national leader, adopting the convenience store format in 2004 and expanding to 1,000 stores by 2000 and 1,500 by 2005—surpassing Pyaterochka in revenue. By 2010 it ranked among the world’s top 250 retailers (Deloitte), and in 2014 became Russia’s largest importer. Its growth continued with milestones including 10,000 stores (2015), entry into pharmacy and drogerie formats, and strategic acquisitions like Dixy (2021) and Samberi (2024). Ownership shifted significantly after 2018, with Marathon Group becoming the largest shareholder in November 2021. Management transitioned from Galitsky to external CEOs starting in 2018, and the company pursued vertical integration via in-house production facilities and distribution infrastructure.
Aldi is not a single company. It is two legally and financially separate firms — Aldi Nord and Aldi Süd — born from a 1960 split triggered by a disagreement over cigarettes. They share a name, a cost-cutting method, and a lineage, but no ownership, no shared board, and no central strategy. Their model works because it eliminates variables: no fresh produce, no advertising, no unsold stock, no large stores, no rebates beyond the legal 3%. By 1960, that method had scaled to 300 stores. Family control ended by 2002. The business survives not through narrative, but through subtraction.
Biocon is a rare case of a biotech company built without VC, without US incorporation, and without founder exit—its growth was constrained and enabled by Indian law, not Silicon Valley logic.
Carrefour is a foundational case in retail format design — not technology, not branding, not finance — but physical integration, location logic, and incremental scaling.
Hyundai Motor is a state-facilitated, scale-first automaker whose power lies in integration — not invention. It controls the largest single auto plant on earth, ranks third globally by output, and sells more hybrids than EVs. Its origin story is contested across sources. Its value is in execution, not narrative.
Kaufland is a German hypermarket chain founded in 1984 in Neckarsulm, part of the Schwarz Gruppe, and developed by Dieter Schwarz as a full-range alternative to Lidl’s discount format. It makes money by selling groceries and general merchandise from hypermarkets averaging over 10,000 m², operating under vertical integration — running in-house bakeries since 1994, meat processing facilities, and organic product lines launched in November 2018. Its strategy of acquiring competitor assets (e.g., 12 famila stores and a Cash-&-Carry-Markt in January 2010) and rebranding existing Handelshof locations gave it rapid scale. It dominates eastern Germany today — a result of opening its first East German store in Meißen in 1990, immediately after reunification. Its Australian expansion failed within a year (2019–2020), exposing limits to its model outside culturally and logistically aligned markets. It does not operate outside Europe. The gap between Kaufland’s self-presentation as a sustainability- and quality-driven retailer (e.g., 2021 decarbonisation strategy, organic range) and its operational reality — acquisitions, rebranding, and regional dominance built on post-reunification timing and antitrust-cleared takeovers — reveals how legacy retail power consolidates without innovation.
Migros is a Swiss retail cooperative founded in 1925 in Zurich by Gottlieb Duttweiler as a private enterprise delivering six staple goods via five lorries to households with limited market access.


Syngenta is a global agricultural technology company headquartered in Basel, Switzerland, operating primarily in crop protection and seeds for farmers. It was founded in 2000 by the merger of the agrichemical businesses of Novartis and AstraZeneca. In 2004, Syngenta Seeds purchased Garst and Golden Harvest Seeds. In February 2016, ChemChina offered to purchase Syngenta for $43 billion, a deal Syngenta unanimously recommended to shareholders. In April 2017, U.S. and European antitrust authorities approved ChemChina's acquisition of Syngenta. To secure regulatory approval, ChemChina agreed to divest pesticide production of paraquat, abamectin, and chlorothalonil.
Takeda’s origin story is misaligned with its present identity: it began as a repackaging merchant, not a drug developer. Its longevity reflects adaptability, not continuity.
Alimentation Couche-Tard is a textbook case of geographic and operational scaling through acquisition and banner standardisation — not product, tech, or marketing innovation. Its model depends on acquiring undermanaged regional chains, stripping overlapping functions, and enforcing consistency in procurement and site selection. It reveals little about consumer behaviour or retail design, but much about how capital, real estate leverage, and decentralised execution combine to dominate fragmented markets.
Asda's origin story is a case study in opportunistic capital allocation — not disruption. It used regulatory shifts, tax law, and real estate terms to scale before it had a coherent brand or national footprint.


Canadian Solar is a vertically integrated solar energy firm founded in 2001 by Dr. Shawn Qu, headquartered in Kitchener, Ontario, with operations spanning manufacturing, project development, and storage system provision.

Dr. Reddy's Laboratories is a business case in disciplined vertical progression: API → branded formulation → export credential → finished product. Its early wins were tactical, not structural. No data on scale, margins, or longevity is provided — only sequence, timing, and pricing intent.
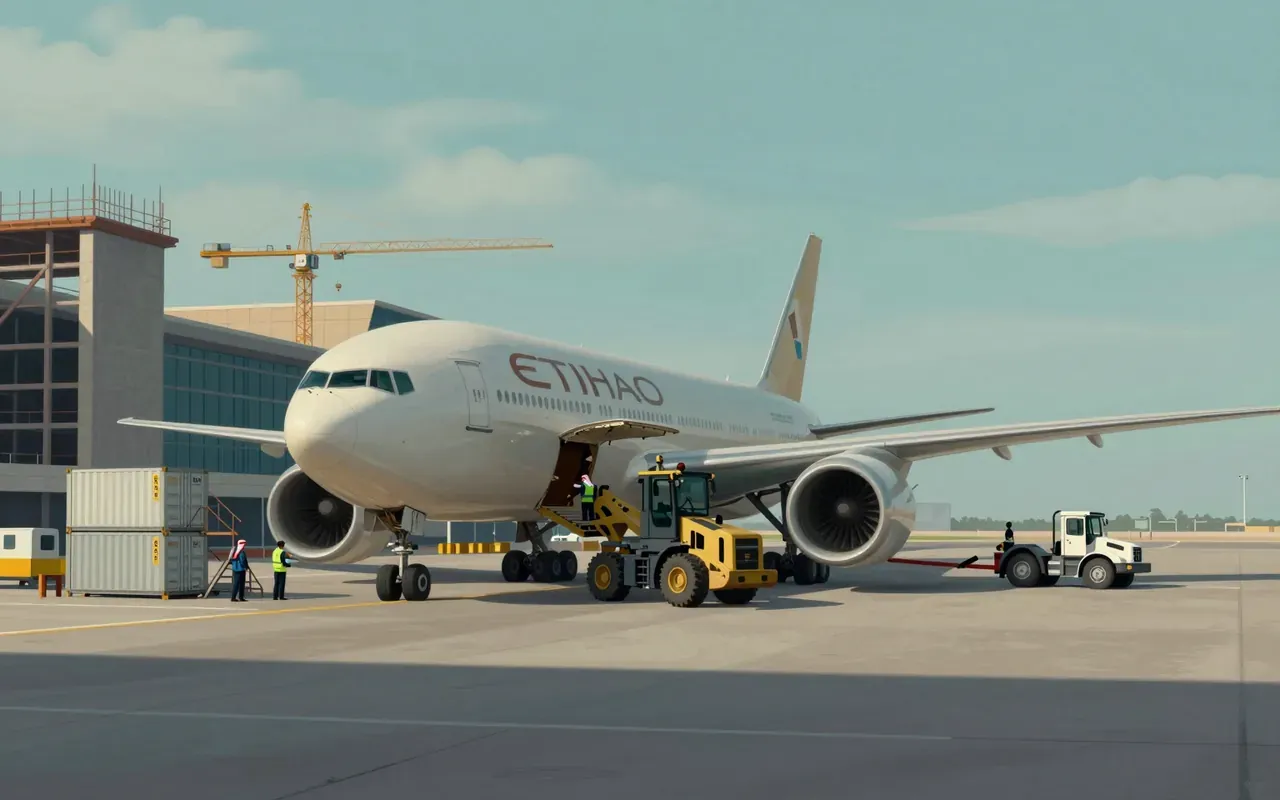
Etihad Airways is a state-owned UAE flag carrier launched in 2003 to project national presence globally. It operates passenger, cargo, and holiday services from Zayed International Airport using a fleet of 107 aircraft. It is the second-largest airline in the UAE after Emirates. Its business model relies on sovereign backing—not unit economics—to sustain scale beyond its home market’s natural demand.
FEMSA is a Mexican multinational beverage and retail company headquartered in Monterrey, operating the largest independent Coca-Cola bottling group in the world and Mexico’s largest convenience store chain. It reports US$26.9 billion in revenue (2019), ranks fifth-largest company in Mexico, and operates across Latin America via bottling plants, convenience stores, drugstores, fuel stations, and third-party logistics—and in the US via jan-san distribution. Listed on the Mexican Stock Exchange since 1978 and NYSE ADRs since 1998. FEMSA is the holding company of Cuauhtémoc Moctezuma Brewery—the culmination of Eugenio Garza Sada’s industrial expansion from a single brewery into Grupo Valores Industriales, which included Fábricas de Monterrey (1920), HYLSA (1942), Empaques de Cartón Titán (1936), and multiple acquired breweries.
First Solar is a U.S. solar panel manufacturer that builds cadmium telluride (CdTe) thin-film modules in domestic factories. It was founded in 1990 as Solar Cells, Inc. by Harold McMaster, acquired and rebranded in 1999, and went public in 2006. Its technology diverges from mainstream silicon PV. As of March 2026, it had ~14 GW of annual domestic nameplate capacity across facilities in Ohio, Alabama, and Louisiana. It does not produce silicon panels, does not operate overseas factories, and does not integrate storage or software.

Natura built a global cosmetics business using direct sales—not digital platforms—and anchored its identity in ethical sourcing and animal-testing bans. It listed on Brazil’s highest-governance stock exchange tier in 2004. But none of its stated commitments include third-party verification, cost impact, or enforcement mechanisms. Its scale—6.6 million consultants in 2018—is real. Its ethics are aspirational.

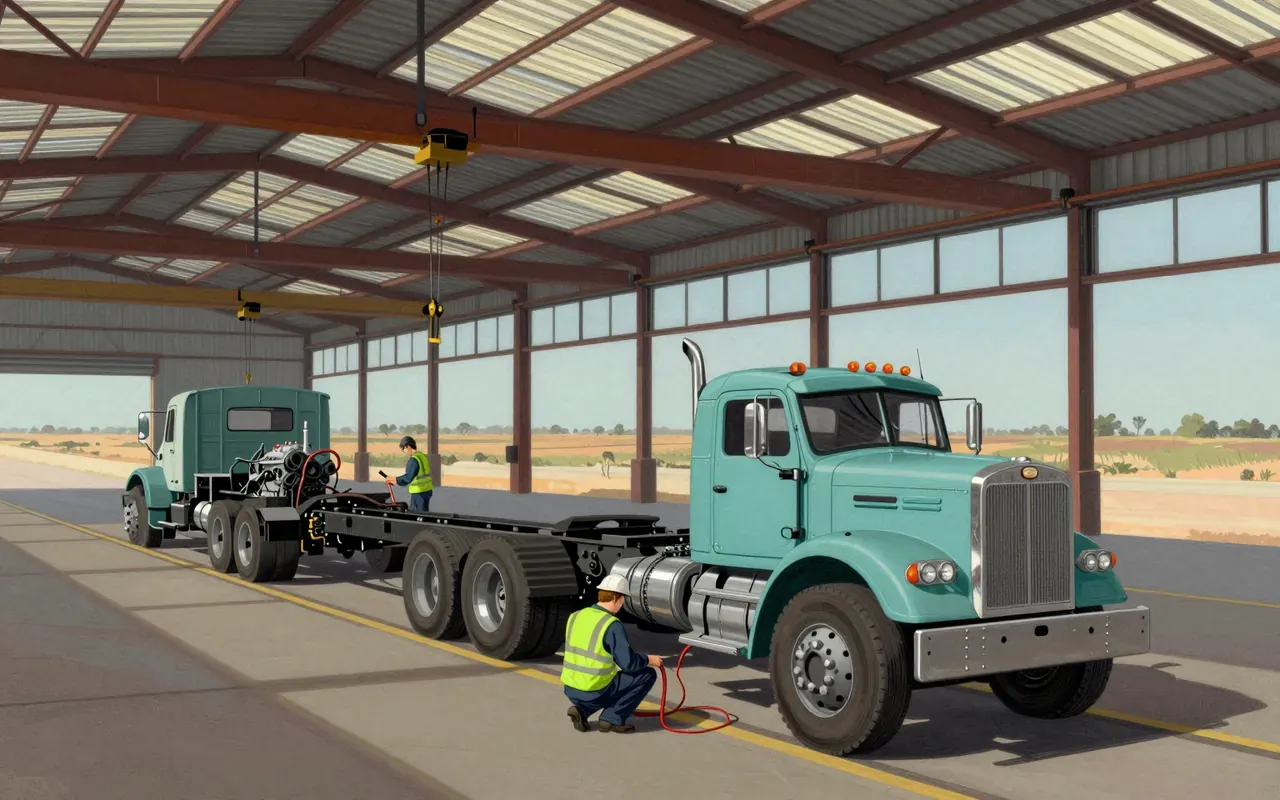
Peterbilt is a case study in acquisition-led industrial continuity: a timber operator bought a defunct truck maker to solve local hauling problems, engineered narrowly effective solutions, scaled only when external demand (military) appeared, and exited when land value exceeded truck value. Its legacy lies in execution, not vision.

Pfizer’s origin story is not about curing disease — it is about solving chemical supply problems with fermentation. Its therapeutic dominance came decades after it mastered industrial microbiology under pressure.
Beyond Meat is a plant-based meat alternative producer founded in 2009 by Ethan Brown to mitigate climate change. It licensed meatless protein technology from University of Missouri professors, launched its first product in 2012, its signature Beyond Burger in 2016, and became the first publicly traded company in its category in 2019. It announced layoffs of 19% of staff in October 2022 due to revenue declines and additional layoffs in November 2023 after a 9% sales decline.
BYD is a battery-born, vertically integrated Chinese manufacturing conglomerate whose automotive business now dominates its revenue and global EV output — but the sources disclose no financials, no unit economics, and no evidence of why its integration delivers advantage beyond scale and employment headcount.
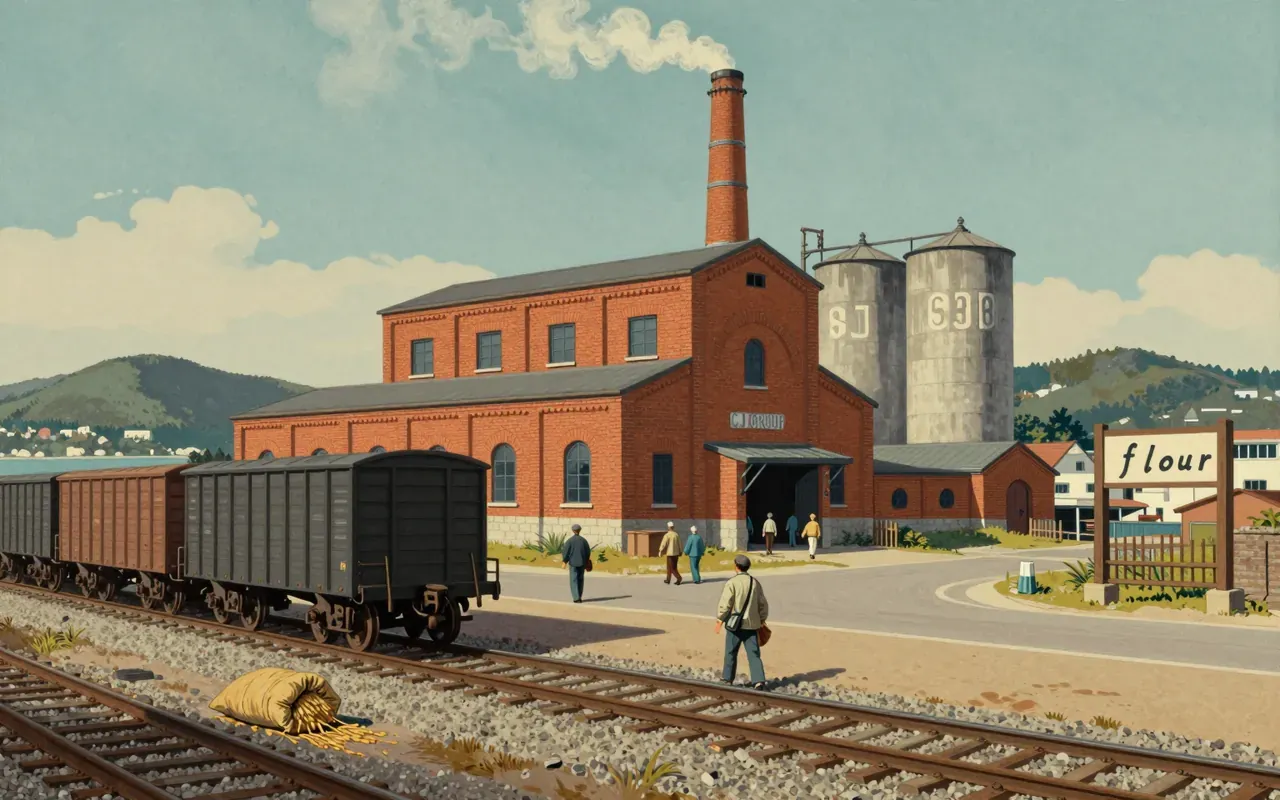
CJ Group is a South Korean chaebol that originated in 1953 as Samsung’s first manufacturing unit: a sugar and flour producer named CheilJedang. It established early industrial firsts — Korea’s first flour mill (1958), first sugar export to Okinawa (1962), and first branded sugar (Beksul, 1965). Its independence from Samsung followed a legal dispute among the Lee family — not market forces. Today it operates across food, bio, logistics, and entertainment, but the sources give no detail on how those businesses interconnect, profit, or compete. It is a case study in legacy infrastructure and familial fracture — not scalable strategy or innovation.

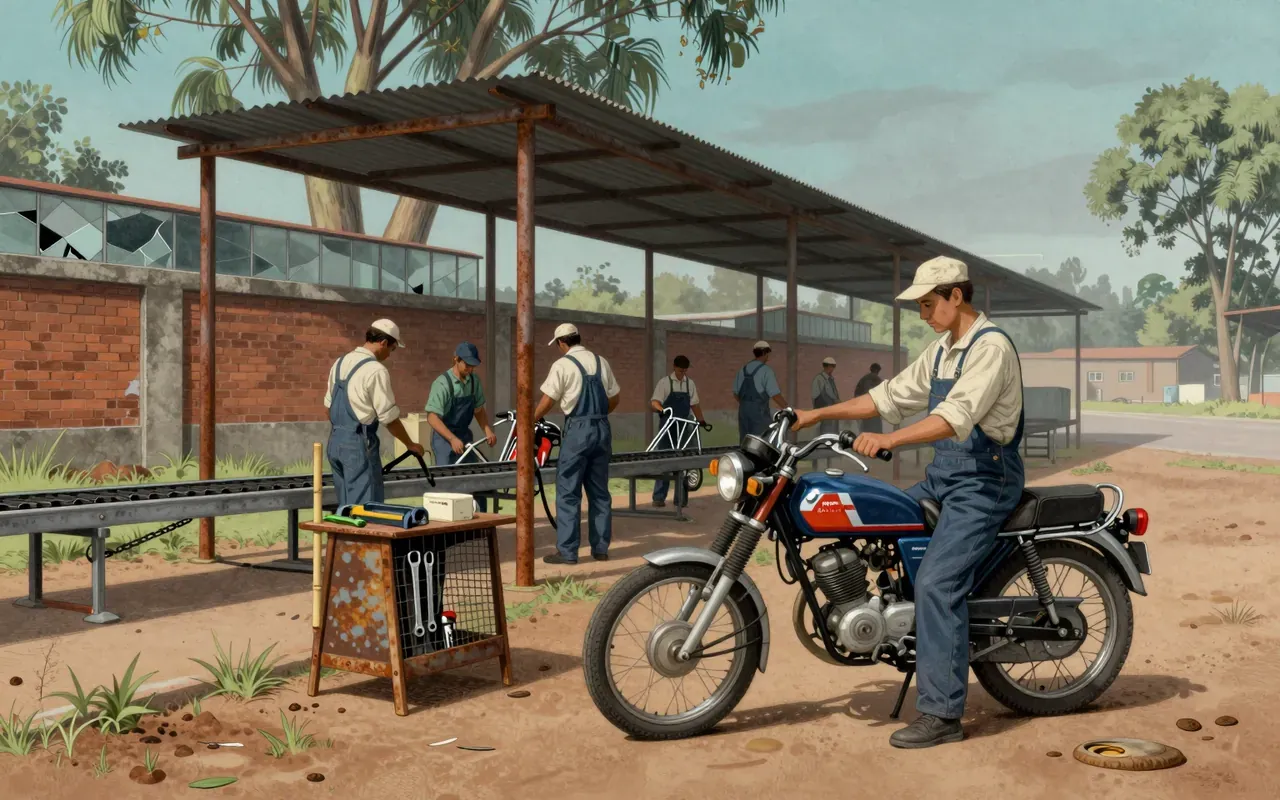
Hero MotoCorp is a case study in state-enabled industrial scaling: it leveraged licences, joint ventures, and low-cost execution—not proprietary tech or global branding—to become India’s dominant two-wheeler maker. Its independence from Honda was real, but its post-2011 growth relies on the same mechanics: volume, distribution, and incremental product iteration.
JD.com is not a platform play. It is a logistics-and-service company disguised as an e-commerce site. Its scale comes from owning the last mile — and the first response.

Nestlé is a case study in how industrial food companies scale not through singular genius, but through technical borrowing, wartime procurement, and post-war recalibration. Henri Nestlé invented a product, then exited. The company that bears his name grew via merger, contract, and consolidation — not continuity.
Netflix is a case study in operational iteration — not technological invention. Its value lies in how it structured incentives, removed friction, and scaled infrastructure — not in what it claimed to be.
Shein is a global fast fashion e-commerce platform founded in 2008 in Nanjing, China, and currently headquartered in Singapore. It began as a drop shipping-style operation sourcing from Guangzhou’s wholesale market, then transformed into a fully integrated retailer starting in 2012. Its product range spans women’s, men’s, and children’s apparel plus accessories and cosmetics, targeting Europe, the Americas, Australia, and the Middle East. Its growth has been tied to popularity among younger Millennials and older Gen Z consumers, enabled by low pricing and rapid trend response.

Uber is a platform whose early growth relied on regulatory noncompliance, strategic rebranding, and reactive imitation — not technical invention or user-first design. Its financial mechanics are transparent: high take rates on massive transaction volume. Its story is not about disruption, but about exploiting gaps between law and enforcement.
Uniqlo is a case study in industrialised apparel: no hype, no heritage theatre, no seasonal spectacle — just a tightly coupled system for making, moving, and refining simple clothes at scale.
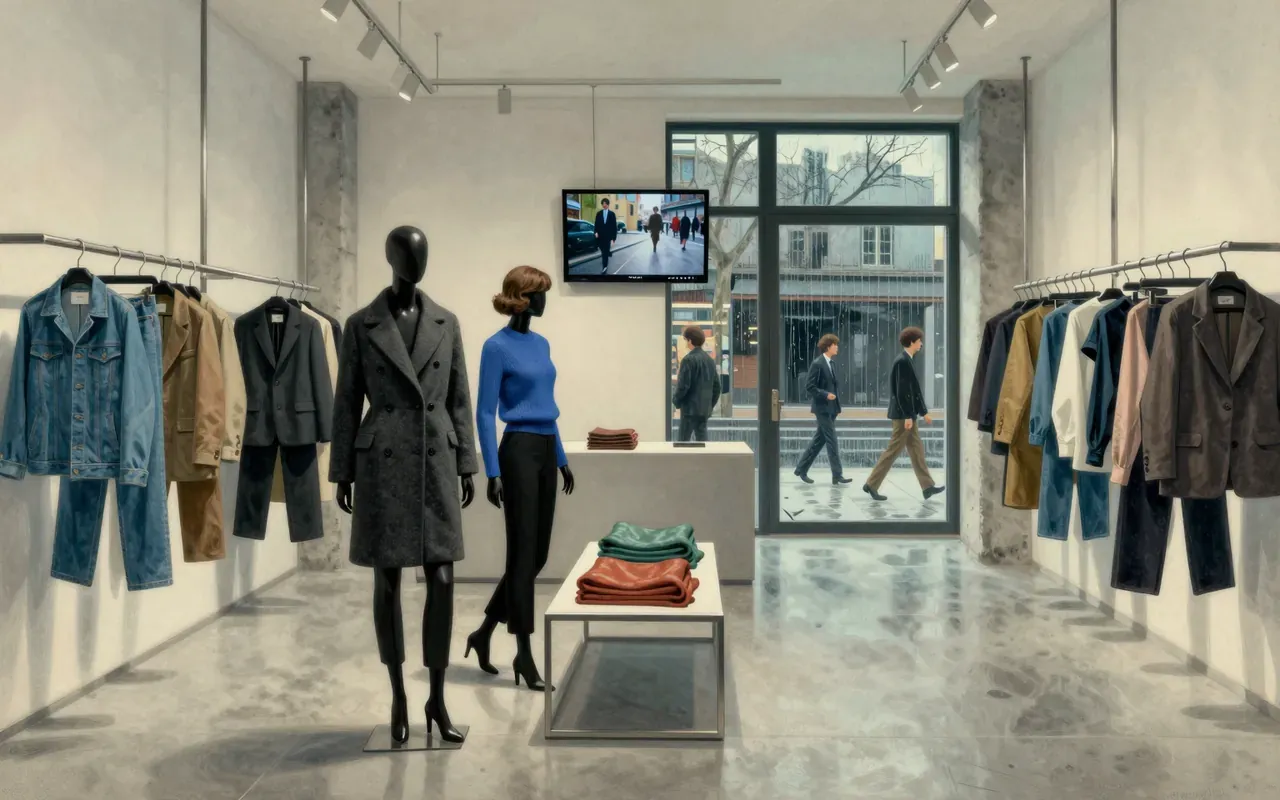
Zara is a case study in operational rigour, not branding or tech. Its advantage is physical: proximity, control, and repetition — not algorithms or virality.
TSMC is the world’s largest and most advanced contract chipmaker — a state-enabled, capital-intensive factory system that executes Moore’s Law with industrial rigour. Its dominance comes not from vision or branding, but from delivering real chips, on schedule, at scale.
Amazon is a vertically integrated infrastructure company disguised as a retailer. Its founding was opportunistic, its growth funded by reinvestment, not profit. Its dominance rests on owning the pipes — logistics, compute, storage, and distribution — not the content or brands moving through them.

The Coca-Cola Company was founded in 1892 by Asa Griggs Candler in Atlanta after he purchased the formula from John Stith Pemberton in 1888. It generated revenue by manufacturing and selling syrup to soda fountains, then licensing bottling rights for $1 per territory — a contract that transferred capital and operational risk to third parties while preserving brand control. By 1895 it achieved nationwide US distribution; exports began in 1899 (Cuba) and 1901 (Europe). Candler trademarked the brand and paid dividends in 1893, proving early financial viability. The model worked because it scaled without infrastructure — but failed to ensure product consistency across bottlers. This is a masterclass in leveraging intellectual property through contractual design, not product innovation.
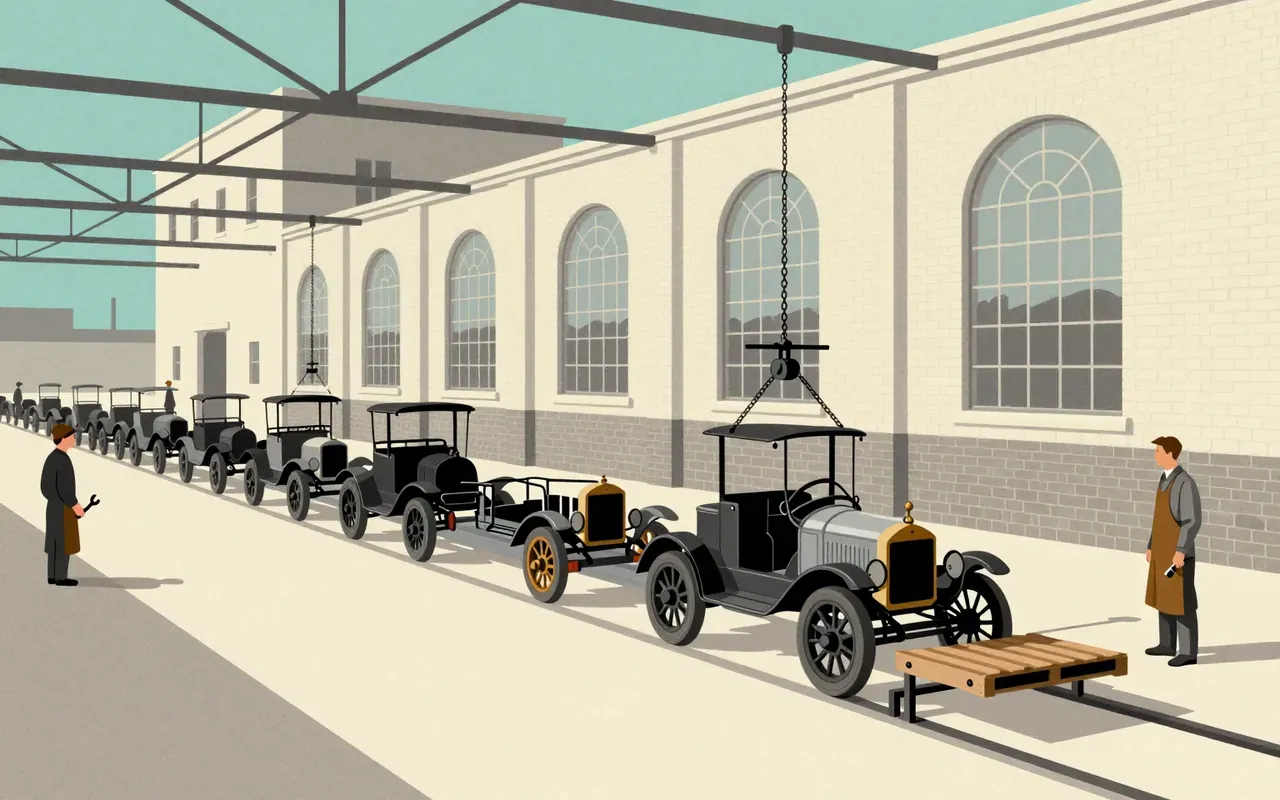
Ford Motor Company was not an idea about mobility—it was a financial and mechanical system for turning $28,000 into 15 million cars. Its power came from eliminating variability: in parts, in process, in price, and eventually in design. It succeeded by making everything repeatable—including authority.
IKEA is a case study in disciplined execution — not innovation. Its success rests on replicating a single operating model globally, enforced by geographic and legal separation between brand and retail. Nothing in the source material supports claims about culture, sustainability, or digital transformation — only cost, control, and structure.

McDonald's is not a restaurant chain but a replication system — built on enforceable standardisation and deliberately constrained franchising. Its economics rely on control, not volume, and its origin story is a legal rebranding of a hostile acquisition.

Nike’s origin is a textbook case of a startup succeeding not by inventing a category, but by reengineering a supply chain — then iterating relentlessly on one functional detail: traction.

Nintendo’s origin is a case study in operational discipline over narrative ambition. It succeeded by controlling production hardware, exploiting regulatory shifts, and locking in high-frequency buyers — not by inventing games or chasing culture.
PepsiCo is a post-1965 corporate construct. Its name recalls, but does not continue, Caleb Bradham’s 1893 pharmacy invention — a digestive soda that failed because of commodity price risk, not brand weakness.
Samsung’s origin contradicts its current identity: it was a trading and transport firm, not a tech innovator. Its electronics entry was late, small-scale, and licence-dependent — a strategic pivot enabled by infrastructure, not invention.
Toyota’s founding was a licensed, capital-backed industrial pivot — not a startup story.

Walmart’s early success was mechanical, not magical. It used known levers — location, transport, procurement — with unusual discipline. Its story is not about disruption but about execution fidelity.