Ray Kroc
Ray Kroc was the American businessman who bought McDonald's in 1961 and helped turn it into a worldwide franchise chain.
The thinking a company runs on — strategy, money, product, management — tested against what firms do rather than what they say.
Bear Stearns collapsed because its business model depended on continuous short-term funding — and when counterparties stopped rolling over repo loans, liquidity vanished faster than capital could be deployed. Its balance sheet held value, but confidence did not. The firm was sold to JPMorgan Chase in a Fed-brokered fire sale.
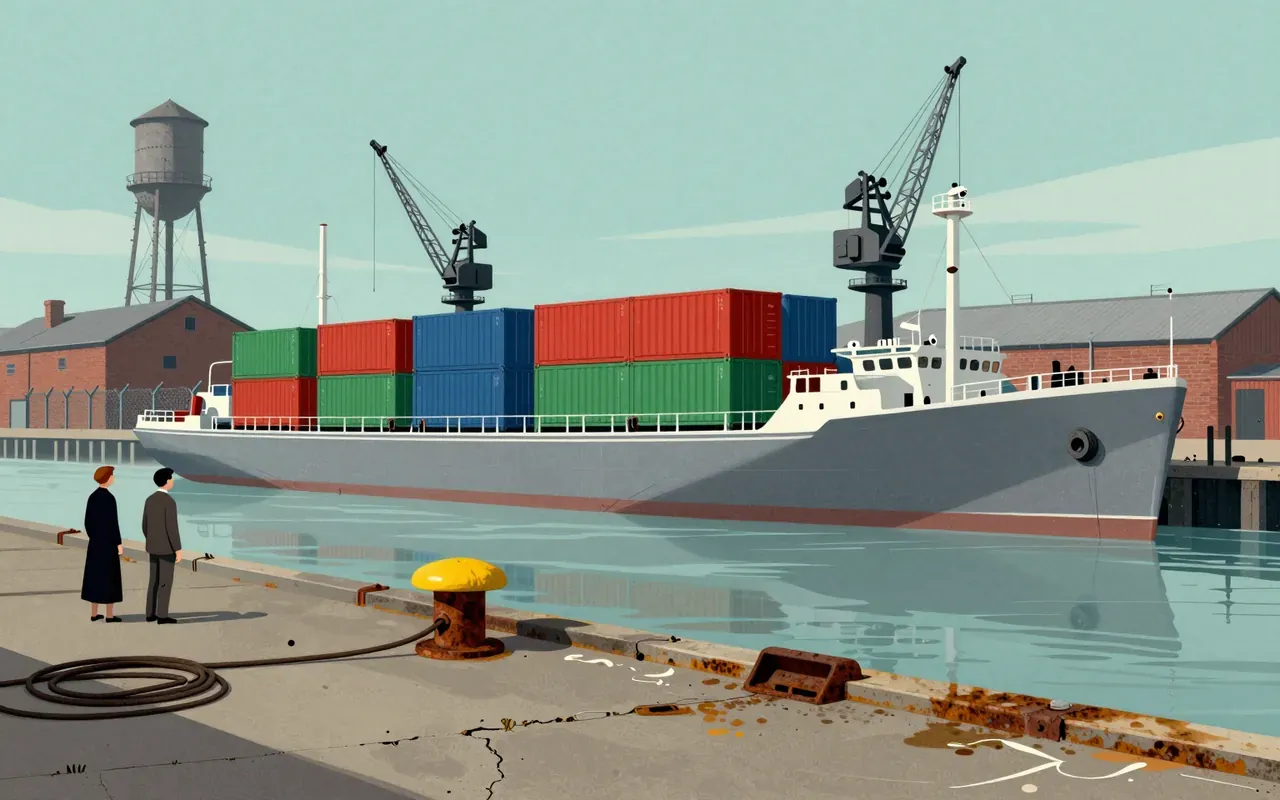
Malcolm McLean’s intermodal container was not an invention but a system — built around a 35-foot steel box sized for Pennsylvania highways, secured by Tantlinger’s corner castings and twistlocks, and operated by Sea-Land’s vertically controlled ships and cranes. It cut port handling time to eight hours — but only on one ship, at one port, under one company’s control. The real innovation was enforcing standardisation through ownership, not designing a better box.

Barrick Mining is a gold-and-copper extraction company built through strategic acquisitions — not innovation, not discovery, not vertical integration. Its value lies in scale: 89 million ounces of gold in reserves, 3.91 million ounces produced in 2024, and a history of absorbing rivals like Placer Dome. But its governance fails where operations meet people: in 2008, Peter Munk personally silenced testimony about violence at Porgera. That gap — between reserve size and human accountability — is the real story.
JBS S.A. is the world’s largest meat processor by sales. On May 30, 2021, ransomware disabled its beef and pork slaughterhouses in the US, Canada, and Australia. It paid $11 million in Bitcoin. The White House attributed the attack to a Russian organisation; news outlets named REvil. REvil did not claim responsibility before its infrastructure vanished on July 13, 2021.
Google DeepMind is a research lab, not a business. Its value lies in its ability to produce peer-recognised scientific milestones — not revenue, not IP licensing, not product deployment. It proves that one company can fund high-risk, long-horizon AI research at industrial scale — but only by insulating it entirely from market logic.
Google is a search engine company founded in 1998 by Larry Page and Sergey Brin. Its core technology, PageRank, ranked websites by inbound links — a method co-published with Motwani and Winograd and patented by Stanford. Scott Hassan wrote the first implementation. The company launched from Susan Wojcicki’s garage. Its name misspelled 'googol' to signal scale. Initial funding came from Andy Bechtolsheim’s $100,000 cheque in August 1998. The sources say nothing about advertising, revenue, users, infrastructure costs, or market position beyond this.
Free is a vertically integrated French ISP that built its own networks, hardware, and pricing model — rejecting reliance on incumbents and subscription lock-in. It achieved profitability and low churn through infrastructure control and disciplined bundling, not venture funding or hype.

Emirates is a state-owned UAE flag carrier founded in 1985 after Gulf Air reduced Dubai services. It operates over 3,600 weekly flights from Dubai International Airport’s Terminal 3, serves 150+ cities across six continents, and ranks third globally by passenger volume and second by freight volume. Its ownership lies with Dubai’s Investment Corporation of Dubai, and its cargo arm is Emirates SkyCargo. It is not part of any global airline alliance.
Hyundai Motor is a state-facilitated, scale-first automaker whose power lies in integration — not invention. It controls the largest single auto plant on earth, ranks third globally by output, and sells more hybrids than EVs. Its origin story is contested across sources. Its value is in execution, not narrative.
Kaufland is a German hypermarket chain founded in 1984 in Neckarsulm, part of the Schwarz Gruppe, and developed by Dieter Schwarz as a full-range alternative to Lidl’s discount format. It makes money by selling groceries and general merchandise from hypermarkets averaging over 10,000 m², operating under vertical integration — running in-house bakeries since 1994, meat processing facilities, and organic product lines launched in November 2018. Its strategy of acquiring competitor assets (e.g., 12 famila stores and a Cash-&-Carry-Markt in January 2010) and rebranding existing Handelshof locations gave it rapid scale. It dominates eastern Germany today — a result of opening its first East German store in Meißen in 1990, immediately after reunification. Its Australian expansion failed within a year (2019–2020), exposing limits to its model outside culturally and logistically aligned markets. It does not operate outside Europe. The gap between Kaufland’s self-presentation as a sustainability- and quality-driven retailer (e.g., 2021 decarbonisation strategy, organic range) and its operational reality — acquisitions, rebranding, and regional dominance built on post-reunification timing and antitrust-cleared takeovers — reveals how legacy retail power consolidates without innovation.

Biocon is a rare case of a biotech company built without VC, without US incorporation, and without founder exit—its growth was constrained and enabled by Indian law, not Silicon Valley logic.

Alimentation Couche-Tard is a textbook case of geographic and operational scaling through acquisition and banner standardisation — not product, tech, or marketing innovation. Its model depends on acquiring undermanaged regional chains, stripping overlapping functions, and enforcing consistency in procurement and site selection. It reveals little about consumer behaviour or retail design, but much about how capital, real estate leverage, and decentralised execution combine to dominate fragmented markets.
Ambev is a case study in consolidation-driven profitability — not product-led growth. Its value came from regulatory navigation, cost discipline, and geographic sequencing, not brand, taste, or technology. It shows how monopoly conditions can be manufactured where competition is weak, not defeated.
Asda's origin story is a case study in opportunistic capital allocation — not disruption. It used regulatory shifts, tax law, and real estate terms to scale before it had a coherent brand or national footprint.

British Airways is the UK’s flag carrier, formed by state merger in 1974, privatised in 1987, and folded into IAG in 2011. It is the largest UK airline by fleet and international reach. It was the first passenger airline to earn over $1 billion on a single route in a year. It has a documented reputation for poor staff conduct, arbitrary service changes, and refusing compensation claims.
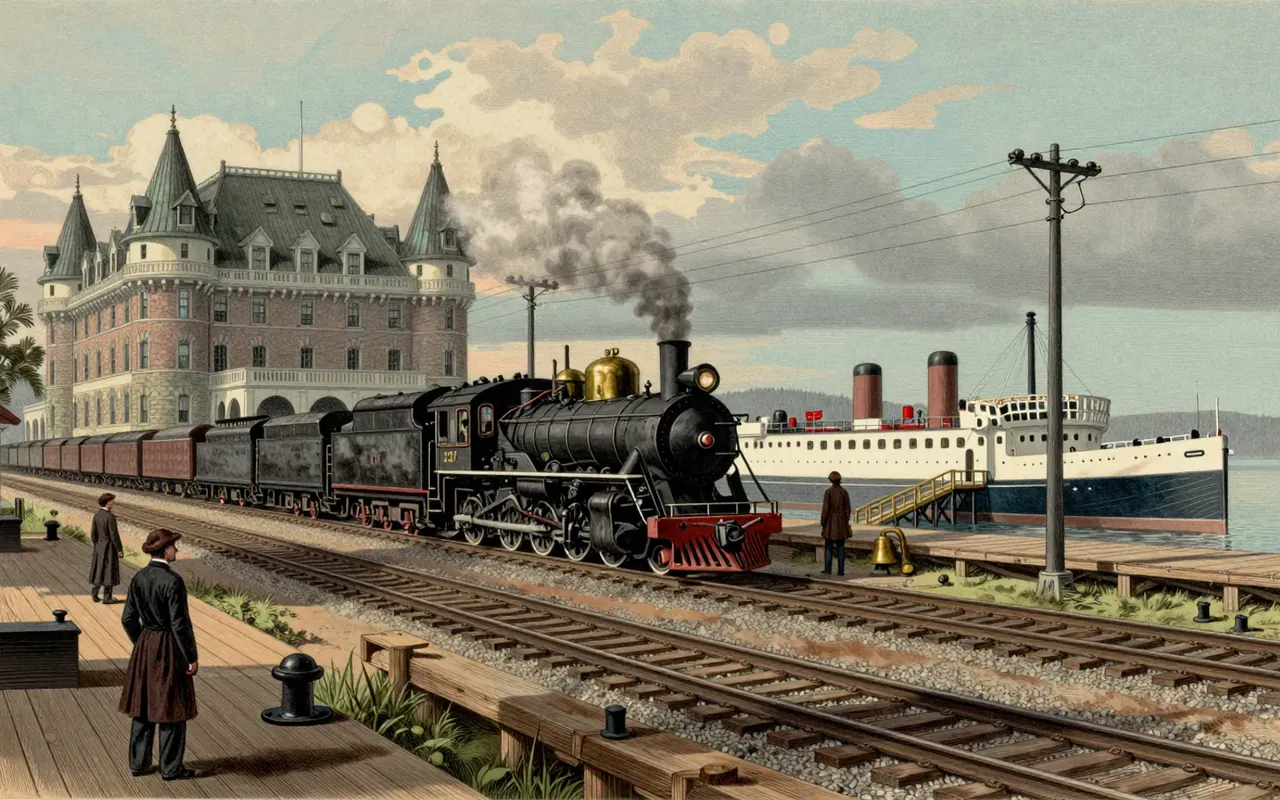
The Canadian Pacific Railway was not a startup, nor a disruptor — it was a state-contracted infrastructure monopoly, executed under tight political deadline and scaled through vertical integration. Van Horne’s genius lay not in invention but in orchestration: he turned a rail line into a self-reinforcing system of movement, messaging, lodging, and shipping — all funded by federal land grants, bonds, and tariffs, not market demand. Its success was geopolitical, not financial; its durability came from control of geography, not innovation.

De Beers is a case study in artificial scarcity — built not on geology or technology, but on merger, capital, and contract.

Dr. Reddy's Laboratories is a business case in disciplined vertical progression: API → branded formulation → export credential → finished product. Its early wins were tactical, not structural. No data on scale, margins, or longevity is provided — only sequence, timing, and pricing intent.
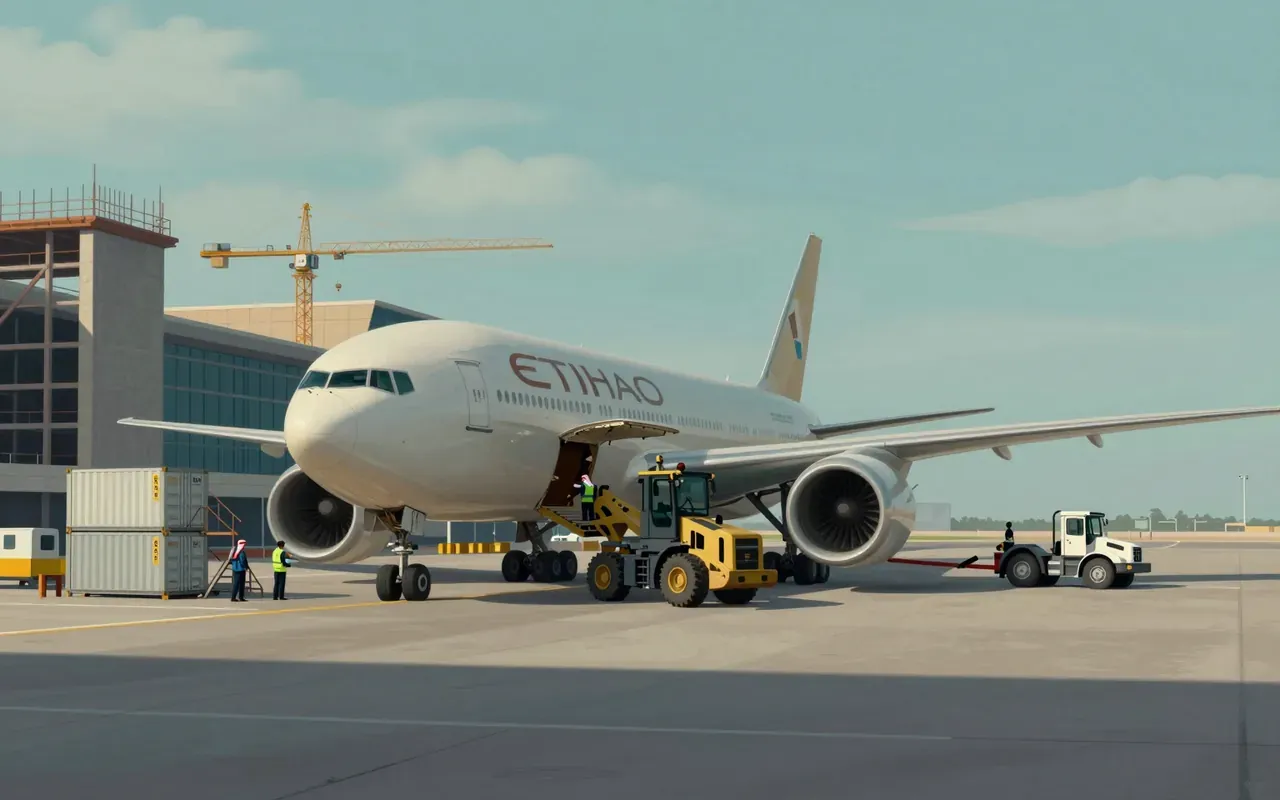
Etihad Airways is a state-owned UAE flag carrier launched in 2003 to project national presence globally. It operates passenger, cargo, and holiday services from Zayed International Airport using a fleet of 107 aircraft. It is the second-largest airline in the UAE after Emirates. Its business model relies on sovereign backing—not unit economics—to sustain scale beyond its home market’s natural demand.
George Weston Limited is a Canadian holding company founded in 1882, structured around two core assets: Loblaw Companies Limited and Choice Properties REIT.



Lamborghini is a case study in disciplined positioning: a luxury carmaker built on agricultural engineering, anchored in one town, defined by one cultural metaphor, and repeatedly tested — and sometimes broken — by global economic forces.
Lukoil is a Russian multinational energy corporation headquartered in Moscow, formed in 1991 by merger of three state-run western Siberian oil enterprises: Langepasneftegaz, Urayneftegaz, and Kogalymneftegaz.


Soros Fund Management is a case study in regulatory adaptation: a firm that built its reputation on transparency of idea (macro thesis) and opacity of structure (family office), where the numbers remain impressive but uncheckable.
Natura built a global cosmetics business using direct sales—not digital platforms—and anchored its identity in ethical sourcing and animal-testing bans. It listed on Brazil’s highest-governance stock exchange tier in 2004. But none of its stated commitments include third-party verification, cost impact, or enforcement mechanisms. Its scale—6.6 million consultants in 2018—is real. Its ethics are aspirational.
Apollo Global Management is a $1.03 trillion alternative asset manager built on distressed-to-control investing, co-founded in 1990 by ex-Drexel bankers. It earns fees from pension funds, endowments, and sovereign wealth funds deploying capital across credit, private equity, and real assets. Its model works at scale—but its credibility fractures where leadership conduct contradicts its governance claims. The $158 million paid to Jeffrey Epstein did not disrupt operations, but it ended Leon Black’s tenure and exposed a rift between Apollo’s discipline-as-brand and its human risk.

Blackstone is the largest alternative investment firm by AUM — $1.2 trillion as of September 2025, $1.3 trillion by Q1 2026 — built on a pivot from M&A advisory to merchant banking in 1987. Its founders lacked LBO experience but leveraged relationships to enter private equity, then scaled across asset classes using consistent mechanics: leverage, illiquidity, and fee-based capital aggregation. Its CEO held formal advisory access to the U.S. presidency, but that did not substitute for early fundraising credibility. The firm discloses neither performance nor risk metrics for its funds. Its growth reflects structural demand — not proprietary insight.

Carlyle is a textbook case of how a firm leverages geography and timing — not product innovation — to dominate a financial services niche. Its business model remains fee-dependent, opaque, and unremarkable in mechanics. Its value lies in its path, not its current structure.
CME Group is a vertically integrated derivatives infrastructure operator. It runs exchanges, provides mandatory central clearing, and operates two spot platforms. In 2025, 81% of its revenue came from clearing and transaction fees, charged at $0.70 per contract across over 7 billion contracts. Volume increases during market volatility — a mechanical, observable feature. Its Bitcoin spot launch in May 2024 has no reported volume or revenue impact. Every major innovation — currency futures (1972), Globex (1987), IPO (2002) — was structural, not product-led.


ICE is a financial infrastructure consolidator — not a technology innovator or market creator. It turned energy trading into a global clearing and exchange empire by acquiring failing or exposed rivals, shutting down physical floors, and layering data and mortgage tech atop core exchange revenue. Its business model depends on regulatory moats, scale-driven pricing, and vertical integration — not speed, intelligence, or user experience.

KKR is a foundational leveraged buyout firm whose early success relied on regulatory change, not market demand — and whose most famous deal was unprofitable. Its current scale reflects diversification beyond private equity, not enduring deal-making superiority.
Moody's Ratings is the credit ratings division of Moody's Corporation, rebranded from Moody's Investors Service in March 2024. It provides international financial research on bonds issued by commercial and government entities, operates as one of the Big Three credit rating agencies, uses a standardized ratings scale measuring expected investor loss in default, assigns ratings from Aaa (highest) to C (lowest), and was founded by John Moody in 1909 to produce manuals of statistics related to stocks, bonds, and bond ratings.

Nasdaq is not a disruptor — it is the incumbent infrastructure operator. Its value lies in ownership of exchange platforms, data feeds, and listing rules — not in technological novelty, which has long since been replicated. It works where liquidity and branding converge: tech IPOs, real-time data sales, and cross-border access. It falls short as a neutral arbiter: its incentives align with listed companies and high-frequency traders, not retail investors or public market integrity. The gap between its self-presentation as a ‘market enabler’ and its actual function as a toll collector is wide — and profitable.




Genmab is a platform biotech — not a drug developer — built around two licensed and proprietary antibody generation methods. Its value is in reducing discovery risk and time, not in owning clinical or commercial outcomes.
Volvo’s origin was not a corporate spin-off or investor-backed startup. It was a personal bet — financed by commissions saved in Paris, structured around a high-risk contract, validated by ten physical prototypes, and launched only after institutional rejection. Its early revenue came from trucks, not cars. Its founding story contradicts the myth of visionary consensus — it was a solo act of leverage, execution, and timing.
ABB is a post-merger industrial incumbent whose value lies in proven, regulated, physical infrastructure — not software, platforms, or scalability stories.

Biogen is a neurology-focused biotech that built scale via acquisition, not foundational science — and César Milstein, whose hybridoma work underpins modern antibody therapeutics, has no documented relationship to the company.
First Solar is a U.S. solar panel manufacturer that builds cadmium telluride (CdTe) thin-film modules in domestic factories. It was founded in 1990 as Solar Cells, Inc. by Harold McMaster, acquired and rebranded in 1999, and went public in 2006. Its technology diverges from mainstream silicon PV. As of March 2026, it had ~14 GW of annual domestic nameplate capacity across facilities in Ohio, Alabama, and Louisiana. It does not produce silicon panels, does not operate overseas factories, and does not integrate storage or software.
AMD is not a story of disruption — it is a story of licensed dependence, contested access, and court-mandated self-reliance in semiconductor design.
Bharti Airtel is not a tech innovator but a regulatory arbitrageur—its real product is the ability to operate at scale across borders where others stall on licensing, spectrum, or infrastructure cost. It built nothing foundational in telecom standards or silicon, but mastered the sequencing: assemble → manufacture → license → outsource → bundle → expand. That sequence works only once per market—and only if you start before the rules harden.
BYD is a battery-born, vertically integrated Chinese manufacturing conglomerate whose automotive business now dominates its revenue and global EV output — but the sources disclose no financials, no unit economics, and no evidence of why its integration delivers advantage beyond scale and employment headcount.

The Walt Disney Company is an American multinational mass media and entertainment conglomerate founded on October 16, 1923, as the Disney Brothers Studio by Walt and Roy Disney in California. It rose to prominence in animation with Steamboat Willie (1928), diversified into live-action films, television, and theme parks in the 1950s, reversed a post-1966 decline under Michael Eisner via international theme park expansion and the Disney Renaissance (1989–1999), and transformed into a major entertainment conglomerate under Bob Iger through strategic acquisitions (Pixar, Marvel, Lucasfilm, 21st Century Fox). It operates the largest television and film studio in Hollywood.


Geely is a founder-led, family-financed industrial pivot machine — not a tech innovator or brand builder. It built scale by acquiring assets (Volvo, Lotus, Smart, Aston Martin), not customers. Its business model relies on platform reuse and regulatory arbitrage, not margin expansion or consumer loyalty. Verified financials are absent. Its most durable tactic is holding equity stakes where others seek control.
H&M is a Swedish multinational clothing company headquartered in Stockholm, founded in 1947 by Erling Persson in Västerås as a women’s-only retailer named Hennes. Built on a fast fashion business model, it sells apparel, accessories, and homeware. In 1968, Persson acquired the hunting apparel retailer Mauritz Widforss, added menswear, and changed the name to Hennes & Mauritz. The company was listed on the Stockholm Stock Exchange in 1974 and opened its first store outside Scandinavia in London in 1976. It began online retailing in 1998 using the domain hm.com, registered in 1997.
Huawei is a Chinese multinational technology conglomerate founded in Shenzhen in 1987 by Ren Zhengfei. Its headquarters are in Longgang, Shenzhen, Guangdong. Its main product lines include telecommunications equipment, consumer electronics, electric vehicle autonomous driving systems, and rooftop solar power products. Telecommunications equipment is its biggest area of business, and its largest customer is the Chinese government. Initially focused on manufacturing phone switches, Huawei expanded to more than 170 countries, building telecom infrastructure, providing equipment and services, and manufacturing consumer communications devices. In 2012, it surpassed Ericsson to become the world's largest telecommunications equipment manufacturer. As of 2025, it is the largest smartphone vendor in China with an 18.1% market share.
JD.com is not a platform play. It is a logistics-and-service company disguised as an e-commerce site. Its scale comes from owning the last mile — and the first response.

Kobe Steel is a Japanese industrial conglomerate whose name misleads: steel accounts for the smallest share of its business among major Japanese steelmakers. It grew not through market innovation but via naval technical guidance and orders after the Russo-Japanese War. Its real strengths lie in wire rods, transport aluminium, screw compressors, and wholesale power supply—three distinct divisions operating semi-independently. The gap between its identity (a steel company) and its economics (a diversified industrial group) is structural, not accidental.
Kodak was not a camera company first — it was a film company that used cameras to distribute its consumable. Its 1888 system created a new market by removing technical barriers. Its dominance came from controlling the film supply chain, not the hardware. No source mentions digital disruption, so the brief stops at peak film-era success.
LG Electronics is a vertically integrated South Korean hardware manufacturer whose post-war origins, protected domestic launch, and 1995 rebranding reveal more about industrial policy than innovation mythology.
L'Oréal is the world's largest cosmetics company — not because it invented beauty, but because it industrialised chemistry, controlled distribution, and systematised intellectual property.

LVMH is a French multinational luxury goods conglomerate formed in 1987 by merger—not founded—of Louis Vuitton and Moët Hennessy. Bernard Arnault assumed control shortly thereafter, not by founding but by outmanoeuvring the initial family owners. The company operates through ~60 subsidiaries managing 75 luxury brands across six branches. Its $500B valuation in April 2023 reflects disciplined acquisition—Boussac Saint-Frères (1984), Tiffany & Co. (2021)—and structural decentralisation that preserves brand identity while centralising financial control. LVMH does not invent luxury; it acquires, integrates, and governs it.
Michelin is a tyre company whose early dominance came from patenting and proving mechanical improvements — detachable, automobile, run-flat, radial, asymmetric — all tested in races or real-world conditions. It monetised mobility itself: first via tyres, then via the Michelin Guide, which existed solely to grow the car-tourism market and thus tyre sales. No evidence supports claims about culture, legacy, or unmeasured influence — only documented innovations, patents, and commercial pivots.

Rolex is a vertically integrated Swiss luxury watchmaker founded in London in 1905, whose early authority came from technical validation (Kew Observatory, 1914), wartime policy (RAF replacement), and structural control (foundation ownership since 1960). It claimed the first waterproof wristwatch case in 1926 — but Depollier patented a functionally identical design eight years earlier. No financial data appears in the sources.
Shein is a global fast fashion e-commerce platform founded in 2008 in Nanjing, China, and currently headquartered in Singapore. It began as a drop shipping-style operation sourcing from Guangzhou’s wholesale market, then transformed into a fully integrated retailer starting in 2012. Its product range spans women’s, men’s, and children’s apparel plus accessories and cosmetics, targeting Europe, the Americas, Australia, and the Middle East. Its growth has been tied to popularity among younger Millennials and older Gen Z consumers, enabled by low pricing and rapid trend response.

SoftBank Group is a Japanese investment holding company founded in 1981 as a software distributor, restructured as a holding company in 1999, and renamed SoftBank Group Corp in 2015. It focuses exclusively on investment management — primarily in technology companies across diverse markets. Its Vision Fund, launched in 2017 with $100 billion, was the world’s largest technology-focused venture capital fund at inception. SoftBank went public in 1994 with a $3 billion valuation. In 2016, it announced a $50 billion U.S. investment commitment targeting 50,000 jobs. From 2023, it shifted strategy toward AI infrastructure and semiconductor-related investments — a direction confirmed by Masayoshi Son’s January 2025 chairmanship of Stargate LLC.
Uniqlo is a case study in industrialised apparel: no hype, no heritage theatre, no seasonal spectacle — just a tightly coupled system for making, moving, and refining simple clothes at scale.
Universal Pictures was a business architecture designed to extract value from every layer of film — from performer contracts to theatre leases — using legal, spatial, and branding levers. Its success was tactical, not mythic.
Valve is a rare case where platform ownership fully decouples creative output from financial sustainability. Its flat structure is not a virtue—it is a tax the company pays for avoiding managerial overhead, made bearable only by Steam’s dominance. It does not scale. It does not replicate. It survives.
Warner Bros. is a trademarked asset that has outlived every corporate owner since its 1923 founding — surviving mergers, spin-offs, and acquisitions not through creative consistency, but because its library and IP rights remain licensable across shifting distribution models.
WeChat is a product of Tencent’s Guangzhou lab, launched in 2011 by Allen Zhang. It bundles messaging, social, and payments — and dominates China not because it is open or interoperable, but because it is closed, complete, and compliant.
Zara is a case study in operational rigour, not branding or tech. Its advantage is physical: proximity, control, and repetition — not algorithms or virality.

Gap Inc. was a logistics play disguised as youth culture — and its early success came from solving stockouts, not selling identity.
Marks & Spencer began as a £5 stall with a slogan — not a brand, not a department store, but a refusal to haggle.
Louis Vuitton is a French luxury fashion house founded in 1854. It merged into LVMH in 1987. It earns revenue from globally distributed, monogrammed luxury goods sold via 460+ owned stores. Its valuation rose from US$25.9bn (2012) to US$28.4bn (2013), alongside US$9.4bn revenue that year. It is repeatedly named the world’s most valuable luxury brand—but never discloses margins, unit costs, or subsidiary-level financials. Legal actions, WWII collaboration, model mistreatment, UNESCO site damage, and cultural appropriation claims are documented—but none appear in its financial reporting or governance disclosures.
ICICI Bank’s 1994 formation under K.V. Kamath was not the birth of a startup but the strategic repackaging of a state-backed institution into a private, technology-enabled, acquisitive financial group — with real execution in regulation-constrained conditions.
Activision’s founding was a contractual rupture, not a technological leap. It turned programmer identity and shelf presence into revenue — and proved third-party publishing could exist only after winning in court.
Adobe’s founding story is not about creative tools—it is about control of a foundational layer: the language that told printers what to print. That decision, made in a garage in 1982, let Adobe license across hardware and software ecosystems before ever selling to end users. Everything else came later—and is absent from the verified record.
Airbnb’s origin is materially humble: a rent crisis, two roommates, an air mattress, and Pop-Tarts. Its business model — brokerage via commission — was clear from the start, but its execution required repeated, costly pivots: cereal sales, crashed websites, YC’s $20k for 6%, and Sequoia’s $585k only after that. Its European expansion relied on acquiring Accoleo — not organic growth or superior product. The story Airbnb tells about itself is one of design-led innovation; the record shows it was one of opportunistic adaptation, funded by hustle and validated by investors only after infrastructure and evidence accumulated.
Baidu is a foundational case of algorithm-first platform building: its 1996 RankDex technology became its 2000 product, its 2001 ad model predated Google’s, and its 2003 content-search innovations were tailored to Chinese media structures. It achieved national dominance and NASDAQ listing — but never decoupled from search advertising, even as it invested in Apollo, Xiaodu, and AI stacks.
Beyond Meat is a plant-based meat alternative producer founded in 2009 by Ethan Brown to mitigate climate change. It licensed meatless protein technology from University of Missouri professors, launched its first product in 2012, its signature Beyond Burger in 2016, and became the first publicly traded company in its category in 2019. It announced layoffs of 19% of staff in October 2022 due to revenue declines and additional layoffs in November 2023 after a 9% sales decline.
Epic Games is a vertically integrated software and entertainment company whose business model relies on cross-subsidising its store and engine through a hit game. Its self-portrait as a developer ally conflicts with its contractual terms and revenue structure. The gap between that story and its mechanics is where the real lesson lies.
Facebook is an American social networking service founded in 2004 by Mark Zuckerberg and four Harvard College roommates; initially limited to Harvard students, it expanded to other North American universities and then globally to users aged 13+ (14+ in select regions) starting in 2006; as of December 2023 it had ~3.07 billion monthly active users and as of July 2025 ranked third globally by web traffic, with 23% originating from the US; it was the most downloaded mobile app of the 2010s and is accessible across internet-connected devices including PCs, tablets, and smartphones; its headquarters are in Palo Alto, California.
Instagram is a photo- and short-video-sharing social networking service launched in October 2010 by Kevin Systrom and Mike Krieger in San Francisco, after pivoting from a check-in app called Burbn.
Netflix is a case study in operational iteration — not technological invention. Its value lies in how it structured incentives, removed friction, and scaled infrastructure — not in what it claimed to be.
Salesforce is a case study in narrative-first SaaS scaling: built on a slogan, funded by subscription growth, extended by platform logic, and recalibrated by AI-driven cost shifts—not disruption, but disciplined iteration.

Twitter, Inc. was a social media company founded in March 2006 in San Francisco, spun off from Obvious Corporation (formerly Odeo), operating the Twitter platform and other services. It prioritised uptime and design principles over revenue until after 2008, grew to over 100 million users by 2012 and 330 million monthly active users by 2019, went public in November 2013, and was acquired by Elon Musk for $44 billion in April 2022 before merging into X Corp. in April 2023. No source states its revenue model, unit economics, or profitability.
Uber is a platform whose early growth relied on regulatory noncompliance, strategic rebranding, and reactive imitation — not technical invention or user-first design. Its financial mechanics are transparent: high take rates on massive transaction volume. Its story is not about disruption, but about exploiting gaps between law and enforcement.
WhatsApp is not a messaging app with a business model—it is a telecom identity layer wrapped in an app. Its value lies in what it replaced (SMS, MMS, local calling) and what it enabled (cross-border, zero-cost, asynchronous communication at planetary scale). Its acquisition by Facebook in 2014 for $19.3 billion confirmed its strategic value as infrastructure—not as a consumer product.
Xiaomi is a Beijing-based Chinese multinational founded in 2010 by Lei Jun and six others. It operates in consumer electronics, software, and electric vehicles. It launched its first smartphone in August 2011 and entered the smart electric vehicle industry in March 2021.
YouTube was a technical execution of a simple idea—upload and share video—with no monetisation strategy. Its founders leveraged prior wealth, network access, and timing to achieve rapid scale, then sold to Google before proving sustainability. The gap between usage and revenue was never closed—it was exited.

Nestlé is a case study in how industrial food companies scale not through singular genius, but through technical borrowing, wartime procurement, and post-war recalibration. Henri Nestlé invented a product, then exited. The company that bears his name grew via merger, contract, and consolidation — not continuity.
TSMC is the world’s largest and most advanced contract chipmaker — a state-enabled, capital-intensive factory system that executes Moore’s Law with industrial rigour. Its dominance comes not from vision or branding, but from delivering real chips, on schedule, at scale.
Goldman Sachs is a multinational investment bank and financial services company founded in 1869 and headquartered in New York City. It offers investment banking (advisory for mergers and acquisitions and restructuring), securities underwriting, prime brokerage, asset management, and wealth management. It acts as a market maker, operates private-equity and hedge funds, structures complex and tailor-made financial products, owns Goldman Sachs Bank USA (a direct bank), and trades both on behalf of clients and for its own account.
JPMorgan Chase is a vertically integrated financial monopoly whose scale rests on documented historical control — from industrial consolidation to slave-backed credit — not disruption or invention.

Morgan Stanley is a financial institution whose origin story is legally precise, but whose current identity is structurally ambiguous. It began as a Glass–Steagall-mandated spin-off — not a startup, not a rebellion, but a regulatory necessity. Its early market share proves execution mattered more than ideology. Its 1997 merger erased the line between investment banking and mass-market finance — yet the firm still trades on the prestige of 1935. That dissonance is the real story.
ByteDance is an AI-driven content platform company built on internal competition, strategic acquisition, and rapid global scaling — not organic product leadership or transparent monetisation.

PayPal is a case study in opportunistic infrastructure: built on a dead-end tech idea, it succeeded only after latching onto a specific, messy, high-volume use case — eBay auctions — and charging for reliability in a trust vacuum.

Tencent is a Chinese multinational technology conglomerate and holding company, co-founded in 1998 in Shenzhen. It is one of the highest-grossing multimedia companies globally by revenue and the world’s largest company in the video game industry by equity investments. Its first product, OICQ, launched in February 1999 and reached over one million registered users by year-end 1999. In 2000, Tencent secured $2.2 million in venture capital funding and adapted its platform for mobile messaging — generating 80% of revenue via telecom operator fee-sharing deals. After losing a U.S. arbitration case over domain names, it renamed OICQ to QQ in December 2000. By 2004, it held 74% of China’s instant messaging market and listed on the Hong Kong Stock Exchange.
Adidas is a German multinational athletic apparel and footwear corporation headquartered in Herzogenaurach. It was founded by Adolf Dassler in 1948, following the breakup of the Dassler Brothers Shoe Factory. Adidas makes money selling athletic apparel and footwear. Its revenue in 2024 was €23 billion. It operated 17 factories and generated one billion Deutschmarks in annual sales by 1978. Dassler’s focus on functional footwear innovation worked: he redesigned spiked running shoes, introduced interchangeable screw-in studs for football boots, and secured high-visibility athlete adoption (Jesse Owens, 1936). The three-stripe logo became a registered trademark in 1949 and a scalable visual identifier. The 1924 Dassler Brothers Shoe Factory was a shared venture — not Adidas — and dissolved in 1948 amid a rift. Post-war material shortages forced rapid reconversion from weapons to shoes — yet Adidas hit one billion Deutschmarks in sales by 1978. Adidas shows how a narrow technical advantage — screw-in studs, canvas-rubber spikes, the three-stripe trademark — can anchor decades of manufacturing expansion when paired with strict control over production, branding, and distribution channels. Yes — as a case study in how technical footwear innovation, trademark discipline, and athlete-led validation built industrial scale in post-war Europe — but only if you treat its origin story as a business reconstitution, not a founding myth.

Intel is a foundational semiconductor company whose business model pivoted from memory to microprocessors—and whose lasting leverage came from controlling the x86 instruction set, not just fabrication.

The Coca-Cola Company was founded in 1892 by Asa Griggs Candler in Atlanta after he purchased the formula from John Stith Pemberton in 1888. It generated revenue by manufacturing and selling syrup to soda fountains, then licensing bottling rights for $1 per territory — a contract that transferred capital and operational risk to third parties while preserving brand control. By 1895 it achieved nationwide US distribution; exports began in 1899 (Cuba) and 1901 (Europe). Candler trademarked the brand and paid dividends in 1893, proving early financial viability. The model worked because it scaled without infrastructure — but failed to ensure product consistency across bottlers. This is a masterclass in leveraging intellectual property through contractual design, not product innovation.
Costco is a membership-first retail system whose financial mechanics are transparent: fees fund operations, low margins enforce discipline, and private label locks in loyalty. It works where density, income, and culture permit bulk buying — and fails where they don’t. No hype. No exceptions.
General Motors was founded in 1908 as a holding company, not a manufacturer. It made money by acquiring brands and suppliers, issuing stock to secure alignment, and franchising dealerships — all before building a single integrated factory. Its early success came from financial engineering, not product innovation. Durant was removed twice — in 1910 and 1920 — exposing the fragility of growth without operational discipline. Sloan’s later reforms codified what Durant had improvised: a scalable, tiered brand architecture. The real innovation was not the car, but the corporation.

IKEA is a case study in disciplined execution — not innovation. Its success rests on replicating a single operating model globally, enforced by geographic and legal separation between brand and retail. Nothing in the source material supports claims about culture, sustainability, or digital transformation — only cost, control, and structure.

McDonald's is not a restaurant chain but a replication system — built on enforceable standardisation and deliberately constrained franchising. Its economics rely on control, not volume, and its origin story is a legal rebranding of a hostile acquisition.

Nintendo’s origin is a case study in operational discipline over narrative ambition. It succeeded by controlling production hardware, exploiting regulatory shifts, and locking in high-frequency buyers — not by inventing games or chasing culture.
Nvidia is a fabless semiconductor company whose business model depends on external demand shocks, not internal cost control or manufacturing leverage.
Samsung’s origin contradicts its current identity: it was a trading and transport firm, not a tech innovator. Its electronics entry was late, small-scale, and licence-dependent — a strategic pivot enabled by infrastructure, not invention.

Starbucks is the world’s largest coffeehouse chain. It was founded in 1971 in Seattle as a coffee bean wholesaler. Howard Schultz transformed it into a company-owned coffeehouse chain serving espresso-based drinks. As of November 2022, it operated 35,711 stores in 80 countries. It held an IPO on June 26, 1992, raising $271 million to double its store count. It credits its growth to rejecting domestic franchising and positioning stores as social hubs — driving the second wave of coffee culture.

TikTok is a Chinese-origin short-form video platform launched internationally by ByteDance in September 2017 as the overseas counterpart to Douyin. It uses AI-driven recommendation algorithms to connect creators with audiences. It surpassed two billion mobile downloads by April 2020. Its corporate entity, TikTok Ltd, is incorporated in the Cayman Islands and headquartered in Singapore and Los Angeles. Zhang Yiming founded ByteDance in 2012 and explicitly framed global expansion as essential because China accounts for only one-fifth of global internet users. ByteDance acquired Musical.ly for US$800 million in August 2018 and integrated it into TikTok.
Toyota’s founding was a licensed, capital-backed industrial pivot — not a startup story.

Walmart’s early success was mechanical, not magical. It used known levers — location, transport, procurement — with unusual discipline. Its story is not about disruption but about execution fidelity.
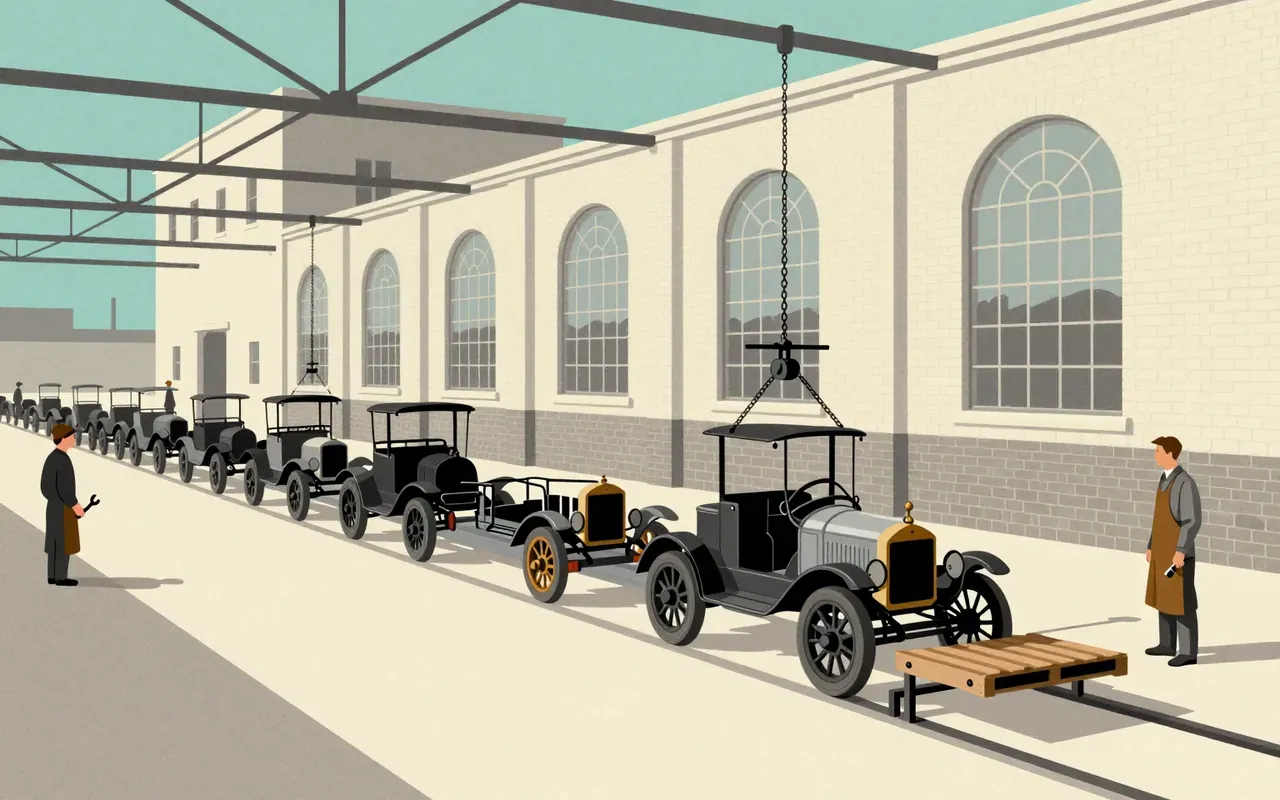
Ford Motor Company was not an idea about mobility—it was a financial and mechanical system for turning $28,000 into 15 million cars. Its power came from eliminating variability: in parts, in process, in price, and eventually in design. It succeeded by making everything repeatable—including authority.

Anthropic positions itself as a safety-first AI builder—but its business runs on proprietary models trained with legally contested data, sold under restrictive partnerships, and governed by self-declared public benefit terms that do not prevent mass-scale book scanning or billion-dollar copyright liability.
Microsoft’s founding was not about building the best software first — it was about controlling the terms of distribution before the market existed. Its early success came from timing, contractual foresight, and treating software as licensable intellectual property — not a service or craft. The company established the template for platform leverage in computing: own the interface, not the hardware.

Nike’s origin is a textbook case of a startup succeeding not by inventing a category, but by reengineering a supply chain — then iterating relentlessly on one functional detail: traction.

OpenAI is a public benefit corporation whose legal structure separates nominal mission stewardship (26% nonprofit ownership) from actual control and value capture. Its market impact is real—ChatGPT became the fifth-most-visited site globally—but its $852bn valuation reflects investor appetite for AI infrastructure access, not verified unit economics, revenue, or margin discipline. Microsoft’s $13bn investment funds development but does not constitute revenue. The gap between OpenAI’s self-description as a public benefit entity and its operational reality is structural—not incidental.
Patreon is not a creator empowerment tool — it is a monetisation layer that captures value at the point of transaction, enforces terms unilaterally, and scales through volume, not trust.
Reddit is a community platform whose founding mechanics—Lisp prototype, Swartz-led rewrite, rapid acquisition, deferred monetisation, and founder re-entry—reveal how infrastructure survives without a clear business model.
Shopify is a Canadian multinational cloud e-commerce management platform for retail point-of-sale systems, founded in 2006 by Tobias Lütke, Daniel Weinand, and Scott Lake. In 2024, it processed US$292.3 billion in transactions, with 5 million customers. Its software is praised for ease of use and reasonable fee structure, and it is described as the 'go-to e-commerce platform for startups'. Shopify went public in 2015 and uses a two-class voting structure that grants disproportionate voting control to Lütke despite his minority economic stake.
SpaceX is a government-contract-powered aerospace manufacturer whose reusable launch system succeeded where others failed — not because of vision alone, but because NASA paid for development, testing, and flight operations while Starlink created a parallel revenue stream. Its Mars and Starship ambitions remain outside this economic reality.
Stripe is infrastructure, not finance. It sells developer convenience — not banking services. Its $159bn valuation rests entirely on volume processed, not revenue disclosed, margins proven, or ownership of capital.
Tesla is not a software or AI company—it is a vertically integrated hardware manufacturer whose valuation rests on future scale, not current unit economics. Its founders were Eberhard and Tarpenning. Musk joined in 2004, led funding, took control, and shaped its public narrative. It sells cars, batteries, and solar—but publishes no per-product margin data. Its market dominance is financial, not operational.
Sony’s early business model was hardware-first, export-first, and name-first — built on tangible, shipable, patentable devices that redefined category boundaries in foreign markets.