businessbriefs
10:08in productionCh. 1 · Founding by gathering/ 10:08 · ceiling 15 min
Finance

Toronto Stock Exchange

1861

A 163-year-old exchange that survives not by reinvention, but by absorbing change — then claiming it as legacy.

The Toronto Stock Exchange is a long-standing equity infrastructure — not a startup, not a platform, not a disruptor. Its history is one of incremental formalisation: from informal broker gathering (1861), to statutory incorporation (1878), to automation rollout (1977), to corporate absorption (TMX Group). No revenue model, no cost structure, no customer definition appears in the source — only facts of jurisdiction, location, ownership, and ranking. Its endurance is real. Its agency — as presented — is not.

Chapters & takeaways5
  1. 1:03
    Founding by gathering

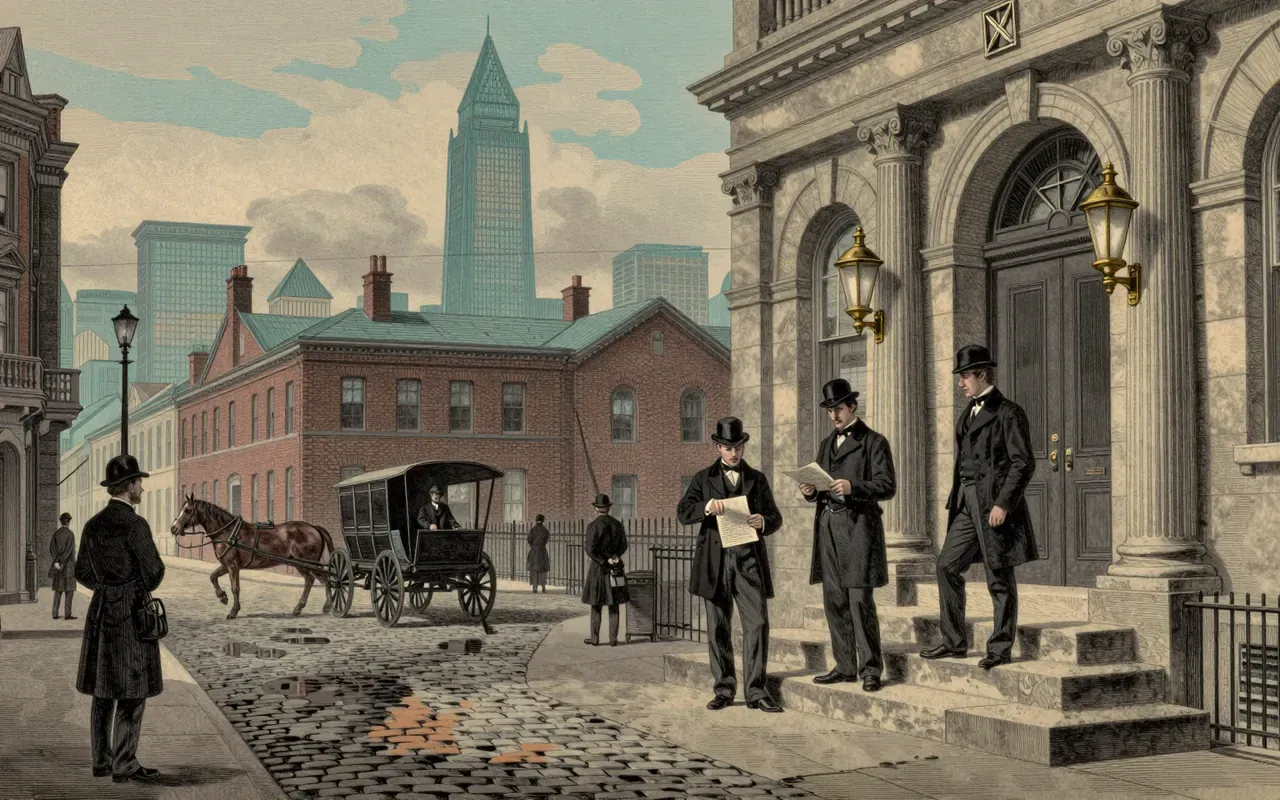
    It began not with a charter, but with a meeting: 24 brokers at Masonic Hall on October 25, 1861.

  2. 2:04
    Incorporated, not invented

    Incorporation came 17 years later — a legal consolidation, not a launch.

  3. 3:17
    Scale without strategy

    Its size ranking — third in North America by 1936, 10th globally today — is structural, not strategic.

  4. 4:50
    Automation with limits

    It trades senior equities as a TMX subsidiary, using automated systems like CATS since 1977 — but only for less liquid stocks.

  5. 6:00
    Fixed address, shifting ownership

    Its location — EY Tower in Toronto’s Financial District — anchors it physically, even as ownership shifts.

Worth your time?

Yes. Study the whole thing.

3.5/ 5
What works
  • maintains scale
  • anchors senior equity trading in Canada
  • documents clear lineage from 1861 to present
What does not
  • make money in ways described
  • operate independently
  • define its own market role
Study it if
  • policymakers tracking national financial infrastructure
  • historians verifying institutional continuity
  • investors assessing unclaimed claims
Skip it if
  • founders seeking playbooks
  • traders evaluating liquidity mechanics
  • analysts needing financials
The written brief1 min read

What the company or idea is

The Toronto Stock Exchange is a stock exchange headquartered in Toronto, Ontario, Canada, founded in 1861 by 24 brokers, incorporated in 1878, and now the senior-equities trading arm of TMX Group.

How it actually makes money

The TSX makes money by charging fees for listing securities, trading execution, market data distribution, and technology services — but the source material does not specify revenue streams, pricing, margins, or who pays those fees.

What works

It maintains scale: it is the 10th largest exchange globally and third largest in North America by market capitalization — a status achieved by 1936 and sustained per the source.

What does not

It does not operate as an independent entity. It is a wholly owned subsidiary of TMX Group, with no operational or financial autonomy described in the material.

What to take from it

Its longevity reflects institutional continuity, not innovation: its major milestones — incorporation (1878), CATS (1977), monopoly on senior equities (1999) — are administrative or technological upgrades, not market creations.

Is it worth your time

Yes — if you need to understand how a national equity infrastructure evolves without relying on self-reported narratives or financial claims absent from the record.

Same desk · Finance4 of 56
9:00
Euronext2000Euronext is a vertically integrated bourse operator that monetises access to fragmented European capital markets. Its value lies in jurisdictional reach—not technical novelty or market-making power. The 2000 merger created a structure; the 2014 spin-off from ICE defined its current ownership and strategic autonomy. Its dominance in debt and funds listings reflects regulatory harmonisation more than competitive advantage.
10:12
Singapore Exchange1999Singapore Exchange is a vertically integrated national infrastructure operator, formed by statutory consolidation in 1999. It monetises control over the full financial market value chain — listing, trading, clearing, settlement, depository and data — across equities, fixed income, currencies and commodities. Its successes in OTC clearing and iron ore swaps flowed directly from that control; its failure with JADE exposed its dependence on unilateral authority, not collaboration. It is not a technology innovator or market maker — it is a regulator-enabled gatekeeper.
9:56
Cboe Global Markets1973Cboe Global Markets is a vertically integrated exchange operator whose business rests on three geographically and structurally distinct markets — U.S. options, U.S. equities, and European equities — all anchored by a 1973 innovation. Its open outcry floor contradicts its electronic dominance. Its growth came not from product invention after 1973, but from acquisition and rebranding. It is a case study in infrastructure longevity, not disruption.
11:44
TMX Group2007TMX Group is a vertically integrated Canadian market infrastructure operator that owns and runs competing exchanges, clearing houses, data services, and brokerage arms — but operates them as separate revenue streams rather than a coordinated system.
Up next in Business

Tronox

2005 · 10:56

A spin-off designed to dump toxic debt — not disrupt an industry.

10:56