JFE Steel
Second in Japan, minor everywhere else: JFE Steel’s global footprint is equity, not control.

John Deere is not a tech company. It is a manufacturer whose first product solved a tactile, geographic problem — soil adhesion — with a repeatable material fix. Its growth followed physical logic: water power, then scale, then diversification. Financial services are noted but undated. Nothing in the sources supports claims about digital transformation, autonomy, or data-driven farming.

Johnson & Johnson began as a vertically integrated supplier of standardised, sterile medical consumables — selling trust, training, and readiness, not cures.

KKR is a foundational leveraged buyout firm whose early success relied on regulatory change, not market demand — and whose most famous deal was unprofitable. Its current scale reflects diversification beyond private equity, not enduring deal-making superiority.
KLM was not a private venture but a state-backed aviation instrument. Its longevity stems from institutional alignment — not market innovation.


Lamborghini is a case study in disciplined positioning: a luxury carmaker built on agricultural engineering, anchored in one town, defined by one cultural metaphor, and repeatedly tested — and sometimes broken — by global economic forces.
Lukoil is a Russian multinational energy corporation headquartered in Moscow, formed in 1991 by merger of three state-run western Siberian oil enterprises: Langepasneftegaz, Urayneftegaz, and Kogalymneftegaz.
Mack Trucks is a vertically narrow, geographically mobile, and corporately subordinated industrial brand — sustained not by innovation or scale, but by consistent execution in a defined vehicle class and enduring customer trust in its vocational durability.
Merck & Co. is a multinational pharmaceutical company founded in 1891 as the American affiliate of the German Merck Group, made independent in 1919 after U.S. government expropriation and resale. Its early growth came from strategic mergers — not organic R&D — and its landmark streptomycin breakthrough relied on external academic research funded by the company. Under George W. Merck’s presidency (1925–1950), it developed synthetic vitamins, sulfas, antibiotics, and hormones, while simultaneously leading the U.S. biological weapons programme. The gap between its self-presentation as a scientific pioneer and its actual mechanics — acquisition, outsourcing, and state-aligned research — is the core of its business story.
Moody's Ratings is the credit ratings division of Moody's Corporation, rebranded from Moody's Investors Service in March 2024. It provides international financial research on bonds issued by commercial and government entities, operates as one of the Big Three credit rating agencies, uses a standardized ratings scale measuring expected investor loss in default, assigns ratings from Aaa (highest) to C (lowest), and was founded by John Moody in 1909 to produce manuals of statistics related to stocks, bonds, and bond ratings.

Nasdaq is not a disruptor — it is the incumbent infrastructure operator. Its value lies in ownership of exchange platforms, data feeds, and listing rules — not in technological novelty, which has long since been replicated. It works where liquidity and branding converge: tech IPOs, real-time data sales, and cross-border access. It falls short as a neutral arbiter: its incentives align with listed companies and high-frequency traders, not retail investors or public market integrity. The gap between its self-presentation as a ‘market enabler’ and its actual function as a toll collector is wide — and profitable.
Natura built a global cosmetics business using direct sales—not digital platforms—and anchored its identity in ethical sourcing and animal-testing bans. It listed on Brazil’s highest-governance stock exchange tier in 2004. But none of its stated commitments include third-party verification, cost impact, or enforcement mechanisms. Its scale—6.6 million consultants in 2018—is real. Its ethics are aspirational.

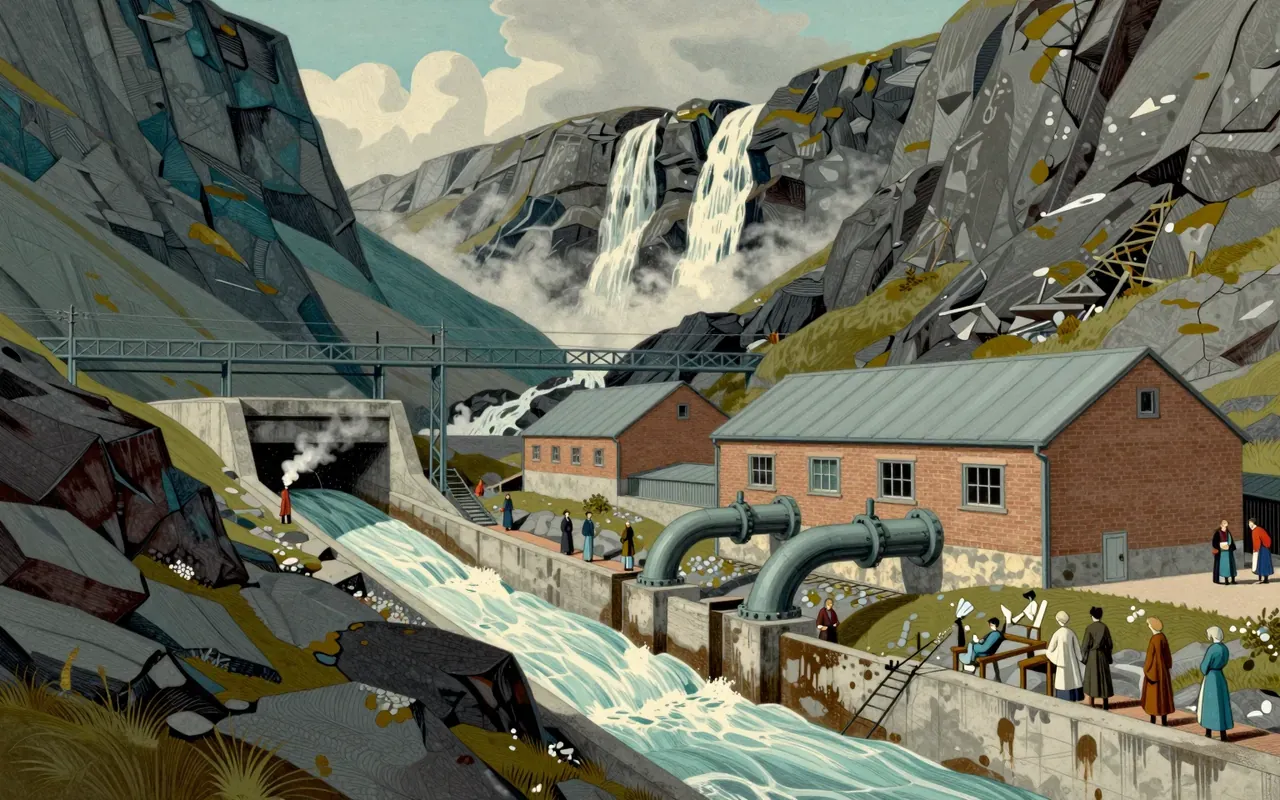
Norsk Hydro began as a single-purpose vehicle for Birkeland’s nitrogen-fixing arc — a physics experiment turned factory. Its early dominance came not from IP or management, but from locking in Norway’s hydropower geography. It survived obsolescence not through reinvention, but by ceding chemical control to IG Farben. Its WWII role — sole European heavy water producer — was accidental infrastructure reuse. Its current aluminium and renewables business shares no technology with its origin, only its dams, debt, and place.
Novatek is a state-tolerated gas monopoly-in-waiting: dominant domestically, absent internationally, priced by regulation not competition.

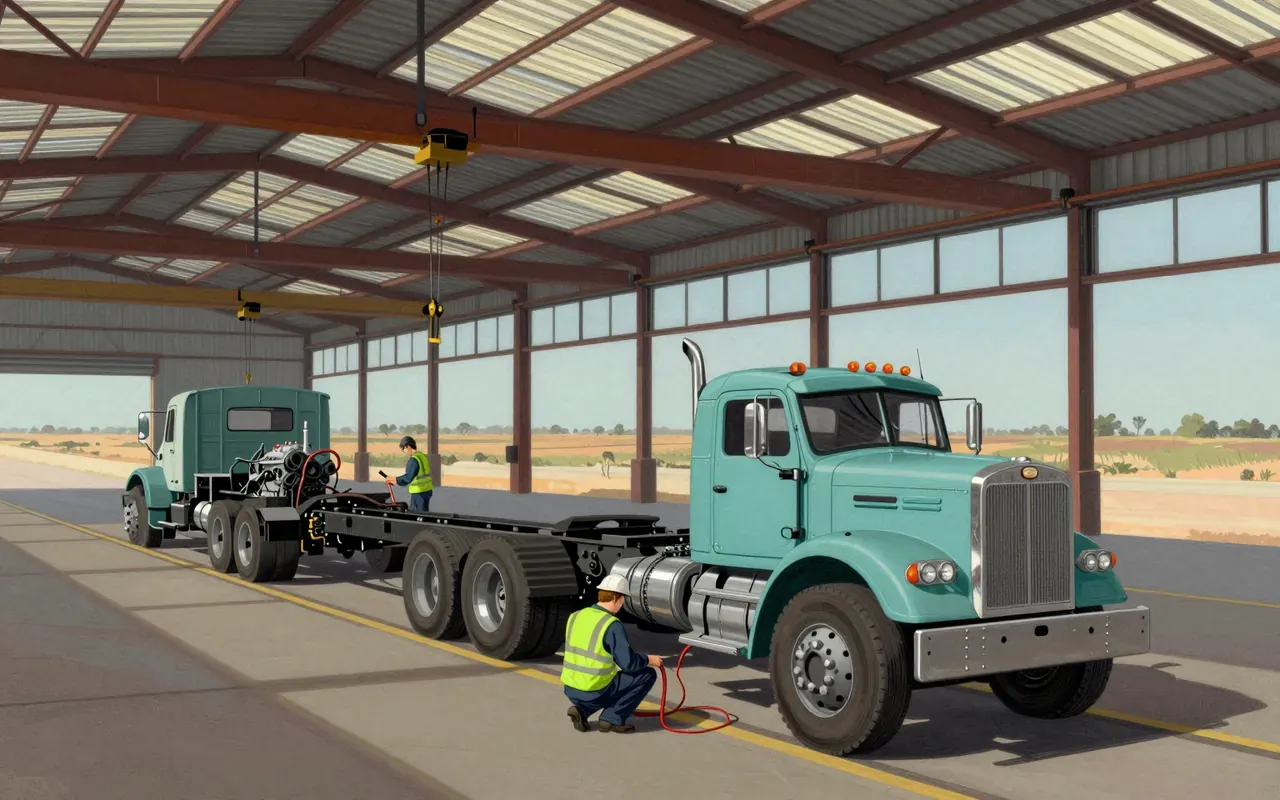
Peterbilt is a case study in acquisition-led industrial continuity: a timber operator bought a defunct truck maker to solve local hauling problems, engineered narrowly effective solutions, scaled only when external demand (military) appeared, and exited when land value exceeded truck value. Its legacy lies in execution, not vision.
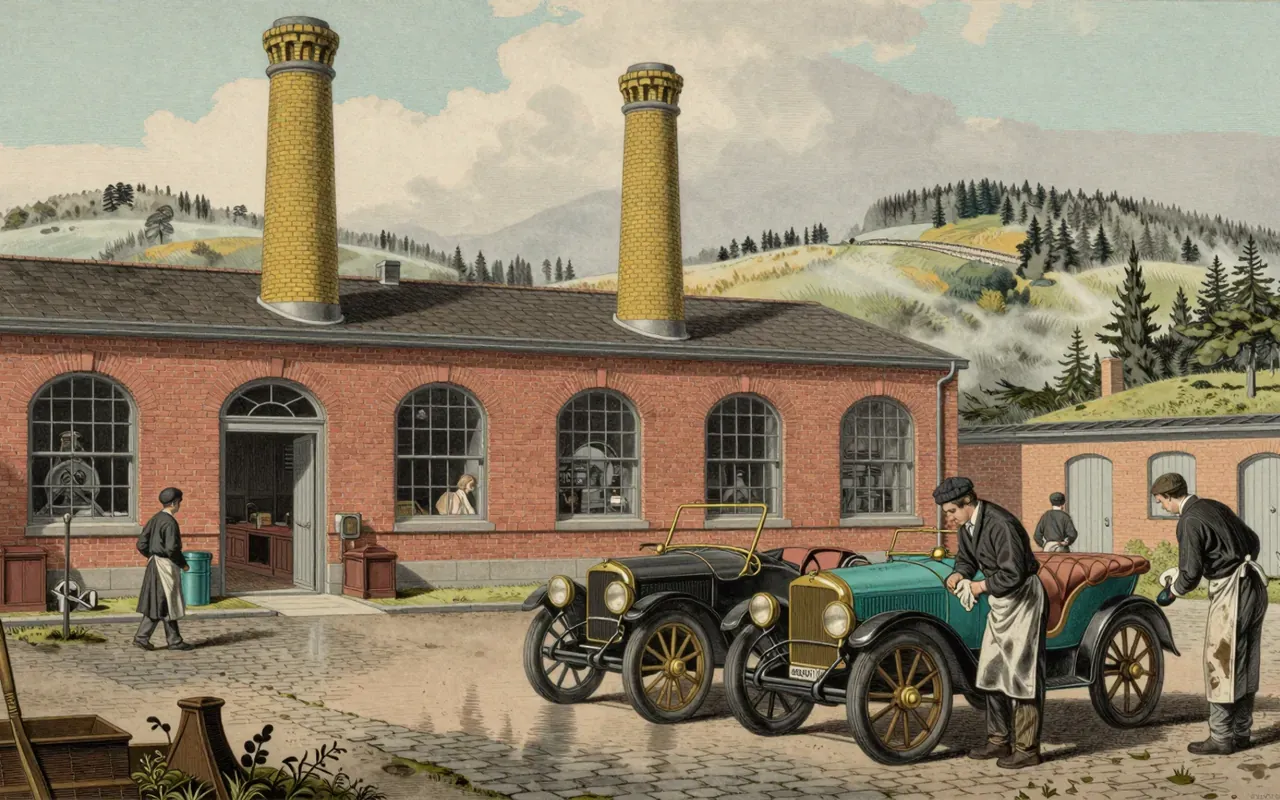
Peugeot is the oldest car company in the world — but only because it formalised its automobile division in 1896, 86 years after its founding as a steel foundry. Its success came not from breakthrough invention, but from disciplined technology adoption, rapid iteration, and industrial scaling.

Pfizer’s origin story is not about curing disease — it is about solving chemical supply problems with fermentation. Its therapeutic dominance came decades after it mastered industrial microbiology under pressure.
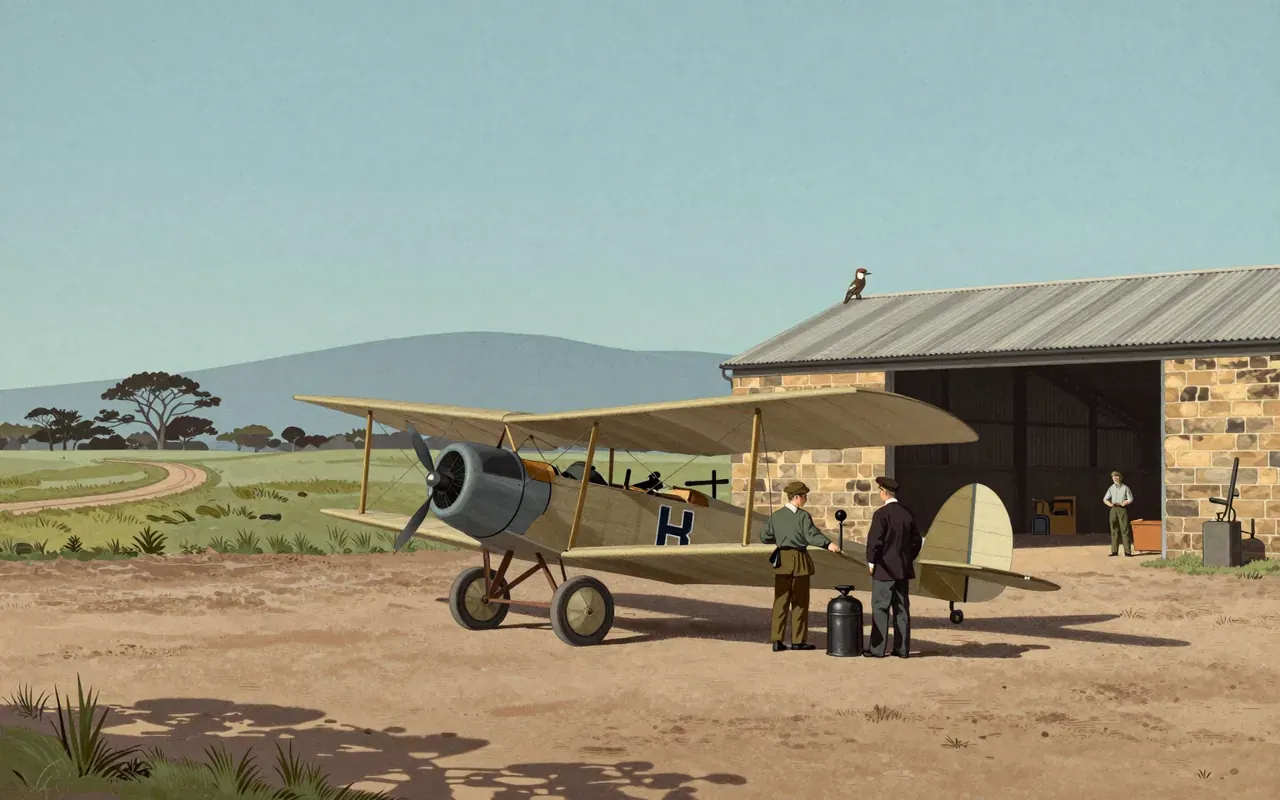
Qantas was founded as a government-enabled airmail service — not a passenger airline — and its early survival depended entirely on public infrastructure needs, not market demand.
Regeneron is a biotech firm whose core innovation — the receptor trap — emerged from neurobiology, not pharmacology. It monetises that science via high-value partnerships and outsized government contracts, not broad platform dominance. Its success depends less on internal scale than on strategic leverage of public R&D funding.
Renault’s early business was built on three concrete moves: selling before incorporation, vertically integrating engine production, and dominating municipal taxi supply — not on vision, branding, or disruption.

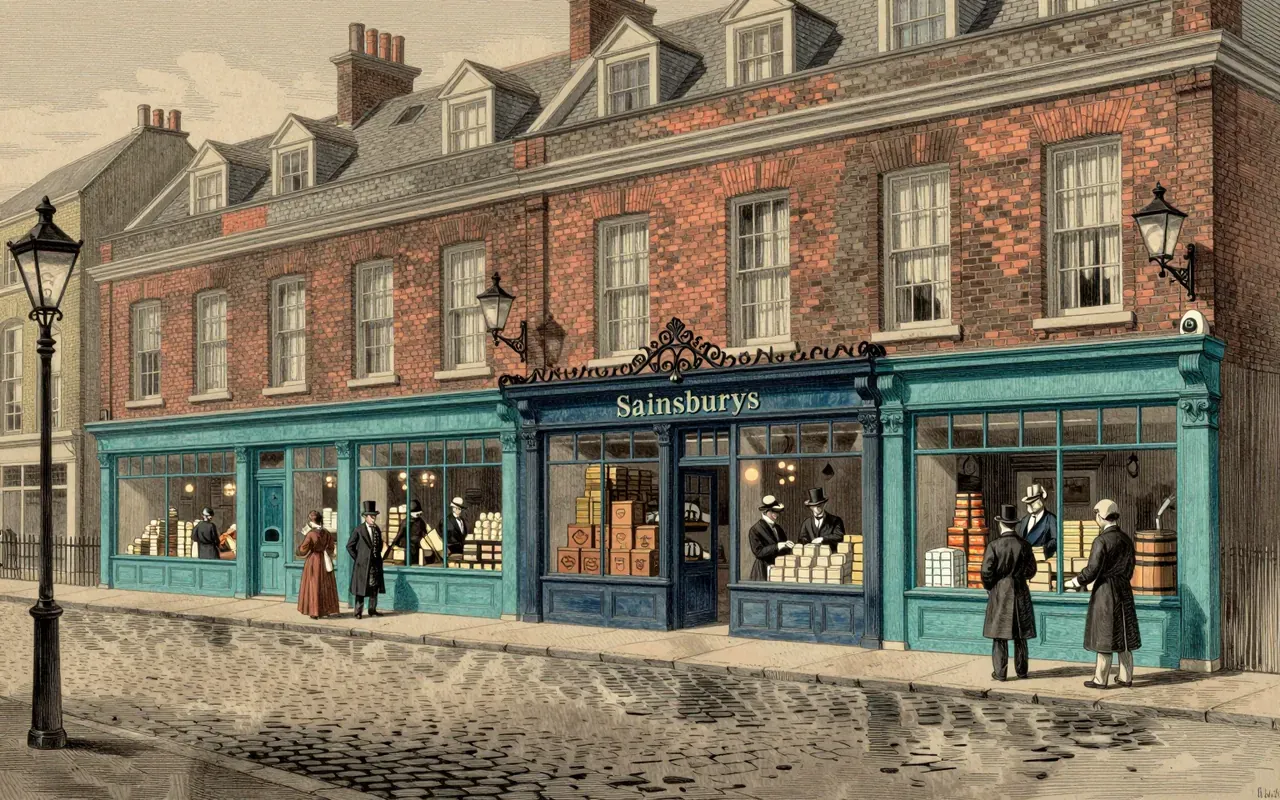
Sainsbury’s is the second-largest UK supermarket chain. It was the largest UK grocery retailer for most of the 20th century. It was founded in 1869 as a partnership by John James Sainsbury and Mary Ann Sainsbury at 173 Drury Lane in London. It began selling fresh foods and later expanded into packaged groceries. Its founding philosophy was 'Quality perfect, prices lower'. It used distinctive cast-iron signage, offered home delivery, and prioritised centrally located shops for better display and cooling before refrigeration existed. It grew to 128 stores by 1928 and remained a family business throughout Sainsbury’s lifetime. He served as Chairman and Governing Director from incorporation in 1922 until his death in 1928.
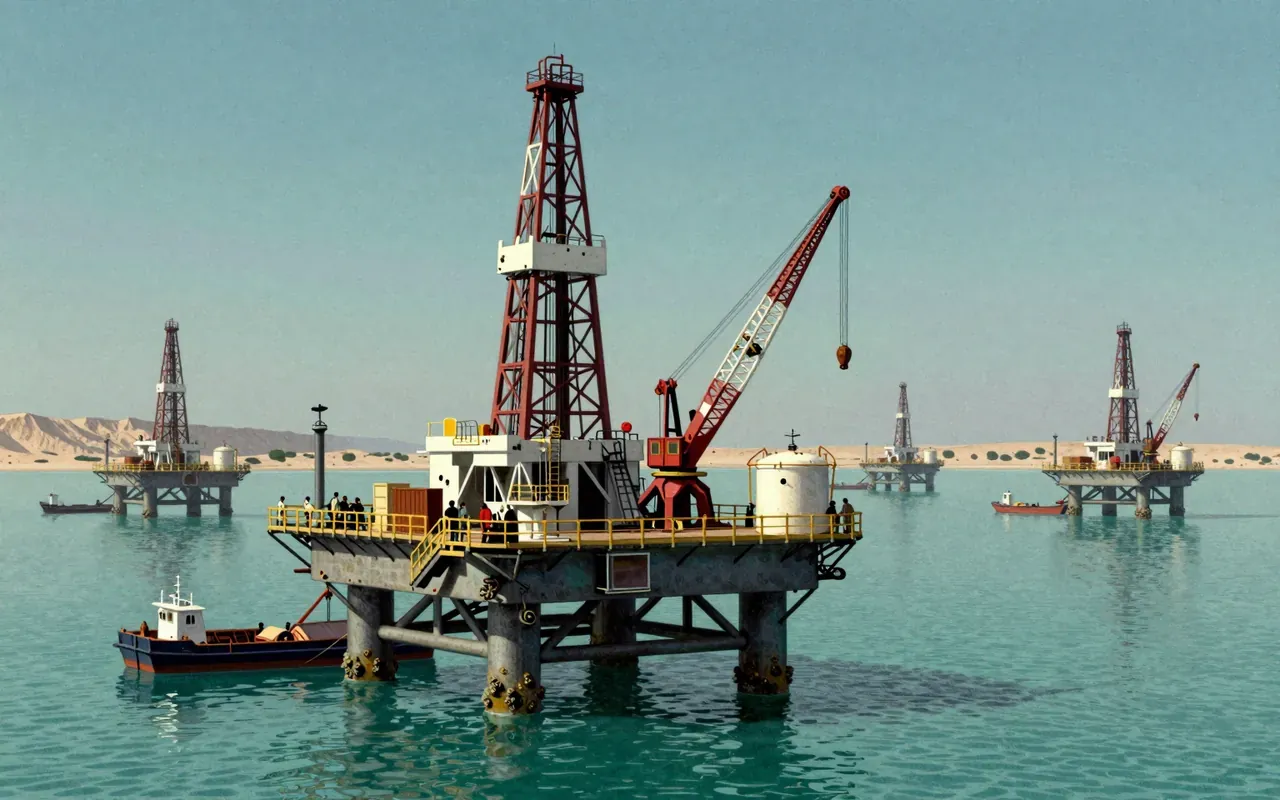
Saudi Aramco is the majority state-owned national oil company of Saudi Arabia. It holds the world's largest proven crude oil reserves and largest daily oil production. It operates the world's largest single hydrocarbon network, the Master Gas System. Its shares began trading on the Saudi Exchange on 11 December 2019, reaching a market capitalisation of about US$1.88 trillion. Its origins lie in a 1933 concession granted by Ibn Saud and executed by Chevron Corporation.



Soros Fund Management is a case study in regulatory adaptation: a firm that built its reputation on transparency of idea (macro thesis) and opacity of structure (family office), where the numbers remain impressive but uncheckable.

Tesco is a British multinational groceries and general merchandise retailer headquartered in Welwyn Garden City, England. It was founded in 1919 by Sir Jack Cohen in Hackney, London, beginning with a market stall selling war-surplus groceries. The Tesco brand emerged in 1924 from supplier initials and Cohen’s surname. The first dedicated shop opened in 1931 in Edgware. It was floated on the London Stock Exchange in 1947. It pioneered self-service (1948) and supermarket formats (1956). Cohen’s core business method was 'pile it high and sell it cheap' and the motivational internal motto 'YCDBSOYA'.



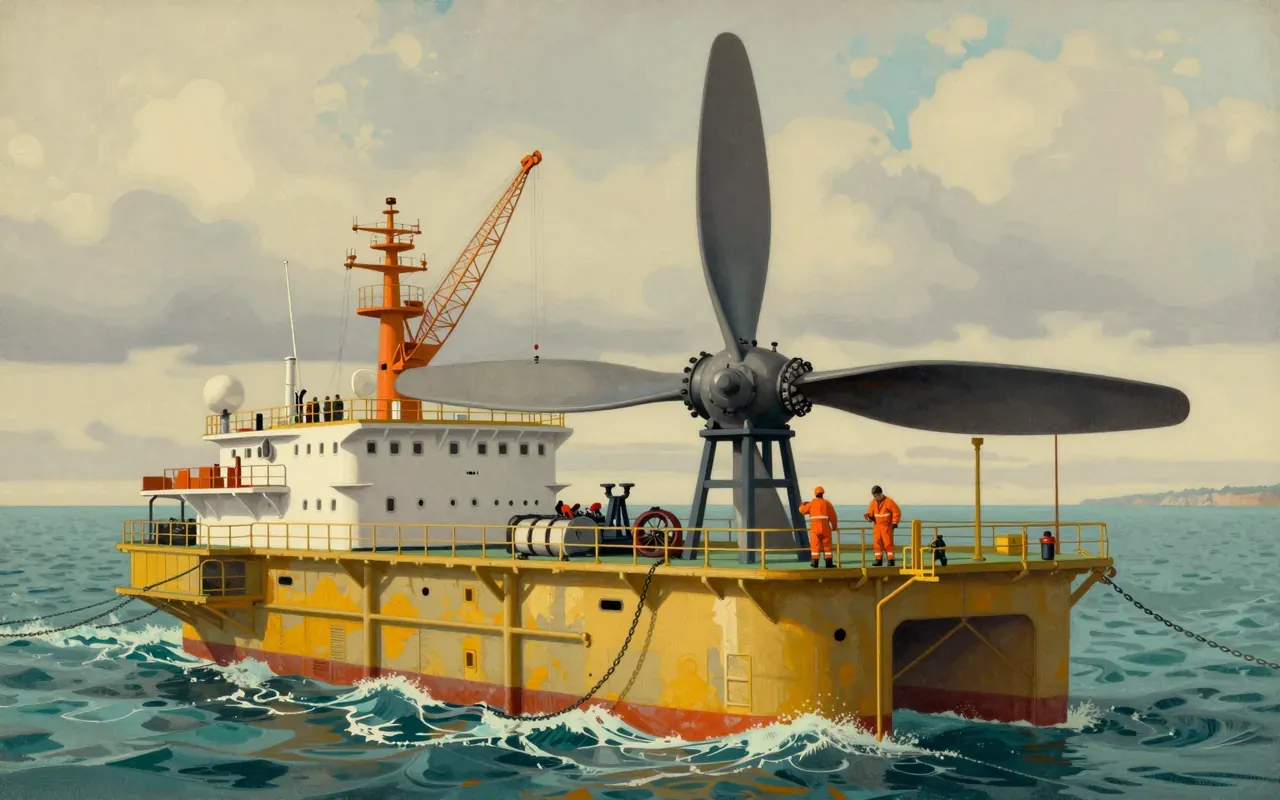
Vestas is a Danish wind turbine company founded in 1945, engaged in manufacturing, selling, installing, and servicing turbines globally; it details major operational milestones including global installations, R&D investment and patenting activity, strategic mergers, facility expansions and closures, and technical innovations such as stealth blades and floating turbines.
Volvo’s origin was not a corporate spin-off or investor-backed startup. It was a personal bet — financed by commissions saved in Paris, structured around a high-risk contract, validated by ten physical prototypes, and launched only after institutional rejection. Its early revenue came from trucks, not cars. Its founding story contradicts the myth of visionary consensus — it was a solo act of leverage, execution, and timing.


Activision’s founding was a contractual rupture, not a technological leap. It turned programmer identity and shelf presence into revenue — and proved third-party publishing could exist only after winning in court.
Adobe’s founding story is not about creative tools—it is about control of a foundational layer: the language that told printers what to print. That decision, made in a garage in 1982, let Adobe license across hardware and software ecosystems before ever selling to end users. Everything else came later—and is absent from the verified record.
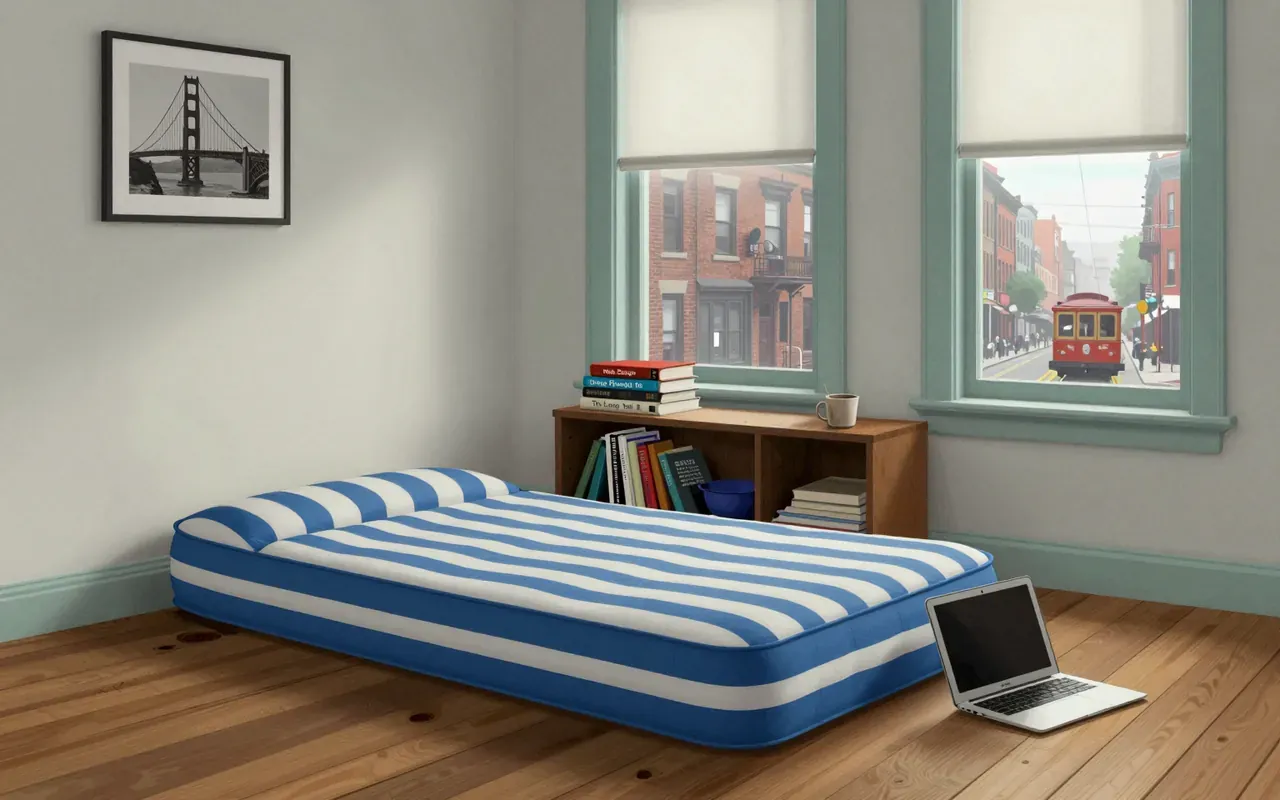
Airbnb’s origin is materially humble: a rent crisis, two roommates, an air mattress, and Pop-Tarts. Its business model — brokerage via commission — was clear from the start, but its execution required repeated, costly pivots: cereal sales, crashed websites, YC’s $20k for 6%, and Sequoia’s $585k only after that. Its European expansion relied on acquiring Accoleo — not organic growth or superior product. The story Airbnb tells about itself is one of design-led innovation; the record shows it was one of opportunistic adaptation, funded by hustle and validated by investors only after infrastructure and evidence accumulated.

Alibaba Group is a Chinese multinational technology company founded in 1999 in Hangzhou as a B2B e-commerce marketplace, now operating nine major subsidiaries including Taobao, Tmall, and Alibaba Cloud.
AMD is not a story of disruption — it is a story of licensed dependence, contested access, and court-mandated self-reliance in semiconductor design.