Sumner Redstone
He didn’t build media. He bought the keys to the vaults — and kept the doors locked.
Oracle Corporation is a multinational technology company founded in 1977 in Santa Clara, California, by Larry Ellison, Bob Miner, and Ed Oates. It sells database software (especially Oracle Database), enterprise applications (ERP, HCM, CX, SCM), and cloud infrastructure and hardware. By the mid-2000s, it had become the world's largest enterprise software vendor. Its foundational database design drew from Edgar F. Codd’s relational model paper. IBM’s delay in releasing a relational database for Unix and Windows allowed Oracle to dominate mid-range and microcomputer systems. Oracle acquired Sun Microsystems in 2010 after regulatory approval in the U.S. and EU.
Qantas was founded as a government-enabled airmail service — not a passenger airline — and its early survival depended entirely on public infrastructure needs, not market demand.

FEMSA is a Mexican multinational beverage and retail company headquartered in Monterrey, operating the largest independent Coca-Cola bottling group in the world and Mexico’s largest convenience store chain. It reports US$26.9 billion in revenue (2019), ranks fifth-largest company in Mexico, and operates across Latin America via bottling plants, convenience stores, drugstores, fuel stations, and third-party logistics—and in the US via jan-san distribution. Listed on the Mexican Stock Exchange since 1978 and NYSE ADRs since 1998. FEMSA is the holding company of Cuauhtémoc Moctezuma Brewery—the culmination of Eugenio Garza Sada’s industrial expansion from a single brewery into Grupo Valores Industriales, which included Fábricas de Monterrey (1920), HYLSA (1942), Empaques de Cartón Titán (1936), and multiple acquired breweries.
CJ Group is a South Korean chaebol that originated in 1953 as Samsung’s first manufacturing unit: a sugar and flour producer named CheilJedang. It established early industrial firsts — Korea’s first flour mill (1958), first sugar export to Okinawa (1962), and first branded sugar (Beksul, 1965). Its independence from Samsung followed a legal dispute among the Lee family — not market forces. Today it operates across food, bio, logistics, and entertainment, but the sources give no detail on how those businesses interconnect, profit, or compete. It is a case study in legacy infrastructure and familial fracture — not scalable strategy or innovation.
Blackstone is the largest alternative investment firm by AUM — $1.2 trillion as of September 2025, $1.3 trillion by Q1 2026 — built on a pivot from M&A advisory to merchant banking in 1987. Its founders lacked LBO experience but leveraged relationships to enter private equity, then scaled across asset classes using consistent mechanics: leverage, illiquidity, and fee-based capital aggregation. Its CEO held formal advisory access to the U.S. presidency, but that did not substitute for early fundraising credibility. The firm discloses neither performance nor risk metrics for its funds. Its growth reflects structural demand — not proprietary insight.
Beyond Meat is a plant-based meat alternative producer founded in 2009 by Ethan Brown to mitigate climate change. It licensed meatless protein technology from University of Missouri professors, launched its first product in 2012, its signature Beyond Burger in 2016, and became the first publicly traded company in its category in 2019. It announced layoffs of 19% of staff in October 2022 due to revenue declines and additional layoffs in November 2023 after a 9% sales decline.

EA is not a tech innovator or creative studio — it is a licensing and distribution engine that built cultural legitimacy on developer authorship, then discarded it for scale.
DiDi is a Chinese mobility technology company founded in 2012 by Cheng Wei in Beijing. It offers ride-hailing, taxi dispatch, bike sharing, vehicle leasing, food delivery, automobile services, and electric vehicle development. It merged with Kuaidi Dache in 2015 and acquired Uber China in 2016. It listed on the NYSE in June 2021 and was delisted in June 2022 after a $1.2 billion fine and app removal over data security concerns.

Husky Energy was a long-lived, vertically integrated petroleum company whose geographic reach and operational scope did not prevent its absorption into Cenovus Energy in 2021.
Renault’s early business was built on three concrete moves: selling before incorporation, vertically integrating engine production, and dominating municipal taxi supply — not on vision, branding, or disruption.

Siemens is a German multinational engineering company founded in 1847 as Telegraphen-Bauanstalt von Siemens & Halske in Berlin. It evolved through mergers into Siemens AG in 1966. It makes money from industrial automation, building automation, rail transport, and health technology. Its early model worked: rapid internationalisation via family agents, vertical integration from invention to installation, and patent-backed standard-setting. It does not sustain leadership in all its historical domains: it no longer builds x-ray tubes, electric trams, or passenger trains as standalone products. The gap between Siemens’s founding logic — applied electromagnetism deployed via owned workshops and international agents — and its present structure — a diversified, publicly listed conglomerate with AI and software at its core — reveals how industrial capability gets recoded as platform strategy over time. Yes — if you are studying how engineering firms scale infrastructure innovation into global revenue without pivoting to venture capital narratives.
Twitter, Inc. was a social media company founded in March 2006 in San Francisco, spun off from Obvious Corporation (formerly Odeo), operating the Twitter platform and other services. It prioritised uptime and design principles over revenue until after 2008, grew to over 100 million users by 2012 and 330 million monthly active users by 2019, went public in November 2013, and was acquired by Elon Musk for $44 billion in April 2022 before merging into X Corp. in April 2023. No source states its revenue model, unit economics, or profitability.

Volvo’s origin was not a corporate spin-off or investor-backed startup. It was a personal bet — financed by commissions saved in Paris, structured around a high-risk contract, validated by ten physical prototypes, and launched only after institutional rejection. Its early revenue came from trucks, not cars. Its founding story contradicts the myth of visionary consensus — it was a solo act of leverage, execution, and timing.
The RJR Nabisco deal was a $25 billion leveraged buyout led by KKR in 1988 — the largest in history at the time. KKR’s $109-per-share bid prevailed over RJR management’s $112 offer because it was guaranteed. The transaction relied on institutional equity co-investors and a hostile tender offer. Post-acquisition, KKR repaid debt through asset sales and restructuring. Over 2,000 workers lost their jobs, most taking 5.6 months to find new work, and 72% who were rehired earned less than half their previous incomes.
Rio Tinto is a British–Australian multinational mining company founded in 1873, headquartered in London and Melbourne, and operating globally as a major producer of copper, iron ore, aluminium, and lithium. Its history includes early dominance in Spanish copper production, strategic diversification after 1925, pivotal mergers — notably with Consolidated Zinc in 1962 and Alcan in 2007 — and extensive international expansion. The company is dual-listed on the London and Australian stock exchanges and has faced recurring criticism over environmental damage, corruption allegations (especially in Guinea), human rights concerns (e.g., Juukan Gorge), workplace culture issues, and legal challenges related to bribery and espionage. Its operational structure spans four product-based business units and numerous subsidiaries across six continents, with core assets concentrated in Australia and Canada.
Emirates is a state-owned UAE flag carrier founded in 1985 after Gulf Air reduced Dubai services. It operates over 3,600 weekly flights from Dubai International Airport’s Terminal 3, serves 150+ cities across six continents, and ranks third globally by passenger volume and second by freight volume. Its ownership lies with Dubai’s Investment Corporation of Dubai, and its cargo arm is Emirates SkyCargo. It is not part of any global airline alliance.

Carlyle is a textbook case of how a firm leverages geography and timing — not product innovation — to dominate a financial services niche. Its business model remains fee-dependent, opaque, and unremarkable in mechanics. Its value lies in its path, not its current structure.
Imperial Oil was founded in 1880 as a Canadian response to Standard Oil’s expansion — a deliberate replication of Rockefeller’s integrated model. It quickly controlled 85% of national refining capacity. After failing to secure British ownership, its board sold 75% to Standard Oil in 1898, absorbing its Canadian subsidiaries. Post-1911 antitrust breakup, Imperial remained legally distinct but was wholly assigned to Jersey Standard — becoming Standard Oil’s exclusive vehicle for Canadian operations.

Nintendo’s origin is a case study in operational discipline over narrative ambition. It succeeded by controlling production hardware, exploiting regulatory shifts, and locking in high-frequency buyers — not by inventing games or chasing culture.
Norsk Hydro began as a single-purpose vehicle for Birkeland’s nitrogen-fixing arc — a physics experiment turned factory. Its early dominance came not from IP or management, but from locking in Norway’s hydropower geography. It survived obsolescence not through reinvention, but by ceding chemical control to IG Farben. Its WWII role — sole European heavy water producer — was accidental infrastructure reuse. Its current aluminium and renewables business shares no technology with its origin, only its dams, debt, and place.
POSCO is a state-created steelmaker that achieved scale and productivity through sovereign backing — not market signals or founder vision.
Salesforce is a case study in narrative-first SaaS scaling: built on a slogan, funded by subscription growth, extended by platform logic, and recalibrated by AI-driven cost shifts—not disruption, but disciplined iteration.

Tencent is a Chinese multinational technology conglomerate and holding company, co-founded in 1998 in Shenzhen. It is one of the highest-grossing multimedia companies globally by revenue and the world’s largest company in the video game industry by equity investments. Its first product, OICQ, launched in February 1999 and reached over one million registered users by year-end 1999. In 2000, Tencent secured $2.2 million in venture capital funding and adapted its platform for mobile messaging — generating 80% of revenue via telecom operator fee-sharing deals. After losing a U.S. arbitration case over domain names, it renamed OICQ to QQ in December 2000. By 2004, it held 74% of China’s instant messaging market and listed on the Hong Kong Stock Exchange.
McDonald's is not a restaurant chain but a replication system — built on enforceable standardisation and deliberately constrained franchising. Its economics rely on control, not volume, and its origin story is a legal rebranding of a hostile acquisition.
Visa is a payment infrastructure built on delegation: banks issue cards, Visa provides the rails and branding, and consumers pay fees embedded in every transaction. Its 1970 restructuring into a member-owned, decentralised association — conceived and led by Dee Hock — was a deliberate rejection of hierarchy. Yet its 2025 volume ($14.2 trillion) reflects not distributed decision-making but tightly coordinated standards enforcement. The ‘chaordic’ ideal remains descriptive, not operational.
Hyundai Motor is a state-facilitated, scale-first automaker whose power lies in integration — not invention. It controls the largest single auto plant on earth, ranks third globally by output, and sells more hybrids than EVs. Its origin story is contested across sources. Its value is in execution, not narrative.
De Beers is a case study in artificial scarcity — built not on geology or technology, but on merger, capital, and contract.
Lukoil is a Russian multinational energy corporation headquartered in Moscow, formed in 1991 by merger of three state-run western Siberian oil enterprises: Langepasneftegaz, Urayneftegaz, and Kogalymneftegaz.
Vestas is a Danish wind turbine company founded in 1945, engaged in manufacturing, selling, installing, and servicing turbines globally; it details major operational milestones including global installations, R&D investment and patenting activity, strategic mergers, facility expansions and closures, and technical innovations such as stealth blades and floating turbines.
H&M is a Swedish multinational clothing company headquartered in Stockholm, founded in 1947 by Erling Persson in Västerås as a women’s-only retailer named Hennes. Built on a fast fashion business model, it sells apparel, accessories, and homeware. In 1968, Persson acquired the hunting apparel retailer Mauritz Widforss, added menswear, and changed the name to Hennes & Mauritz. The company was listed on the Stockholm Stock Exchange in 1974 and opened its first store outside Scandinavia in London in 1976. It began online retailing in 1998 using the domain hm.com, registered in 1997.
ArcelorMittal is the world’s second-largest steelmaker — a $33 billion hostile merger of Mittal Steel and Arcelor in 2007. It operates across mining, smelting, and recycling in 14 countries. In 2025, it produced 55.6 million tons of steel against 74.6 million tons of capacity — 53% in Europe, 40% in the Americas. It sources 72% of its iron ore and 91% of its coke internally. The Mittal family surrendered control to close the deal. It is not a technology company. It is not growing. It is a vertically integrated commodity producer whose scale is structural, not strategic.
Apollo Global Management is a $1.03 trillion alternative asset manager built on distressed-to-control investing, co-founded in 1990 by ex-Drexel bankers. It earns fees from pension funds, endowments, and sovereign wealth funds deploying capital across credit, private equity, and real assets. Its model works at scale—but its credibility fractures where leadership conduct contradicts its governance claims. The $158 million paid to Jeffrey Epstein did not disrupt operations, but it ended Leon Black’s tenure and exposed a rift between Apollo’s discipline-as-brand and its human risk.
Epic Games is a vertically integrated software and entertainment company whose business model relies on cross-subsidising its store and engine through a hit game. Its self-portrait as a developer ally conflicts with its contractual terms and revenue structure. The gap between that story and its mechanics is where the real lesson lies.

SoftBank Group is a Japanese investment holding company founded in 1981 as a software distributor, restructured as a holding company in 1999, and renamed SoftBank Group Corp in 2015. It focuses exclusively on investment management — primarily in technology companies across diverse markets. Its Vision Fund, launched in 2017 with $100 billion, was the world’s largest technology-focused venture capital fund at inception. SoftBank went public in 1994 with a $3 billion valuation. In 2016, it announced a $50 billion U.S. investment commitment targeting 50,000 jobs. From 2023, it shifted strategy toward AI infrastructure and semiconductor-related investments — a direction confirmed by Masayoshi Son’s January 2025 chairmanship of Stargate LLC.
Xiaomi is a Beijing-based Chinese multinational founded in 2010 by Lei Jun and six others. It operates in consumer electronics, software, and electric vehicles. It launched its first smartphone in August 2011 and entered the smart electric vehicle industry in March 2021.
Shopify is a Canadian multinational cloud e-commerce management platform for retail point-of-sale systems, founded in 2006 by Tobias Lütke, Daniel Weinand, and Scott Lake. In 2024, it processed US$292.3 billion in transactions, with 5 million customers. Its software is praised for ease of use and reasonable fee structure, and it is described as the 'go-to e-commerce platform for startups'. Shopify went public in 2015 and uses a two-class voting structure that grants disproportionate voting control to Lütke despite his minority economic stake.
Free is a vertically integrated French ISP that built its own networks, hardware, and pricing model — rejecting reliance on incumbents and subscription lock-in. It achieved profitability and low churn through infrastructure control and disciplined bundling, not venture funding or hype.
Anthropic positions itself as a safety-first AI builder—but its business runs on proprietary models trained with legally contested data, sold under restrictive partnerships, and governed by self-declared public benefit terms that do not prevent mass-scale book scanning or billion-dollar copyright liability.

Porsche began as a contract engineering firm — not a carmaker. Its first product was the Volkswagen Beetle, designed for the German government in 1931. It earned royalties on every Beetle built. Only in 1948 did it sell its first car under its own name: the 356, built by hand in a Gmünd sawmill using Beetle-sourced components due to post-war scarcity. Over 78,000 356s were made across 17 years — but the company’s revenue came first from consulting, then royalties, not car sales.

TikTok is a Chinese-origin short-form video platform launched internationally by ByteDance in September 2017 as the overseas counterpart to Douyin. It uses AI-driven recommendation algorithms to connect creators with audiences. It surpassed two billion mobile downloads by April 2020. Its corporate entity, TikTok Ltd, is incorporated in the Cayman Islands and headquartered in Singapore and Los Angeles. Zhang Yiming founded ByteDance in 2012 and explicitly framed global expansion as essential because China accounts for only one-fifth of global internet users. ByteDance acquired Musical.ly for US$800 million in August 2018 and integrated it into TikTok.
JBS S.A. is the world’s largest meat processor by sales. On May 30, 2021, ransomware disabled its beef and pork slaughterhouses in the US, Canada, and Australia. It paid $11 million in Bitcoin. The White House attributed the attack to a Russian organisation; news outlets named REvil. REvil did not claim responsibility before its infrastructure vanished on July 13, 2021.
ABB is a post-merger industrial incumbent whose value lies in proven, regulated, physical infrastructure — not software, platforms, or scalability stories.
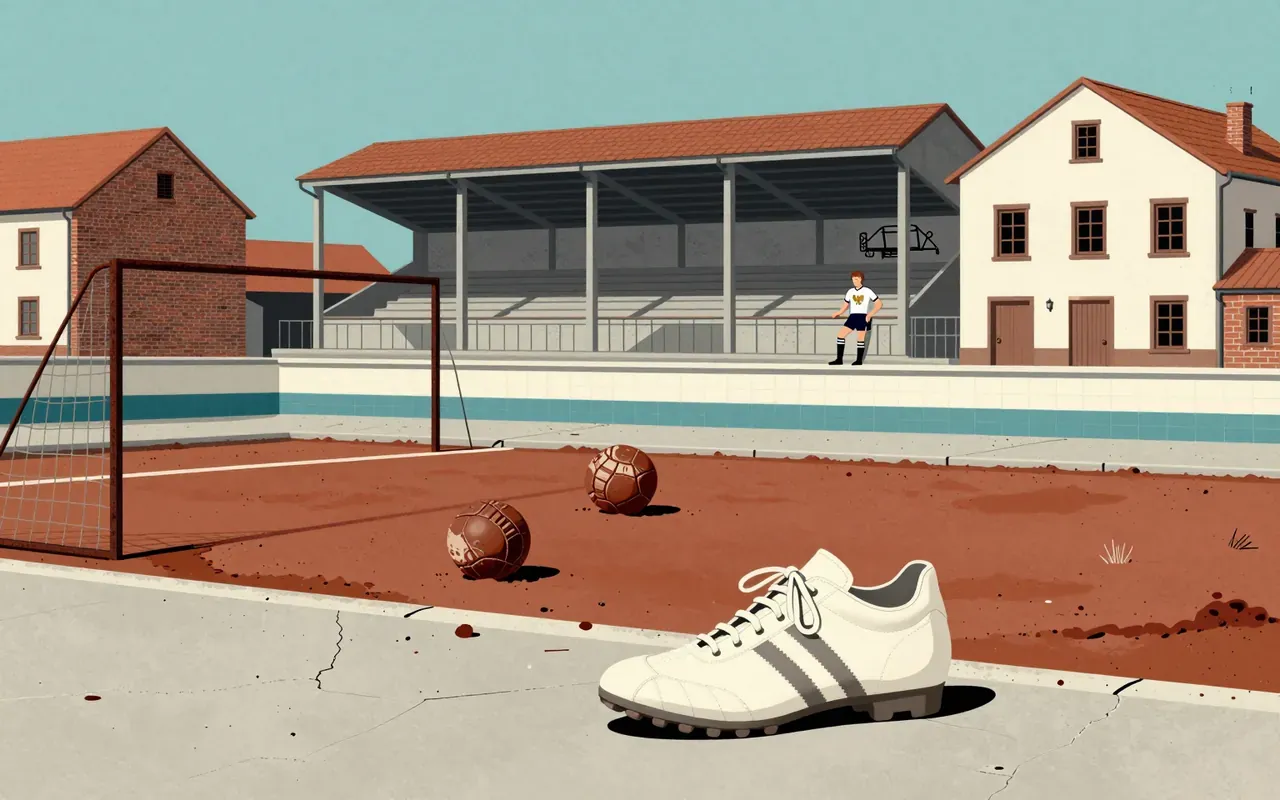
Adidas is a German multinational athletic apparel and footwear corporation headquartered in Herzogenaurach. It was founded by Adolf Dassler in 1948, following the breakup of the Dassler Brothers Shoe Factory. Adidas makes money selling athletic apparel and footwear. Its revenue in 2024 was €23 billion. It operated 17 factories and generated one billion Deutschmarks in annual sales by 1978. Dassler’s focus on functional footwear innovation worked: he redesigned spiked running shoes, introduced interchangeable screw-in studs for football boots, and secured high-visibility athlete adoption (Jesse Owens, 1936). The three-stripe logo became a registered trademark in 1949 and a scalable visual identifier. The 1924 Dassler Brothers Shoe Factory was a shared venture — not Adidas — and dissolved in 1948 amid a rift. Post-war material shortages forced rapid reconversion from weapons to shoes — yet Adidas hit one billion Deutschmarks in sales by 1978. Adidas shows how a narrow technical advantage — screw-in studs, canvas-rubber spikes, the three-stripe trademark — can anchor decades of manufacturing expansion when paired with strict control over production, branding, and distribution channels. Yes — as a case study in how technical footwear innovation, trademark discipline, and athlete-led validation built industrial scale in post-war Europe — but only if you treat its origin story as a business reconstitution, not a founding myth.
KLM was not a private venture but a state-backed aviation instrument. Its longevity stems from institutional alignment — not market innovation.
Kodak was not a camera company first — it was a film company that used cameras to distribute its consumable. Its 1888 system created a new market by removing technical barriers. Its dominance came from controlling the film supply chain, not the hardware. No source mentions digital disruption, so the brief stops at peak film-era success.

Godrej & Boyce is not a story of disruption but of continuity — sustained by refusing to outsource precision, testing claims in fire, and anchoring engineering to national need. Its business model has never been about scaling a single product, but about retaining sovereign capability across generations.

Daewoo was a South Korean chaebol founded in March 1967 by Kim Woo-choong as a small textiles trading corporation. It expanded using government-sponsored cheap loans tied to export potential, acquiring near-bankrupt companies across shipbuilding, electronics, and automotive sectors. By the 1990s, it ranked second largest in assets and third in revenues among South Korean conglomerates. It collapsed in November 1999 with $50 billion in debt after the 1997 Asian financial crisis exposed its reliance on continuous credit. Its story reveals how state-backed finance can substitute for profitability — until it cannot.